Guía de estudio · Edición 2026
Series 66 — Uniform Combined State Law — Complete Study Guide (2026)
Nineteen chapters that follow NASAA's four content areas, law first.
- Extensión
- 747 páginas (193 de enseñanza + banco de preguntas)
- Preguntas de práctica en el libro
- 1,161
- Simulacro en línea de PrepPass
- 100 preguntas · 150 min
- Datos verificados y archivo actualizado
- octubre de 2026
- Entrega
- PDF + EPUB · en inglés · descarga inmediata
Léelo antes de comprar: This is an independent study aid, not affiliated with or endorsed by NASAA, FINRA, or Prometric.
Leer el resto de este aviso
The Series 66 is a NASAA exam administered by FINRA; this guide is authored from the public Uniform Securities Act, NASAA model rules, and the Investment Advisers Act of 1940. Some dollar thresholds (the qualified-client net worth/AUM figures, the gift-tax exclusion) are indexed and change — this guide teaches the underlying rules and flags indexed figures to 'verify current year'; it is general educational information, not legal or investment advice.
Sobre este libro
Nineteen chapters that follow NASAA's four content areas, law first: the Uniform Securities Act, NASAA model rules and the Investment Advisers Act of 1940, plus the economics and product knowledge the Series 66 tests.
Tarifa del examen: $177 por intento, que se paga a FINRA. Repetir el examen vuelve a costarlo. Esta guía: $24.99, pago único.
Datos del examen, a quién le sirve y qué cambió
Sobre el examen en sí
| Organismo administrador | North American Securities Administrators Association (NASAA) — examen administrado por FINRA |
|---|---|
| Preguntas | 110 preguntas (100 calificadas, 10 de prueba sin calificar) |
| Tiempo límite | 150 minutos |
| Puntuación para aprobar | 73 de 100 correctas |
| Tarifas |
Fuente: NASAA — Exam FAQs |
| Idiomas disponibles | Inglés Fuente: NASAA — Exam FAQs |
Mira dentro del libro
Tres páginas reales, renderizadas directamente del PDF que descargas — una página de referencia, una de explicación y una pregunta resuelta, siempre en ese orden. Nada se rediseñó para verse mejor.
- Referencia rápidaAppendix — Question Bank 1,161 practice questions with answers and explanations · Página 628 del PDF
Una página a la que puedes volver: cifras, plazos o términos reunidos en un solo lugar.
- Cómo se enseñaChapter 14 — Equity and Valuation Common stock, ADRs and shareholder rights · Página 153 del PDF
Una página de explicación: el material enseñado en prosa, en el orden en que lo evalúa el examen.
- Una pregunta resueltaAppendix — Question Bank 1,161 practice questions with answers and explanations · Página 356 del PDF
Una pregunta de práctica con su respuesta y el razonamiento detrás — no solo la clave.
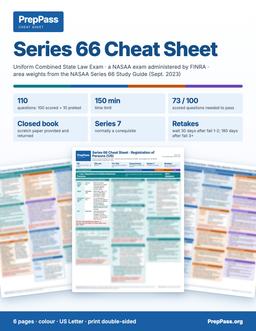
¿Examen en menos de dos semanas?
Esta guía es la enseñanza, para leer durante semanas. Si tu examen es en menos de dos semanas, la hoja de referencia a color imprimible es el otro producto: las cifras clave, por secciones.
6 páginas · US Letter · PDF imprimible · tuyo para siempre
Qué incluye — y qué no
Incluido
- Nineteen chapters covering NASAA's four content areas, law first (45%), with a table mapping the chapters to the official weights
- Every chapter closes with a key-facts box and a named exam-traps list
No incluido
- No se envía copia impresa — es un archivo que descargas y puedes imprimir tú
- El libro no incluye curso en vídeo, instructor ni tutorías — los vídeos gratis del sitio van aparte
Todo lo incluido y todo lo que no
Incluido
- Registration of broker-dealers, agents, advisers and representatives, exempt securities versus exempt transactions, Administrator powers, the Investment Advisers Act of 1940 and fiduciary duty
- Worked math: Sharpe ratio, beta, CAPM, taxable-equivalent yield, duration, time value of money
- Prohibited and unethical business practices, the most heavily tested trap area
- 193 pages of teaching, then a question bank of 1161 practice questions, grouped by topic, with answers and explanations
- PDF (print & tab it) + EPUB (phone / e-reader)
No incluido
- No incluye tu inscripción al examen ni la tasa del centro, que sigues pagando al organismo oficial
Contenido
Ver 21 secciones y la página en la que empieza cada una
- Chapter 1 — Federal Law Foundationsp. 11
- Section 15: broker-dealers register with the SEC, join a self-regulatoryp. 21
- Chapter 2 — Adviser Registration and Compliance Investment adviser representatives, qualificationp. 24
- Chapter 3 — Broker-Dealer and Agent Registration, Records and Supervisionp. 33
- Chapter 4 — The State Act, 1956 and 2002, and Communicationsp. 42
- Chapter 5 — Conduct, AML, Privacy, Seniors and Due Diligencep. 54
- Chapter 6 — FINRA Rules and Regulation Best Interestp. 64
- Chapter 7 — Client Types and Profilingp. 70
- Chapter 8 — Strategies and Techniques Modern portfolio theory and the efficient frontierp. 78
- Chapter 9 — Taxation Income tax brackets and marginal rates (2026)p. 85
- Chapter 10 — Retirement Plans and ERISA Retirement plan types and 2026 limitsp. 95
- Chapter 11 — Education, Health, Ownership and Estatep. 107
- Chapter 12 — Trading and Returns Order types and how they executep. 119
- Chapter 13 — Cash and Fixed Income Insured deposits and the money marketp. 130
- Chapter 14 — Equity and Valuation Common stock, ADRs and shareholder rightsp. 142
- Chapter 15 — Offerings and Equity Compensationp. 151
- Chapter 16 — Pooled Products and Derivatives Unit investment trusts, ETFs and REITsp. 160
- Chapter 17 — Annuities, Insurance, Alternatives and Digital Assetsp. 172
- Chapter 18 — Quantitative Methodsp. 181
- Chapter 19 — Financial Ratios and Valuation Modelsp. 188
- Appendix — Question Bank 1,161 practice questions with answers and explanationsp. 194
Tomado del PDF que descargas, con la página en la que empieza cada uno — no escrito a mano aquí.
Lee un capítulo completo gratis
Un capítulo completo, tal como viene en el eBook. Desplázate en la ventana para leerlo aquí; sin descargas ni correo.
Lee el capítulo 18 aquí, sin salir de la página
No te dimos la introducción fácil — el capítulo gratis abre en una de las partes más exigentes del libro, para que juzgues la enseñanza donde el examen se pone difícil.
Time value of money: future value, present value, NPV and IRR
Money received sooner is worth more than money received later, because it can be invested. All the formulas below use one idea: moving a dollar amount across time at a rate of return.
Future value
FV = PV x (1 + r)^n
Worked example. $10,000 invested at 6% a year for 8 years: $10,000 x 1.06^8 = $10,000 x 1.5938 = $15,938.48.
If interest compounds quarterly the rate per period is 6% / 4 = 1.5% and there are 8 x 4 = 32 periods: $10,000 x 1.015^32 = $16,103.24. More frequent compounding gives a larger amount.
Rule of 72. Years to double is about 72 divided by the annual rate in percent. At 6%, 72 / 6 = 12 years. Check: $10,000 x 1.06^12 = $20,121.96. The rule is an approximation that works best between 6% and 10%.
Present value
PV = FV / (1 + r)^n
Worked example. A client wants $20,000 in 5 years and can earn 7%. PV = $20,000 / 1.07^5 = $20,000 / 1.4026 = $14,259.72. The client needs $14,259.72 today.
Present value of a series. To receive $1,000 at the end of each year for 5 years with a 6% discount rate, discount each payment: $943.40 + $890.00 + $839.62 + $792.09 + $747.26 = $4,212.36.
A higher discount rate gives a lower present value; a longer time gives a lower present value.
Net present value
NPV is the sum of the present values of all cash flows, including the initial outlay, discounted at the required rate of return.
Worked example. A project costs $10,000 now and returns $3,000, $4,000 and $5,000 at the end of years 1, 2 and 3. The required return is 8%.
| Year | Cash flow | Discount factor | Present value |
|---|---|---|---|
| 0 | -$10,000 | 1.0000 | -$10,000.00 |
| 1 | $3,000 | 1/1.08 | $2,777.78 |
| 2 | $4,000 | 1/1.08^2 | $3,429.36 |
| 3 | $5,000 | 1/1.08^3 | $3,969.16 |
| NPV | +$176.29 |
NPV is positive, so the project earns more than 8% and adds value. Decision rule: accept if NPV is greater than zero; reject if negative. The profitability index (present value of inflows / outlay) is 10,176.29 / 10,000 = 1.018.
Internal rate of return
IRR is the discount rate at which NPV equals zero. There is no direct formula. Solve by trying rates.
Worked example (same project).
| Trial rate | NPV |
|---|---|
| 8% | +$176.29 |
| 9% | -$20.07 |
| 10% | -$210.37 |
The sign changes between 8% and 9%, so the IRR is just under 9%. Linear interpolation between 8% and 10%: 8% + 2% x 176.29 / (176.29 + 210.37) = 8% + 0.91% = 8.91%. Refining gives IRR = 8.90%. At 8.90%, NPV is almost exactly zero.
Decision rule: accept if IRR is greater than the required return (8.90% > 8%: accept). The NPV and IRR rules agree here.
When NPV and IRR disagree. For mutually exclusive projects of different size or cash-flow timing, IRR can rank the projects differently than NPV. NPV assumes cash flows are reinvested at the required rate; IRR assumes reinvestment at the IRR itself, which is less realistic. A project with cash flows that change sign more than once can have more than one IRR. In these cases NPV is the better guide because it measures the dollar value added.
Where it appears in advice. IRR is used to compare investments with irregular cash flows, such as private equity. The money-weighted return of a portfolio with deposits and withdrawals is an IRR.
Key facts — Time value of money: future value, present value, NPV and IRR - FV = PV x (1 + r)^n; PV = FV / (1 + r)^n. - Rule of 72: doubling time = 72 / rate. - NPV > 0: accept. IRR > required return: accept. - IRR is the rate at which NPV = 0. - NPV is preferred when NPV and IRR conflict.
Exam traps
- Using the annual rate with monthly periods.
- Forgetting the initial outlay in NPV.
- Assuming a higher IRR project is always better than a larger project with a higher NPV.
Descriptive statistics: mean, median, mode, range and standard deviation
Mean, median, mode and range
Worked example. A fund's monthly returns (in percent) over seven months: 4, 8, 6, 5, 3, 8, 9.
- Sort: 3, 4, 5, 6, 8, 8, 9.
- Mean = (4 + 8 + 6 + 5 + 3 + 8 + 9) / 7 = 43 / 7 = 6.14.
- Median = the middle value of the sorted list = 6. With an even count, the median is the average of the two middle values; for 2, 4, 7, 9 the median is (4 + 7) / 2 = 5.5.
- Mode = the most frequent value = 8.
- Range = highest minus lowest = 9 - 3 = 6.
The median is not changed by an outlier; the mean is. If the last value were 90, the mean would jump while the median would stay at 6.
Arithmetic and geometric mean. The arithmetic mean averages the returns. The geometric mean gives the true compound rate. A fund that gains 50% one year and loses 50% the next has an arithmetic mean of (50% + (-50%)) / 2 = 0%, but $100 becomes $150 then $75. The geometric mean is the square root of (1.50 x 0.50) minus 1 = square root of 0.75 minus 1 = -13.40% a year. The geometric mean is always at most the arithmetic mean, and the gap grows with volatility.
Standard deviation, calculated by hand
Standard deviation (SD) measures how far returns scatter around their mean. It is the square root of the variance.
Worked example. Four annual returns: 10%, 4%, -2%, 8%.
- Mean = (10 + 4 - 2 + 8) / 4 = 5.
- Deviations from the mean: 5, -1, -7, 3.
- Squared deviations: 25, 1, 49, 9. Sum = 84.
- Population variance (divide by n = 4) = 84 / 4 = 21. SD = square root of 21 = 4.58%.
- Sample variance (divide by n - 1 = 3) = 84 / 3 = 28. SD = square root of 28 = 5.29%.
Use the sample SD when the returns are a sample of a longer record (the usual case for a fund's history); use the population SD when the data are the whole group.
Interpretation. For a roughly normal distribution, about 68% of outcomes fall within one SD of the mean, 95% within two, and 99.7% within three. A fund with a mean return of 8% and an SD of 12% has a 68% range of -4% to 20% and a 95% range of -16% to 32%.
Coefficient of variation = SD / mean, the risk per unit of return. Fund A has mean 8%, SD 12%: 1.50. Fund B has mean 6%, SD 6%: 1.00. Fund B has less risk per unit of return.
Key facts — Descriptive statistics: mean, median, mode, range and standard deviation - Mean is sensitive to outliers; median is not. - Range = highest - lowest. - Population SD divides by n; sample SD divides by n - 1. - About 68%, 95%, 99.7% within 1, 2, 3 SDs for normally distributed returns. - Geometric mean is at most the arithmetic mean.
Exam traps
- Reading SD as a loss measure. It measures dispersion in both directions.
- Using the arithmetic mean to describe multi-year growth.
- A data set can have no mode, or more than one mode.
Covariance, correlation and combined risk
Covariance measures whether two assets tend to move together. Correlation rescales covariance to a number between -1 and +1:
Correlation = covariance(X, Y) / (SD of X x SD of Y)
Worked example. Annual returns of two funds over four years (in percent):
| Year | Fund X | Fund Y |
|---|---|---|
| 1 | 10 | 6 |
| 2 | 4 | 3 |
| 3 | -2 | 5 |
| 4 | 8 | -2 |
| Mean | 5 | 3 |
- Deviations of X: 5, -1, -7, 3. Deviations of Y: 3, 0, 2, -5.
- Products: 5 x 3 = 15; -1 x 0 = 0; -7 x 2 = -14; 3 x -5 = -15. Sum = -14.
- Sample covariance = -14 / 3 = -4.667.
- SD of X (sample) = 5.29 (from the earlier example). Squared deviations of Y: 9, 0, 4, 25 = 38; variance = 38 / 3 = 12.667; SD of Y = 3.56.
- Correlation = -4.667 / (5.29 x 3.56) = -0.248.
The correlation is weakly negative. Combining the funds should reduce portfolio risk.
Why correlation matters: a two-asset portfolio. Portfolio SD is not the weighted average of the SDs. For weights w1 and w2:
SD(portfolio) = square root of [ (w1 x SD1)^2 + (w2 x SD2)^2 + 2 x w1 x w2 x SD1 x SD2 x correlation ]
With 60% in a stock fund (SD 20%) and 40% in a bond fund (SD 10%), correlation 0.3:
- (0.60 x 20)^2 = 144
- (0.40 x 10)^2 = 16
- 2 x 0.60 x 0.40 x 20 x 10 x 0.3 = 28.8
- Variance = 144 + 16 + 28.8 = 188.8. SD = 13.74%.
The weighted average of the SDs is 0.6 x 20 + 0.4 x 10 = 16%. Diversification cut the risk to 13.74%. If the correlation were +1, the portfolio SD would equal 16%, so there would be no diversification benefit. The lower the correlation, the larger the benefit; at -1 risk can be eliminated with the right weights. Diversification reduces unsystematic risk only; it cannot reduce market risk.
R-squared is the square of the correlation with a benchmark: the share of a fund's movement explained by the benchmark. A correlation of 0.9 gives R-squared of 0.81, meaning 81%.
R-squared is usually read together with tracking error, the amount by which a fund's returns deviate from its benchmark's. A high R-squared says the fund moves with the benchmark. A low tracking error says its returns stay close to the benchmark's. An adviser who wants to know how closely a fund follows its index looks at both: R-squared close to 1 (100%) and a small tracking error describe an index-like fund. Sharpe ratio and standard deviation describe risk-adjusted return and volatility, and beta describes sensitivity to the market; none of them measures how closely a fund follows a benchmark.
Key facts — Covariance, correlation and combined risk - Correlation ranges from -1 to +1. Covariance has no fixed range. - Portfolio SD is less than the weighted average SD unless correlation is +1. - R-squared = correlation squared. - R-squared plus tracking error measure how closely a fund follows its benchmark.
Exam traps
- Correlation of zero means no linear relationship, not no risk.
- A negative covariance does not mean negative returns.
- Diversification does not remove systematic risk.
Preguntas frecuentes
¿Cómo lo recibo?
Paga y la descarga aparece en esta página al instante. Los enlaces también se te envían por correo. No hace falta cuenta.
¿Y si no es para mí?
Escríbenos dentro de 14 días para un reembolso total, sin preguntas.
¿Va a desaparecer la práctica gratis?
No. Todas las preguntas, el simulacro cronometrado y los capítulos gratis del sitio siguen gratis. Este libro es la mitad de estudio, no una valla alrededor de lo gratuito.
Más preguntas (1)
¿Puedo leerlo en el móvil?
Sí — el EPUB es para móviles y e-readers, el PDF para imprimir y marcar. Recibes ambos.
¿Por qué comprar el libro si la práctica es gratis?
Nuestras preguntas de práctica y el simulacro cronometrado siguen gratis: nada del sitio se esconde tras este libro. El libro de $24.99 es la mitad de estudio: el material en sí, explicado en orden, en un archivo tuyo.
- Enseñanza sistemática — cada sección del examen explicada capítulo a capítulo, de principio a fin, no solo preguntas
- Imprímelo y márcalo — un PDF listo para papel que puedes resaltar, anotar y llevar a tu mesa de estudio
- Estudia en cualquier lugar, sin conexión — EPUB en tu teléfono o e-reader; sin wifi, sin pestañas
- Todo en un solo lugar — los capítulos y las preguntas de práctica en un archivo
- Tuyo de por vida — pago único de $24.99, descarga instantánea, sin suscripción
Los detalles
- Verificado con la fuente oficial(Uniform Securities Act, NASAA test specifications and model rules, and the Investment Advisers Act of 1940)
- 1,161 preguntas de práctica gratis
Un Series 66 prep course cuesta $400–$800. Este libro enseña el mismo examen — las mismas reglas, verificadas a los estándares actuales — por un pago único de $24.99 que conservas de por vida.
Compra única, acceso de por vida a la descarga. El eBook es la guía completa de NASAA Series 66 (Uniform Combined State Law) en PDF y EPUB. Resumen educativo, no asesoría profesional ni legal — confirma siempre las reglas vigentes con la fuente oficial. Última actualización: October 2026.