Sách ôn thi · Ấn bản 2026
Series 3 Study Guide — 2026 Edition
Market knowledge and regulations for the NFA National Commodity Futures Examination, written to NFA's study outline, with worked calculations and two full 120-question practice exams.
Phiên bản: Rebuilt Oct 2026 on NFA's study outline · Rules 2-8/2-9 amended Mar 18, 2026 · 120 Q, 150 min, 70% each part
- Độ dài
- 414 trang
- Câu hỏi luyện tập trong sách
- 421
- Thi thử trực tuyến PrepPass
- 100 câu · 125 phút
- Đối chiếu thông tin và cập nhật tệp
- tháng 10 năm 2026
- Giao hàng
- PDF + EPUB · tiếng Anh · tải ngay
Về cuốn sách này
Lệ phí thi: $140 mỗi lần thi, nộp cho FINRA. Thi lại phải nộp lại. Cuốn sách này: $24.99, trả một lần.
Thông tin kỳ thi, ai nên dùng và thay đổi
Về chính kỳ thi này
| Cơ quan quản lý | National Futures Association (NFA) |
|---|---|
| Số câu hỏi | 125 câu hỏi (120 câu tính điểm, 5 câu thử nghiệm không tính điểm) Nguồn: NFA — Study Outline for Futures Industry Exams (Series 3 section and exam table) |
| Thời gian làm bài | 150 phút Nguồn: NFA — Study Outline for Futures Industry Exams (Series 3 section and exam table) |
| Điểm đậu | 70% Nguồn: NFA — Study Outline for Futures Industry Exams (Series 3 section and exam table) |
| Lệ phí |
Nguồn: NFA — Study Outline for Futures Industry Exams (Series 3 section and exam table) |
| Ngôn ngữ thi | NFA and FINRA không công bố Những trang chúng tôi đã đọc và không tìm thấy: NFA — Study Outline for Futures Industry Exams (Series 3 section and exam table) |
Xem bên trong cuốn sách
Ba trang thật, kết xuất thẳng từ tệp PDF bạn sẽ tải — lần lượt là một trang tra cứu, một trang giảng giải, và một câu hỏi có lời giải. Không trang nào được vẽ lại cho đẹp.
- Trang tra cứu nhanhChapter 1 — Futures Trading Theory and the Structure of Futures Markets · Trang 29 của PDF
Một trang để lật lại: các con số, mốc thời hạn hoặc thuật ngữ gom về một chỗ.
- Cách giảng dạySection I — FCMs and introducing brokers (9 questions) · Trang 402 của PDF
Trang giảng giải: kiến thức được trình bày bằng văn xuôi, theo trình tự kỳ thi kiểm tra.
- Một câu hỏi có lời giảiPart 1 — Market Knowledge (85 questions) · Trang 323 của PDF
Một câu luyện tập kèm đáp án và lập luận đằng sau — không chỉ là đáp án.
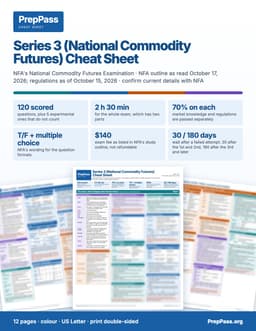
Thi trong vòng hai tuần?
Sách này là phần giảng dạy, đọc trong nhiều tuần. Nếu bạn thi trong vòng hai tuần, bảng tra cứu màu in được là sản phẩm còn lại: các con số then chốt, xếp theo từng phần.
12 trang · US Letter · PDF in được · giữ vĩnh viễn
Có gì — và không có gì
Bao gồm
- An exam-review guide for candidates entering or working in the futures industry: terms are defined as they appear, but it assumes everyday market vocabulary and basic arithmetic, not a first course in trading
- 12 chapters in the order of NFA's Series 3 study outline as read on October 17, 2026
Không bao gồm
- Không gửi bản in — đây là tệp bạn tải về và có thể tự in
- Sách không kèm khoá video, giảng viên hay kèm riêng — video miễn phí trên trang là phần khác
Toàn bộ phần bao gồm và không bao gồm
Bao gồm
- Two full 120-question practice exams, each split 85 market knowledge / 35 regulations (PrepPass's split; NFA publishes none), scored part by part
- Step-by-step worked calculations: margin and variation, basis and hedges in the markets the outline names, spreads, speculative profit and return, option strategies and option spreads
- Current NFA and CFTC rules, including Rules 2-8, 2-9 and 3-1 as amended March 18, 2026, and the pending small-pool exemption proposal
- A common-mistakes list in every chapter, a formula and numbers sheet, a key-terms table and an exam-facts table
- 421 original questions, each with a worked explanation citing its source
- PDF + EPUB you keep
Không bao gồm
- Không bao gồm lệ phí đăng ký thi hay phí trung tâm khảo thí — bạn vẫn nộp cho cơ quan chính thức
Mục lục
Xem 28 phần và trang bắt đầu của từng phần
- Chapter 1 — Futures Trading Theory and the Structure of Futures Marketstr. 11
- Chapter 2 — Futures and Options Terminologytr. 37
- Chapter 3 — Margins, Option Premiums, Price Limits, Settlement, Delivery, Exercise and Assignmenttr. 57
- Chapter 4 — Orders, Customer Accounts and Price Analysistr. 87
- Chapter 5 — Hedging and Basis Calculationstr. 116
- Chapter 6 — Spreadingtr. 144
- Chapter 7 — Speculating in Futures: Profit, Loss and Returntr. 160
- Chapter 8 — Options: Hedging, Speculating and Spreadingtr. 176
- Chapter 9 — Registration, NFA Membership and Opening Customer Accountstr. 204
- Chapter 10 — FCMs and Introducing Brokerstr. 231
- Chapter 11 — Commodity Pool Operators, Commodity Trading Advisors and Promotional Materialtr. 257
- Chapter 12 — Arbitration, NFA Discipline and CFTC Enforcementtr. 281
- Part 1, A: futures theory, 1-18 Chapters 1 and 2 market structure, terminologytr. 304
- Part 1, B: margins, limits, 19-30 Chapter 3 delivery, exercisetr. 304
- Part 1, C: orders and price 31-40 Chapter 4 analysistr. 304
- Part 1, D: hedging and basis 41-55 Chapter 5tr. 304
- Part 1, E: spreading 56-64 Chapter 6tr. 304
- Part 1, F: speculation, profit, 65-72 Chapter 7 loss and returntr. 304
- Part 1, G: options strategies 73-85 Chapter 8tr. 304
- Part 2, H: registration, NFA 1-11 Chapter 9 membership, customer accountstr. 304
- Part 2, I: FCMs and 12-20 Chapter 10 introducing brokerstr. 304
- Part 2, J: CPOs, CTAs, 21-28 Chapter 11 promotional materialtr. 304
- Part 2, K: arbitration, 29-35 Chapter 12 discipline, enforcementtr. 304
- Part 1 — Market Knowledge (85 questions)tr. 304
- Part 2 — Regulations (35 questions)tr. 334
- Section I — FCMs and introducing brokers (9 questions)tr. 336
- Appendix A — The exam at a glance, in one tabletr. 404
- Appendix B — Terms the exam expects you to use preciselytr. 405
Lấy từ chính tệp PDF bạn tải về, kèm trang bắt đầu của từng phần — không phải gõ tay ở đây.
Đọc miễn phí trọn một chương
Trọn vẹn một chương, đúng như trong eBook. Cuộn cửa sổ để đọc ngay tại đây; không cần tải, không cần email.
Đọc chương 5 ngay tại đây, không rời trang
The free chapter is Chapter 5, hedging and basis calculations: worked examples at the pace of the whole book, which defines its terms in Chapters 1 and 2 and assumes everyday market vocabulary and basic arithmetic.
This is the chapter the market-knowledge part is built around. NFA's outline gives it three headings — short and long hedging, the basis, and hedging calculations — and then lists examples in grains, livestock, foodstuffs, metals, energy, lumber, Treasury notes and bonds, T-bills and 3-month SOFR, municipals, currencies and stock indices[1]. Every one of those examples is solved with the same small set of rules. Learn the rules, then practice until the sign of the basis never trips you.
The basis
Definition and sign
Basis is the difference between the cash (spot) price of a commodity and the price of the nearest futures contract for the same or a related commodity, typically calculated as cash minus futures[2].
Basis = cash price − futures price
If cash is $4.10 and futures are $4.35, the basis is −$0.25, spoken "25 under." If cash is $4.50 and futures $4.35, the basis is +$0.15, "15 over." Merchants quote cash prices this way: a basis quote is an offer or sale of a cash commodity in terms of the difference above or below a futures price, such as "10 cents over December corn"[2].
How the basis is determined
The CFTC notes that the basis is usually computed against the futures contract next to expire and may reflect differences in time, product form, grade or location[2]. In practice, four things set a local basis:
- Transportation costs. A futures contract prices the commodity at its delivery points[2]. A grain elevator far from a delivery point pays less for grain than the futures price, because someone must pay to ship it to where the contract is priced. Farther away, weaker basis; closer to demand, stronger basis.
- Variation in grades. Futures price the par grade[2]. A cash lot of better quality commands a premium; a lower grade, a discount[2]. That difference shows up in the basis.
- Time and carrying charges. A cash price today compared with a futures price for a later month reflects the cost of carrying the commodity until then[2]. That is why the basis in a normal market tends to strengthen (move toward zero) as delivery approaches: the remaining carrying cost shrinks.
- Local supply and demand. A local shortage strengthens the basis; a local glut weakens it.
Strengthening and weakening
Because the basis is a signed number, describe changes by direction rather than by "wider" or "narrower," which are ambiguous when the basis crosses zero:
- Strengthening — the basis becomes more positive (or less negative): −30 to −10, or +5 to +20. Cash is gaining on futures.
- Weakening — the basis becomes more negative (or less positive): −10 to −30, or +20 to +5. Cash is losing ground to futures.
NFA's outline also uses "narrowing or widening basis" in the spread section[1]. When you meet those words, translate them into strengthening or weakening by writing out the numbers.
Basis risk
Basis risk is the risk of an unexpected widening or narrowing of the basis between the time a hedge is placed and the time it is lifted[2]. A hedge converts price risk into basis risk. Price risk is large and unpredictable; basis risk is usually smaller and more predictable, because transportation, grade and carrying costs change slowly. That trade is the whole economic reason to hedge.
Long the basis, short the basis
The CFTC's definitions give the two positions their names:
- Long the basis — a person who has bought the spot commodity and hedged with a sale of futures[2]. This is the short hedger: long cash, short futures.
- Short the basis — the purchase of futures as a hedge against a commitment to sell in the cash market[2]. This is the long hedger, who is effectively short cash (committed to deliver, or needing to buy) and long futures.
The names tell you who benefits from a basis change, exactly as "long" and "short" do for prices:
Long the basis (short hedger) gains when the basis strengthens. Short the basis (long hedger) gains when the basis weakens.
Prove it once, then trust it. The short hedger owns cash and is short futures. If the basis strengthens, cash has risen relative to futures: the cash side gained more (or lost less) than the futures side lost (or gained). The hedger is long the thing that outperformed.
Short hedging
A short (selling) hedge sells futures to protect against falling prices[2]. Typical short hedgers are farmers, producers and holders of inventory[1].
Net price received
For a short hedger who sells the cash commodity and buys back the futures on the same day:
Net sale price = cash price received + futures gain (or − futures loss) = futures price when the hedge was placed + basis when the hedge is lifted
The second line is the shortcut: the hedge locks in the original futures price, and the basis at the end is added to it.
Worked example — basis strengthens. In June a farmer expects to harvest 30,000 bushels and sells six 5,000-bushel December futures at $4.80. Her local basis for harvest delivery has typically been 40 under.
In October she sells the cash corn at $4.15 when December futures are $4.45.
- Basis at lift: $4.15 − $4.45 = −$0.30 (30 under), stronger than the −$0.40 she expected.
- Futures gain: $4.80 − $4.45 = $0.35.
- Net price: $4.15 + $0.35 = $4.50 — which equals $4.80 + (−$0.30).
- The 10-cent basis improvement adds $0.10 × 30,000 = $3,000 compared with the $4.40 she had planned on.
Worked example — basis weakens. Same hedge, but at harvest cash is $3.95 and futures $4.45 (basis 50 under). Net price = $3.95 + $0.35 = $4.30 = $4.80 − $0.50. The weaker basis cost her 10 cents compared with the expected $4.40.
Holders of inventory
An elevator that buys grain and stores it is long the basis while it carries the grain. Worked example. In October an elevator buys corn at $4.05 when March futures are $4.55 (basis −50) and sells March futures to hedge. In February it sells the corn at $4.60 when March futures are $4.70 (basis −10).
- Cash gain: $4.60 − $4.05 = +$0.55.
- Futures loss: $4.55 − $4.70 = −$0.15.
- Net result: +$0.40 per bushel — exactly the 40-cent strengthening of the basis, from −50 to −10.
A storage hedger does not care where prices go; it earns the basis change, which is its payment for storing.
Long hedging
A long (buying) hedge buys futures to protect against increases in the cost of commodities[2]. Typical long hedgers are processors, manufacturers and exporters[1].
Net price paid
Net purchase price = cash price paid − futures gain (or + futures loss) = futures price when the hedge was placed + basis when the hedge is lifted
It is the same shortcut. A long hedger, being short the basis, wants that closing basis to be as weak (as negative) as possible.
Worked example. In March a feed manufacturer knows it will buy 50,000 bushels of soybeans in July. It buys July futures at $11.60 when its expected July basis is +$0.20. In July it buys cash at $12.30 when futures are $12.00.
- Basis at lift: $12.30 − $12.00 = +$0.30 (stronger than the expected +$0.20).
- Futures gain: $12.00 − $11.60 = +$0.40.
- Net purchase price: $12.30 − $0.40 = $11.90 = $11.60 + $0.30.
- The long hedger expected $11.80 and paid 10 cents more, because the basis strengthened against it.
Anticipatory hedges
A hedge placed before the hedger has the cash position — a processor buying futures for next quarter's needs, or a farmer selling futures before planting — is an anticipatory hedge. The CFTC's definition of a hedger covers someone who buys or sells futures "as a temporary substitute for a cash transaction that will occur later"[2]. An exporter that has agreed to sell grain abroad at a fixed price but has not yet bought it is short the cash commodity and hedges by buying futures.
Effect of the basis on the commodity actually delivered or purchased
Hedgers rarely deliver on futures; they buy and sell in their local cash market and offset their futures. That is why the local basis, not the futures price alone, determines the outcome. If a hedger does deliver against futures, the price received is the futures invoice price[2] adjusted for any grade premium or discount[2] — and the hedger bears the cost of getting the commodity to a delivery point[2]. A hedger far from a delivery point usually does better selling locally and buying back futures.
Hedging calculations: a method that never fails
For any hedge question, write four lines:
| Cash | Futures | Basis | |
|---|---|---|---|
| Start | price | price | cash − futures |
| End | price | price | cash − futures |
| Change | ± | ± | ± |
Then:
- Mark which side the hedger is long and which short.
- Gain or loss on each side = change × (+1 if long, −1 if short).
- Net result = sum of the two sides = basis change × (+1 if long the basis, −1 if short the basis).
- Net price = the actual cash price ± the futures result.
Worked example — the full table. A cattle feeder will sell 40,000 pounds of cattle in four months. She sells one 40,000-pound futures contract at $1.92 per pound when cash is $1.86.
| Cash | Futures | Basis | |
|---|---|---|---|
| Start | $1.86 | $1.92 short | −$0.06 |
| End | $1.78 | $1.81 buy back | −$0.03 |
| Change | −$0.08 | +$0.11 gain | +$0.03 (stronger) |
She is long the basis (long cattle, short futures), so she gains the 3-cent strengthening. Net price = $1.78 + $0.11 = $1.89 per pound = $1.92 + (−$0.03). In dollars: 40,000 × $1.89 = $75,600.
The basis in financial markets
Financial futures have a basis too, and the same arithmetic applies. What differs is what drives it.
Carry: short-term versus long-term rates
For a financial instrument, carrying costs are the cost of financing — the short-term rate — and the "income" of carrying is the instrument's own return. When financing costs less than the instrument earns, the CFTC calls it positive carry; when it costs more, negative carry[2]. With a positive yield curve (long-term rates above short-term)[2], holding a long-term bond financed at short-term rates earns positive carry, so deferred bond futures can trade below nearby futures and below cash. This is why financial markets often look "inverted" without any shortage — the outline's "short-term rates vs. long-term rates"[1].
Interest-rate hedges
Debt prices fall when yields rise[3], so:
- An investor holding Treasury notes or bonds (long cash) fears rising rates and sells note or bond futures — a short hedge.
- A borrower planning to issue debt or take a floating-rate loan fears rising rates and sells interest-rate futures (T-bill, SOFR, note or bond futures, depending on the maturity) — an anticipatory short hedge.
- An investor who will receive cash later and fears falling rates buys interest-rate futures — an anticipatory long hedge.
Treasury bills are short-term zero-coupon obligations of up to one year; notes run more than one and up to ten years; bonds more than ten[2]. Match the hedge to the maturity of the risk: short-term borrowing costs are hedged with short-term-rate contracts, long-term bond holdings with bond futures. Rates are measured in basis points; one basis point is 1/100 of one percent[2]. Don't confuse this with "the basis."
Cross-hedging: municipals and other close substitutes
A cross-hedge hedges a cash position with futures on a different but price-related commodity[2]. A dealer holding municipal bonds, for example, may hedge with Treasury futures or a municipal-bond-index contract because the prices tend to move together. Cross-hedges carry extra basis risk: the two prices can diverge for reasons that have nothing to do with the general level of rates. The hedge ratio — the value of futures bought or sold relative to the value of the cash position — is computed to minimize that basis risk[2].
Currencies
An exchange rate is the price of one currency in terms of another[2]. Currency hedges follow the ordinary rules once you ask "who is long the foreign currency?"
- A U.S. exporter that will receive euros in three months is long euros and fears the euro will fall; it sells euro futures.
- A U.S. importer that must pay yen in three months is short yen and fears the yen will rise; it buys yen futures.
Worked example. An importer owes ¥50,000,000 in 90 days. Today the spot rate and the futures price are both $0.006800 per yen (basis zero), so the bill would cost $340,000 at today's rate. The importer buys yen futures at $0.006800. At payment the spot rate is $0.007050 and futures are $0.007070, a basis of −$0.000020.
- Cash cost rose by $0.000250 × 50,000,000 = $12,500, to $352,500.
- Futures gained $0.000270 × 50,000,000 = $13,500.
- Net cost: $352,500 − $13,500 = $339,000 — slightly better than $340,000, because the basis weakened and the importer, a long hedger, is short the basis. Check: $0.006800 + (−$0.000020) = $0.006780 × 50,000,000 = $339,000.
Stock indices
Portfolio insurance is the CFTC's name for using stock index futures or options to protect a stock portfolio against market declines[2]. A manager holding stocks sells stock index futures (a short hedge); a manager expecting cash to invest who fears a rally buys them (an anticipatory long hedge). The number of contracts is set by the hedge ratio: portfolio value divided by the value of one futures contract, adjusted for how closely the portfolio tracks the index[2].
Worked example. A $6,000,000 portfolio moves in line with an index whose futures trade at 4,800 with a $50 multiplier. One contract is worth 4,800 × $50 = $240,000. Contracts to sell: $6,000,000 ÷ $240,000 = 25.
Sources cited in this excerpt
- Study Outline for Futures Industry Exams (Series 3 – National Commodity Futures Examination). National Futures Association, 2026-10-17. https://www.nfa.futures.org/registration-membership/study-outlines/index.html
- CFTC Glossary. U.S. Commodity Futures Trading Commission, 2026-10-17. https://www.cftc.gov/LearnAndProtect/EducationCenter/CFTCGlossary/index.htm
- Understanding Pricing and Interest Rates. U.S. Department of the Treasury, Bureau of the Fiscal Service (TreasuryDirect), 2026-10-17. https://www.treasurydirect.gov/marketable-securities/understanding-pricing/
Câu hỏi người mua thường hỏi
Nhận sách thế nào?
Thanh toán xong, mục tải xuống hiện ngay trên trang này. Liên kết cũng được gửi qua email. Không cần tài khoản.
Nếu sách không hợp thì sao?
Gửi email trong vòng 14 ngày để được hoàn tiền đầy đủ, không cần lý do.
Phần luyện tập miễn phí có bị bỏ không?
Không. Mọi câu hỏi luyện tập, bài thi thử tính giờ và các chương miễn phí trên trang vẫn miễn phí. Cuốn sách là nửa "học", không phải hàng rào quanh phần miễn phí.
Thêm câu hỏi (1)
Đọc trên điện thoại được không?
Được — EPUB cho điện thoại và máy đọc sách, PDF để in và dán tab. Bạn nhận cả hai.
Vì sao mua sách khi phần luyện tập miễn phí?
Câu hỏi luyện tập và bài thi thử tính giờ vẫn miễn phí — không có gì trên trang bị giấu sau cuốn sách này. Cuốn sách $24.99 là nửa "học": chính phần kiến thức, dạy theo trình tự, trong một tệp thuộc về bạn.
- Dạy có hệ thống — mọi phần thi giảng theo từng chương, từ đầu đến cuối, không chỉ là câu hỏi
- In ra & dán nhãn — PDF sẵn sàng để in, tô đậm, ghi chú và mang tới bàn học
- Học mọi nơi, ngoại tuyến — EPUB trên điện thoại hay máy đọc sách; không cần wifi, không cần tab trình duyệt
- Tất cả một chỗ — các chương và câu hỏi luyện tập trong một tệp
- Của bạn trọn đời — trả một lần $24.99, tải ngay, không thuê bao
Chi tiết
- Đối chiếu từ nguồn chính thức(NFA Study Outline for Futures Industry Exams and NFA Rulebook, FINRA Series 3 exam page, CFTC regulations (eCFR) and the Commodity Exchange Act, read October 2026)
- 102 câu hỏi luyện tập miễn phí
Một Series 3 exam prep course có giá $150–$500. Cuốn sách này dạy cùng một kỳ thi — cùng quy định, đối chiếu theo chuẩn hiện hành — chỉ với $24.99 trả một lần, thuộc về bạn trọn đời.
Mua một lần, truy cập tải về trọn đời. eBook là trọn bộ hướng dẫn ôn Series 3 — National Commodity Futures Exam ở dạng PDF và EPUB. Bản tóm tắt mang tính giáo dục, không phải tư vấn chuyên môn hay pháp lý — luôn xác nhận quy định hiện hành với nguồn chính thức. Cập nhật lần cuối: October 2026.