Personal Lines Insurance Producer · 2026 版
Personal Lines Insurance Producer — Complete Study Guide (2026)
The personal subset of P&C — homeowners, dwelling, personal auto, renters/condo, and umbrella — with HO forms, PAP parts, and coinsurance worked examples.
- 全国通用部分 8 章 —— 房屋险、住宅险、个人车险、租客与共管公寓、伞式责任与 NFIP 洪水险 —— PDF + EPUB 永久保存
- 一套 55 题的模拟练习,答案键逐题讲解推理过程,而不只给出选项字母
- 凡由各州自行规定的数字 —— 共 51 处 —— 正文中均标注 [state-set],让你清楚该向本州保险厅核实哪些内容
$19.99一次买断 · 永久下载 · 无订阅
PDF + EPUB · 英文 · 70 页 · $19.99 一次买断
本书为英文版,下载的 PDF 与 EPUB 均为英文。
付款后立即下载 —— 无需注册账号,无订阅。
14 天退款保证:任何原因不满意?购买后 14 天内发邮件至 support@preppass.org 即可全额退款。 这是电子下载,无需寄回任何东西。 退款政策
先做 10 题,看看讲解 —— 免费
先答完这 10 题,交卷后每题都有解析 —— 还会指出本指南里讲这一点的那一节。约 5 分钟,无需注册。
开始 10 道免费题翻开这本书看看
三页真实内页,直接从你将下载的 PDF 渲染而来 —— 依次是一页速查、一页讲解、一道带解析的例题。没有任何一页是为了好看而重画的。
- 速查页Chapter 2 — Insurance Regulation, Licensing & Producer Ethics · PDF 第 19 页
一页可以随时翻回来的内容:把数字、期限或术语集中在一处。
- 怎么讲Practice Exam — 55 Questions · PDF 第 63 页
讲解页:用文字把知识讲清楚,顺序与考试考查的顺序一致。
- 一道题的完整解析Chapter 1 — General Insurance Principles · PDF 第 13 页
一道练习题,连同答案和背后的推理 —— 不只是一个答案键。
两门都要考?有套装价
- Personal Lines Insurance Producer — Complete Study Guide (2026)$19.99
- California Personal Lines Insurance Producer — Cheat Sheet (2026)$9.99
两件一起买:$22.99 —— 比分开买省 $6.99
分开买 $29.98 · 立减 23% · 一次结账,两件都到手。
已经买过《California Personal Lines Insurance Producer》了?那就别买套装——套装里含这本,你会重复付费。单独购买《Personal Lines Insurance Producer》只要 $19.99。 Personal Lines Insurance Producer · 套装内容 →
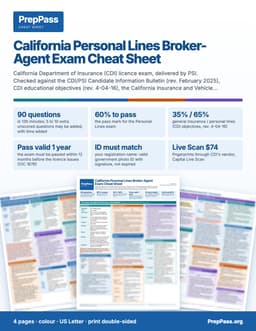
两周内就要考试?
这本指南是系统讲解,要花几周读。如果两周内就考,可打印的彩色速查表是另一款产品:考试涉及的关键数字,按章节排好。
4 页 · US Letter · 可打印 PDF · 永久保存
关于这场考试本身
| 主管机构 | 没有统一的主管机构:各州保险局分别颁发个人险种代理人执照并自行设定考试,通常由考试机构承办。加州由 PSI Services LLC 承办;得州由 Pearson VUE 承办。如 PrepPass 已有你所在州的考试事实页面,请查看该页面。 我们查阅但未找到该数据的来源: PSI / California Department of Insurance — Candidate Information Bulletin for California Insurance License Examinees (revised March 2026) |
|---|---|
| 题目数量 | 由各州自行规定。加州的考试为 90 题。如 PrepPass 已有你所在州的考试事实页面,请查看该页面。 我们查阅但未找到该数据的来源: PSI / California Department of Insurance — Candidate Information Bulletin for California Insurance License Examinees (revised March 2026) |
| 考试时限 | 由各州自行规定。加州给 135 分钟;得州的 Personal Lines Property & Casualty 考试给 120 分钟。如 PrepPass 已有你所在州的考试事实页面,请查看该页面。 我们查阅但未找到该数据的来源: PSI / California Department of Insurance — Candidate Information Bulletin for California Insurance License Examinees (revised March 2026) |
| 及格标准 | 由各州自行规定。加州公布的是 60%;Pearson VUE 的得州手册公布的是 0–100 量表上的标准分 70,并说明该分数不是答对题目的百分比。如 PrepPass 已有你所在州的考试事实页面,请查看该页面。 我们查阅但未找到该数据的来源: CDI — Examination Times and Number of Questions (CDI website table; stale on languages and, for time limits, disagrees with the CIB) |
| 费用 | 由各州自行规定。Pearson VUE 的得州手册列出 Personal Lines Property & Casualty 考试每次 $39。如 PrepPass 已有你所在州的考试事实页面,请查看该页面。 我们查阅但未找到该数据的来源: Pearson VUE — Texas Insurance Licensing Candidate Handbook, October 2024 (#124400) |
| 考试语言 | 由各州自行规定;Pearson VUE 的得州手册列有英语与西班牙语版本。如 PrepPass 已有你所在州的考试事实页面,请查看该页面。 我们查阅但未找到该数据的来源: Pearson VUE — Texas Insurance Licensing Candidate Handbook, October 2024 (#124400) |
包含什么,不包含什么
包含
- Homeowners: HO-2/3/4/5/6/8, Coverage A–F, and special limits
- Dwelling (DP-1/2/3) and the 'no liability in the base DP' trap
- Personal auto (PAP) Parts A–F, UM/UIM, and newly-acquired-auto rules
- Property fundamentals: coinsurance, ACV vs RC, NFIP flood
- 55 original practice questions with answer explanations
- PDF (print & tab it) + EPUB (phone / e-reader)
不包含
- 不寄送纸质书 —— 这是一份你下载后可自行打印的文件
- 购书不含视频课程、讲师或一对一辅导 —— 站上的免费视频是另一回事
- 不含考试报名费与考点费用,这些仍需向官方机构缴纳
目录
查看 12 个部分及各部分起始页
- Chapter 1 — General Insurance Principles第 7 页
- Chapter 2 — Insurance Regulation, Licensing & Producer Ethics第 14 页
- Chapter 3 — Property Insurance Fundamentals第 20 页
- Chapter 4 — The Dwelling Policy (DP)第 27 页
- Chapter 5 — Homeowners Insurance (HO Forms)第 33 页
- Section I — The Property Coverages第 34 页
- Section II — Liability and Medical Payments第 35 页
- Section I Exclusions (Homeowners)第 36 页
- Chapter 6 — Personal Auto Insurance (PAP)第 39 页
- Chapter 7 — State Overlays, Residual Markets & Catastrophe Perils第 46 页
- Chapter 8 — Endorsements, Personal Liability & Umbrella第 52 页
- Practice Exam — 55 Questions第 58 页
取自你将下载的那份 PDF,并标明各章起始页 —— 不是在此手工录入的。
免费读完整一章
完整的一章,与电子书正文一字不差。直接在此窗口滚动阅读;无需下载,无需邮箱。
在本页直接阅读第 1 章
Before you ever quote a homeowners or personal auto policy, you need a vocabulary. This chapter covers the bedrock ideas every personal lines producer must master: which risks are insurable, how hazards differ from perils, the legal nature of an insurance contract, the duty of utmost good faith, and the doctrines — insurable interest, indemnity, subrogation, contribution — that keep insurance from turning into a wager. These concepts are truly national: they come from insurance law and industry practice, not from any one state's code, so nothing in this chapter is state-set. Expect roughly seven percent of the exam here, and expect it to test definitions and applications, not memorized statute language.
Risk, and What Makes a Risk Insurable
Risk is simply uncertainty about a future outcome. Insurance addresses only pure risk — a situation that can end in a loss or in no loss, but never in a gain. A house burning, a car being rear-ended, jewelry being stolen: each is a pure risk. Speculative risk carries three possibilities — loss, no change, or gain — like buying a stock or betting on a game. Speculative risk is not insurable, because insuring a chance to profit would create a wagering contract, which the law will not enforce.
To be insurable, a pure risk should also meet several practical conditions. A common memory aid is that an insurable loss should be definite (measurable in time, place, and amount), accidental (fortuitous, outside the insured's control — not intentional), part of a large group of similar exposure units (so the insurer can predict aggregate losses by the law of large numbers), not catastrophic to the insurer (one event should not bankrupt the pool the way an uninsured war or a single mega-hurricane could), calculable (frequency and severity can be estimated well enough to price), and economically feasible (the premium is small relative to the potential loss). This is why insurers reinsure or exclude flood, quake, and war — those perils threaten too many insureds at once.
Peril vs. Hazard
A peril is the actual cause of a loss — fire, theft, windstorm, a falling tree. A hazard is a condition that increases the chance a peril will occur or makes a resulting loss worse. The exam tests three kinds of hazard, and confusing them is a classic wrong answer.
- A physical hazard is a tangible condition: worn knob-and-tube wiring, an unfenced pool, a roof at the end of its life.
- A moral hazard is a dishonest tendency in the insured — a history of suspicious claims, or a desire to over-insure in order to profit from a loss. Moral hazards involve intent to cause or exaggerate loss.
- A morale hazard (sometimes "attitudinal hazard") is carelessness or indifference that arises because the person has insurance — leaving the front door unlocked because "the policy will pay." No dishonesty, just apathy.
Underwriters price physical hazards, decline or surcharge moral hazards, and try to educate against morale hazards.
The Insurance Contract and Its Special Nature
An insurance policy is a contract, so it needs the four elements of any contract: agreement (offer and acceptance), consideration (the premium in exchange for the insurer's promise to pay), legal capacity of both parties, and a legal purpose. Beyond those basics, insurance contracts carry four special characteristics that appear on nearly every exam:
- Aleatory — the dollars exchanged are unequal and depend on chance. An insured might pay one premium and collect a $400,000 loss, or pay for thirty years and never file a claim.
- Conditional — the insurer pays only if conditions are met: premium paid, prompt notice of loss, cooperation, proof of loss.
- Unilateral — only one party (the insurer) makes a legally enforceable promise. The insured can simply stop paying without being sued for breach; the insurer, once premium is paid, is bound.
- Adhesion — the insurer drafts the contract and offers it on a take-it-or-leave-it basis. Because the insured cannot negotiate the wording, courts construe any genuine ambiguity against the insurer (the drafter). This rule of construction is heavily tested.
A related idea: insurance contracts are contracts of utmost good faith (see below), and they rely on representations and warranties. A representation is a statement believed true when made; a warranty is a promise guaranteed to be true. In modern personal lines, most applicant statements are treated as representations.
The Anatomy of a Policy — and the Binder
Every personal-lines policy is assembled from the same four building blocks, remembered by the acronym DICE:
- Declarations — the who/what/where/how much page: named insured, address, policy period, limits, deductibles, premium.
- Insuring agreement — the insurer's core promise: what perils or claims it will pay for.
- Conditions — the rules both parties must follow for the promise to operate: duties after loss, appraisal, subrogation, cancellation.
- Exclusions — what the policy will not pay for, no matter how the loss occurred.
Endorsements are attached forms that modify the base contract — adding, removing, or reshaping coverage — and an endorsement controls over the base form wherever they conflict.
Before the policy itself is issued, an agent with binding authority may issue a binder: temporary evidence that coverage is in force, effective immediately, oral or written. A binder is not the policy and does not guarantee one will be issued; it simply holds coverage in place until the insurer issues the policy or declines the risk, at which point the binder ends. Exam questions like to test that a binder is temporary and that it is real coverage while it lasts.
Utmost Good Faith, Representations, and Concealment
An insurance contract is one of utmost good faith (Latin: uberrimae fidei). Both sides must deal honestly, and the applicant in particular must disclose information the insurer cannot easily verify. Three terms recur:
- A representation is a statement of fact made by the applicant before the policy takes effect. A misrepresentation is a false one. If it is material, the insurer may rescind (void) the policy.
- Concealment is silence — the failure to disclose a fact the applicant knows and ought to communicate. A material concealment also gives the insurer grounds to rescind.
- Materiality is the test that governs both: a fact is material if it would influence a prudent insurer's decision to accept the risk or set the premium. For property-casualty policies, materiality generally does not require proof of intent — even an innocent material misstatement can support rescission (whereas fraud requires intent).
Two doctrines cut the other way — they stop the insurer from going back on its own conduct. Waiver is the intentional relinquishment of a known right: an insurer that issues a policy knowing of a breach may be held to have waived the right to rely on it. Estoppel bars the insurer from asserting a defense after its words or conduct led the insured to reasonably rely to their detriment — an adjuster who tells the insured "you're covered, go ahead and repair" may estop the company from later denying on a technicality. Good faith runs in both directions.
(The specific statutory citations and the exact standard for rescission are [state-set]; the concepts are national.)
Insurable Interest — When It Must Exist
Insurable interest is the legal or financial stake an insured must have in the covered property or life. Without it, the contract is a wager and unenforceable. The rule that matters most in property insurance:
In property insurance, insurable interest must exist at the time of loss (it need not exist when the policy is bought). In life insurance, insurable interest must exist at policy inception (it need not exist at the time of the insured's death).
Sources of insurable interest in personal lines include direct ownership of a home or car, a mortgagee's lien on a dwelling, a lessee's interest in property, and a bailee's interest in property held for another. Classic trap: a homeowner sells the house, and the buyer's payment clears before a fire; the seller has no insurable interest at the moment of loss and cannot collect — even though premium was paid through the policy period.
Indemnity, Subrogation, and Contribution
Indemnity is the principle that insurance should restore the insured to the same financial position as before the loss — no better, no worse. It is what keeps property insurance from becoming a profit center. Most personal lines property policies are contracts of indemnity, paying actual cash value or replacement cost up to the limit and never more than the actual loss. (Valued policies and some replacement-cost settlements are limited exceptions.)
Subrogation is indemnity's enforcement arm. Once the insurer pays the insured for a covered loss, it steps into the insured's shoes and may pursue any responsible third party to recover what it paid. If a neighbor's contractor negligently starts a fire that damages the insured's home, the insurer pays the homeowner, then sues the contractor. Two rules follow: the insured may not collect twice (once from the insurer, once from the wrongdoer) because that would violate indemnity, and the insured may not sign away the insurer's subrogation rights after a loss.
Contribution (and the Other Insurance clause) governs when more than one policy covers the same loss. The most common personal-lines method is pro rata: each insurer pays the share of the loss that its limit bears to the total of all applicable limits. If two policies cover the same dwelling for $400,000 and $200,000 and the loss is $300,000, the first pays two-thirds ($200,000) and the second one-third ($100,000). Contribution prevents the insured from profiting by stacking overlapping policies.
How Insurers Are Classified
Insurers are grouped by ownership and by regulatory status:
- A stock insurer is owned by shareholders; profits go to shareholders as dividends, and policyholders are simply customers.
- A mutual insurer is owned by its policyholders; surplus may be returned to insureds as policyholder dividends, which are not guaranteed.
- A reciprocal exchange is an unincorporated group whose subscribers insure each other through an attorney-in-fact.
- An admitted (authorized) insurer holds a certificate of authority from the state, is regulated for rates and forms, and participates in the state guaranty association that pays covered claims if the insurer becomes insolvent.
- A non-admitted (surplus lines) insurer is not licensed in the state; its policies are placed through a surplus lines broker only for risks the admitted market will not write, and its insureds generally get no guaranty-association protection.
(Guaranty-association names, coverage caps, and surplus-lines rules are [state-set]; the categories are national.)
Key Numbers & Facts — Chapter 1 - Insurance covers pure risk only (loss or no loss), never speculative risk (loss/no change/gain). - Peril = cause of loss; hazard = something that raises the chance/severity. Physical / moral (dishonesty) / morale (carelessness). - Four special contract traits: aleatory, conditional, unilateral, adhesion. Ambiguity is read against the insurer. - Policy anatomy = DICE: Declarations, Insuring agreement, Conditions, Exclusions (+ endorsements modify). A binder = temporary, immediate evidence of coverage until the policy issues or is declined. - Utmost good faith; a material misrepresentation or concealment can let the insurer rescind. Property-casualty materiality generally needs no proof of intent. - Waiver = insurer intentionally gives up a known right; estoppel = insurer barred from a defense after the insured relied on its conduct. - Insurable interest: property = at time of loss; life = at inception. - Indemnity = made whole, no more. Subrogation = insurer pursues the at-fault third party. Contribution/pro rata = insurers share by limits. - Stock (shareholders) vs. mutual (policyholders); admitted (guaranty-fund protected) vs. non-admitted/surplus (not).
Worked Example. A homeowner tells her agent she has "never had a claim," when in fact she had two water-damage claims two years ago that she genuinely forgot. A pipe bursts; the insurer's investigation surfaces the prior claims. Can the insurer rescind? Likely yes: prior claims are material (they influence acceptance and pricing), and for a property policy the misrepresentation need not be intentional to be grounds for rescission. Her honest forgetfulness does not save the policy. The lesson for a producer: help clients answer application questions completely, because an innocent material error can void coverage after a loss.
Exam Traps.
- Moral vs. morale. Moral = dishonesty (padding a claim). Morale = carelessness born of having insurance (leaving keys in the car). Test-writers swap these constantly.
- Peril vs. hazard. Fire is a peril; the frayed wiring that started it is a hazard.
- Insurable-interest timing. Property = time of loss; life = inception. A choice that says "property insurance requires insurable interest when the policy is issued" is wrong.
- Unilateral. Only the insurer makes an enforceable promise. Do not pick "bilateral."
- Ambiguity is construed against the drafter (insurer) — a consequence of adhesion, not of good faith.
- A binder is coverage, but temporary. "No coverage exists until the policy is delivered" is wrong when a binder was issued; "a binder guarantees the policy will be issued" is wrong too.
购买前
- 怎么拿到?
- 付款后下载入口立即出现在本页,链接同时发到你的邮箱。无需注册账号。
- 不合适怎么办?
- 14 天内发邮件即可全额退款,无需理由。
- 免费练习会取消吗?
- 不会。站上的每一道练习题、计时模考和免费章节都继续免费。这本书是「学」的那一半,不是把免费部分围起来的门。
- 能在手机上看吗?
- 可以 —— EPUB 适合手机和电子书阅读器,PDF 适合打印和贴标签,两种都给你。
详细信息
The personal subset of P&C — homeowners, dwelling, personal auto, renters/condo, and umbrella — with HO forms, PAP parts, and coinsurance worked examples.
- Format: PDF + EPUB download · 70 pages
- 55 practice questions in the book, with a full answer key
- 324 free practice questions for this exam on PrepPass, included at no cost
- $19.99 one-time — no subscription
- 14-day money-back guarantee · refund policy
- Cross-referenced against: ISO personal-lines forms / NFIP / NAIC model acts
- Last updated: September 2026
- 官方来源核验(ISO personal-lines forms / NFIP / NAIC model acts)
- 324 道免费练习题
- 即时下载,永久拥有
insurance pre-license course 要 $100–$500。这本书讲的是同一门考试 —— 同样的规则、核对到最新标准 —— 只需一次性 $19.99,永久归你。
练习免费,为什么还要买书?
我们的练习题和计时模考一直免费 —— 网站上的东西不会因为这本书而收起来。这本 $19.99 的书是「学」的那一半:知识本身,按顺序讲清楚,存成一份属于你的文件。
- 系统讲解 —— 每个考试部分按章节从头讲到尾,不只是题目
- 可打印可贴标签 —— 一份适合打印的 PDF,能划重点、做批注、带到书桌前
- 随处离线学 —— EPUB 放手机或电子书阅读器;不用 wifi,不用一堆浏览器标签
- 全在一处 —— 章节和练习题都在同一份文件里
- 永久归你 —— 一次 $19.99,即时下载,无订阅
而且零风险:14 天退款保证 —— 不满意?发邮件即可全额退款,无需理由。 详见退款政策。
14 天退款保证 · 全额退款,无需理由。
一次购买,永久下载访问。此电子书是完整的 Personal Lines Insurance Producer 学习指南,含 PDF 与 EPUB。仅为教育性摘要,非专业或法律意见 —— 请始终以官方来源核实当前规定。最后更新:September 2026。