Guía de estudio · Edición 2026
Florida Real Estate Sales Associate Exam — Complete Study Guide (2026)
The FL sales associate exam, taught from Florida Statutes Chapter 475 and FREC rules.
- Extensión
- 87 páginas
- Preguntas de práctica en el libro
- 30
- Simulacro en línea de PrepPass
- 100 preguntas · 210 min
- Datos del examen verificados
- septiembre de 2026
- Entrega
- PDF + EPUB · en inglés · descarga inmediata
Léelo antes de comprar: This is an independent study aid, not affiliated with or endorsed by the Florida DBPR, FREC, or the exam vendor.
Leer el resto de este aviso
It is authored from Florida Statutes Chapter 475, FREC rules, and standard real-estate principles. FL real-estate rules and figures (license/CE requirements, fees, documentary-stamp & intangible taxes) change — this guide teaches the rules and flags changeable figures to 'verify current with FREC/DBPR'; it is general educational information, not legal advice.
Sobre este libro
The FL sales associate exam, taught from Florida Statutes Chapter 475 and FREC rules — licensing & agency (the transaction-broker default), escrow, contracts, finance, valuation, and the real-estate math you'll be tested on.
Datos del examen, a quién le sirve y qué cambió
Sobre el examen en sí
| Organismo administrador | Florida Department of Business and Professional Regulation (DBPR), for the Florida Real Estate Commission — examen administrado por Pearson VUE |
|---|---|
| Preguntas | 100 preguntas |
| Tiempo límite | 210 minutos |
| Puntuación para aprobar | 75 de 100 correctas |
| Tarifas |
|
| Idiomas disponibles | Inglés · Español |
Mira dentro del libro
Tres páginas reales, renderizadas directamente del PDF que descargas — una página de referencia, una de explicación y una pregunta resuelta, siempre en ese orden. Nada se rediseñó para verse mejor.
- Referencia rápidaCHAPTER 2 — Florida License Law and Brokerage Relationships · Página 33 del PDF
Una página a la que puedes volver: cifras, plazos o términos reunidos en un solo lugar.
- Cómo se enseñaCHAPTER 5 — Property Valuation and Appraisal · Página 64 del PDF
Una página de explicación: el material enseñado en prosa, en el orden en que lo evalúa el examen.
- Una pregunta resueltaCHAPTER 1 — Real Estate Principles and Property Ownership · Página 19 del PDF
Una pregunta de práctica con su respuesta y el razonamiento detrás — no solo la clave.
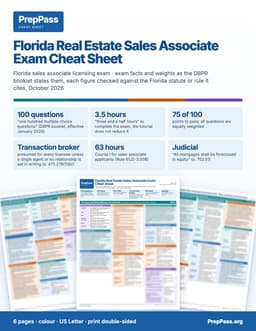
¿Examen en menos de dos semanas?
Esta guía es la enseñanza, para leer durante semanas. Si tu examen es en menos de dos semanas, la hoja de referencia a color imprimible es el otro producto: las cifras clave, por secciones.
6 páginas · US Letter · PDF imprimible · tuyo para siempre
Qué incluye — y qué no
Incluido
- All exam areas at real weight, with FL specifics (Ch. 475, FREC)
- The transaction-broker default (§475.278) + escrow timelines
No incluido
- No se envía copia impresa — es un archivo que descargas y puedes imprimir tú
- El libro no incluye curso en vídeo, instructor ni tutorías — los vídeos gratis del sitio van aparte
Todo lo incluido y todo lo que no
Incluido
- Homestead (all three senses) + Save Our Homes; construction liens (Ch. 713)
- Worked FL math (doc-stamp on deed+note, intangible tax, prorations, millage)
- In-book practice questions with explanations (400+ more free on the site)
- A key-figures reference (changeable figures flagged verify-current) — PDF + EPUB
No incluido
- No incluye tu inscripción al examen ni la tasa del centro, que sigues pagando al organismo oficial
Contenido
Ver 6 secciones y la página en la que empieza cada una
- CHAPTER 1 — Real Estate Principles and Property Ownershipp. 9
- CHAPTER 2 — Florida License Law and Brokerage Relationshipsp. 21
- CHAPTER 3 — Real Estate Contracts and Listing Agreementsp. 35
- CHAPTER 4 — Real Estate Finance and Mortgagesp. 46
- CHAPTER 5 — Property Valuation and Appraisalp. 57
- CHAPTER 6 — Real Estate Mathematicsp. 67
Tomado del PDF que descargas, con la página en la que empieza cada uno — no escrito a mano aquí.
Lee un capítulo completo gratis
Un capítulo completo, tal como viene en el eBook. Desplázate en la ventana para leerlo aquí; sin descargas ni correo.
Lee el capítulo 6 aquí, sin salir de la página
Real-estate math is the part most candidates fear — so that's the chapter you can read free: the exam's math patterns, worked step by step. If the teaching works here, it works everywhere.
About 13% of the exam. Math appears throughout the test and in daily practice. This chapter drills the calculations you must own: commissions and splits, seller's net, financing math (down payment, LTV, interest, points), area and land measurement, prorations (365-day and 360-day), and property taxes and percentages. Work every example on paper — the exam rewards doing, not reading.
The rule: convert, then apply the base formula
Almost every problem reduces to part = whole × rate, with the rate in decimal form (move the decimal two places left: 6% → 0.06). Rearranged: whole = part ÷ rate and rate = part ÷ whole. The single most valuable habit is to plug your answer back into the relationship to check it.
Worked example — commission and splits
A home sells for $325,000 at a 6% total commission. The listing and selling brokerages split it 50/50, and the listing agent keeps 60% of the brokerage's share.
- Total commission = 325,000 × 0.06 = $19,500.
- Each brokerage's side = 19,500 × 0.50 = $9,750.
- Listing agent = 9,750 × 0.60 = $5,850; brokerage keeps 9,750 − 5,850 = $3,900.
Work whole → part: total first, then split the sides, then split each side between brokerage and agent.
Worked example — seller's net (working backward)
A seller wants to net $188,000 after a 6% commission and no other costs.
- Price = net ÷ (1 − rate) = 188,000 ÷ (1 − 0.06) = 188,000 ÷ 0.94 = $200,000.
- Check: 200,000 × 0.06 = $12,000 commission; 200,000 − 12,000 = $188,000. ✓
Do not multiply the net by the rate and add it back — that understates the price.
Worked example — down payment, LTV, and points
A buyer purchases a $250,000 home (appraised at value) at 80% LTV with 2 points.
- Loan = 250,000 × 0.80 = $200,000.
- Down payment = 250,000 − 200,000 = $50,000.
- Points = 200,000 × 0.02 = $4,000 (on the loan).
To find LTV from a loan and value: LTV = loan ÷ value. A $180,000 loan on a $240,000 property = 180,000 ÷ 240,000 = 0.75 = 75%.
Worked example — simple interest, annual and monthly
A $200,000 loan at 5% interest, interest-only.
- Annual interest = 200,000 × 0.05 = $10,000.
- Monthly interest = 10,000 ÷ 12 = $833.33.
Interest = principal × rate × time. For part of a year, multiply by the fraction of the year (for example, 90 days ÷ 360, or ÷ 365 if the problem so specifies).
Worked example — area, acres, and the survey system
- A lot 80 ft × 120 ft = 80 × 120 = 9,600 sq ft.
- One acre = 43,560 sq ft. A 21,780 sq ft parcel = 21,780 ÷ 43,560 = 0.5 acre. A 3-acre tract = 3 × 43,560 = 130,680 sq ft.
- Cost estimate: a 2,000 sq ft house at $120/sq ft = 2,000 × 120 = $240,000.
- Government survey: a section = 1 square mile = 640 acres; a quarter-section = 640 ÷ 4 = 160 acres; a quarter of a quarter = 160 ÷ 4 = 40 acres.
- Triangle (corner lot): area = ½ × base × height.
Keep units consistent before multiplying (convert yards/inches to feet first) and label the result.
Worked example — proration on a 365-day year (taxes in arrears)
Annual taxes are $3,650, and the seller owned the property 120 days of the year through the day before closing. Florida taxes are paid in arrears, so the seller credits the buyer.
- Daily rate = 3,650 ÷ 365 = $10.00/day.
- Seller's share = 10.00 × 120 = $1,200, credited to the buyer at closing.
On a 360-day (banker's) year, the daily rate would be 3,650 ÷ 360 = $10.14/day — which is why the problem must state the method. Confirm who is charged for the closing date (contract or custom).
Worked example — property tax by millage
A property has a taxable value of $200,000 and a millage rate of 20 mills (recall 1 mill = $1 per $1,000).
- Tax = (200,000 ÷ 1,000) × 20 = 200 × 20 = $4,000 (equivalently, 200,000 × 0.020 = $4,000).
In Florida, taxable value = assessed value minus exemptions (like homestead); use the figure the problem provides, and remember exemption amounts and caps change — verify current with the county property appraiser.
Worked example — percentage change
A property rose from $250,000 to $280,000.
- Change = 280,000 − 250,000 = $30,000.
- Percent change = change ÷ original = 30,000 ÷ 250,000 = 0.12 = 12% increase.
To recover the original after a known increase: original = new ÷ (1 + rate) = 280,000 ÷ 1.12 = $250,000. Always divide the change by the original, never the new, amount.
The rule: the T-method for any part-whole problem
Many candidates organize percentage problems with a T (or circle): the total on top, the part and the rate on the bottom. Cover the unknown and the T shows the operation: part = total × rate; total = part ÷ rate; rate = part ÷ total. It works for commissions (price, rate, commission), interest (principal, rate, interest), and taxes (value, rate, tax). Label which number is the whole, which is the part, and which is the rate, then read the operation off the T. This single tool converts a large share of the math section into mechanical steps.
Worked example — profit and loss
An investor buys a property for $200,000, spends $30,000 on improvements, and sells for $276,000. What is the percent profit on total cost?
- Total cost = 200,000 + 30,000 = $230,000.
- Profit = 276,000 − 230,000 = $46,000.
- Percent profit = profit ÷ cost = 46,000 ÷ 230,000 = 0.20 = 20%.
Always divide profit by cost (the original investment), not by the sale price.
Worked example — appreciation
A home worth $250,000 appreciates 4% per year. Its value after two years:
- Compounded: Year 1 = 250,000 × 1.04 = $260,000; Year 2 = 260,000 × 1.04 = $270,400.
- Simple (add 4% of the original twice): 250,000 + 2 × (250,000 × 0.04) = 250,000 + 20,000 = $270,000.
Read whether the problem compounds or not — the answers differ.
Worked example — combined Florida transfer taxes
A property sells for $360,000 with a new $288,000 mortgage. Using common rates (deed $0.70/$100, note $0.35/$100, intangible 2 mills — verify current):
- Deed doc stamps: 360,000 ÷ 100 = 3,600 × $0.70 = $2,520.
- Note doc stamps: 288,000 ÷ 100 = 2,880 × $0.35 = $1,008.
- Intangible tax: 288,000 × 0.002 = $576.
- Total = 2,520 + 1,008 + 576 = $4,104.
Keep the bases straight: the deed tax is on the price; the note and intangible taxes are on the loan.
Worked example — prorating rent at closing
A rented property closes on the 20th of a 30-day month; the tenant paid $1,500 for the full month to the seller. The buyer owns from the 20th through the 30th (11 days, if the buyer is charged the closing date).
- Daily rent = 1,500 ÷ 30 = $50.00.
- Buyer's share = 50.00 × 11 = $550, credited to the buyer at closing (the seller collected rent for days the buyer will own).
Confirm the day count and whether the buyer or seller is charged for the closing date; prepaid rent means the seller credits the buyer for the unused days.
Worked example — mortgage payoff with accrued interest
A seller pays off a $120,000 loan balance at closing; interest is 6% and 15 days have accrued since the last payment (30-day-month convention).
- Monthly interest = 120,000 × 0.06 ÷ 12 = $600.
- 15 days = half a month = $300 accrued interest.
- Payoff = principal + accrued interest = 120,000 + 300 = $120,300 (plus any fees).
The payoff exceeds the balance because interest accrues to the payoff date.
Worked example — area of an irregular (L-shaped) lot
A lot is an L shape: a 100 ft × 60 ft rectangle with a 40 ft × 30 ft corner removed.
- Full rectangle = 100 × 60 = 6,000 sq ft.
- Removed corner = 40 × 30 = 1,200 sq ft.
- Area = 6,000 − 1,200 = 4,800 sq ft. In acres: 4,800 ÷ 43,560 = 0.11 acre.
Alternatively, split the L into two rectangles and add them — same result.
Worked example — graduated commission split
An agent is on a 70/30 split up to $50,000 of company-earned commission this year, then 100% after the cap. This deal earns the brokerage $9,000 gross, and the agent has already generated $46,000 toward the cap.
- The agent's 70% applies to the first $4,000 (reaching the $50,000 cap): 4,000 × 0.70 = $2,800.
- The remaining $5,000 is past the cap at 100%: 5,000 × 1.00 = $5,000.
- Agent total from this deal = 2,800 + 5,000 = $7,800.
Split-cap problems apply each rate to the portion in its tier — work in pieces, like a tax bracket.
Worked example — seller net with costs and a loan payoff
A seller wants to net $100,000 cash. They owe $180,000 on their mortgage and will pay a 6% commission and $4,000 in other closing costs. What sale price is needed?
- Required proceeds before commission = net $100,000 + payoff $180,000 + costs $4,000 = $284,000.
- Commission is 6% of price, so price × (1 − 0.06) = 284,000 → price × 0.94 = 284,000.
- Price = 284,000 ÷ 0.94 = $302,127.66, about $302,128.
Build the required proceeds first, then divide by (1 − commission rate). Check: commission ≈ $18,128; price − commission = $284,000; minus loan and costs leaves ≈ $100,000. ✓
Worked example — solving for the interest rate
A borrower pays $9,600 in interest in the first year on a $160,000 interest-only loan. What is the rate?
- Rate = interest ÷ principal = 9,600 ÷ 160,000 = 0.06 = 6%.
Rearranging interest = principal × rate × time lets you solve for any one unknown when you know the other three.
Worked example — square footage and price per square foot
A house has a main floor of 40 ft × 30 ft and a second floor of 40 ft × 20 ft. It is listed at $396,000.
- Main floor = 40 × 30 = 1,200 sq ft.
- Second floor = 40 × 20 = 800 sq ft.
- Total living area = 1,200 + 800 = 2,000 sq ft.
- Price per square foot = 396,000 ÷ 2,000 = $198/sq ft.
To compare with a comparable listed at $210/sq ft, multiply that rate by this home's area: 210 × 2,000 = $420,000 — showing the subject is priced below the comparable per foot. Add multi-level areas before dividing.
Worked example — the seller's net after commission and payoff (quick form)
A property sells for $400,000. The seller pays a 6% commission, owes $220,000 on the mortgage, and pays $3,000 in other costs. What does the seller net?
- Commission = 400,000 × 0.06 = $24,000.
- Seller's proceeds = price − commission − payoff − costs = 400,000 − 24,000 − 220,000 − 3,000 = $153,000.
Work top-down: start with the price, subtract each cost and the loan payoff. (Compare this to the reverse "net-to-price" problem, where you divide the required proceeds by (1 − rate).)
Worked example — capitalization to find value, income, or rate
The income approach's core relationship — Value = Net Operating Income ÷ Capitalization Rate — rearranges three ways:
- Value: NOI $90,000 at an 8% cap rate → 90,000 ÷ 0.08 = $1,125,000.
- NOI: a $1,000,000 property at a 7% cap rate → 1,000,000 × 0.07 = $70,000 of NOI.
- Cap rate: $84,000 NOI on an $1,200,000 property → 84,000 ÷ 1,200,000 = 0.07 = 7%.
Cover the unknown in the IRV triangle (Income on top, Rate and Value on the bottom) and read the operation: I = R × V, V = I ÷ R, R = I ÷ V.
Preguntas frecuentes
¿Cómo lo recibo?
Paga y la descarga aparece en esta página al instante. Los enlaces también se te envían por correo. No hace falta cuenta.
¿Y si no es para mí?
Escríbenos dentro de 14 días para un reembolso total, sin preguntas.
¿Va a desaparecer la práctica gratis?
No. Todas las preguntas, el simulacro cronometrado y los capítulos gratis del sitio siguen gratis. Este libro es la mitad de estudio, no una valla alrededor de lo gratuito.
Más preguntas (1)
¿Puedo leerlo en el móvil?
Sí — el EPUB es para móviles y e-readers, el PDF para imprimir y marcar. Recibes ambos.
¿Por qué comprar el libro si la práctica es gratis?
Nuestras preguntas de práctica y el simulacro cronometrado siguen gratis: nada del sitio se esconde tras este libro. El libro de $14.99 es la mitad de estudio: el material en sí, explicado en orden, en un archivo tuyo.
- Enseñanza sistemática — cada sección del examen explicada capítulo a capítulo, de principio a fin, no solo preguntas
- Imprímelo y márcalo — un PDF listo para papel que puedes resaltar, anotar y llevar a tu mesa de estudio
- Estudia en cualquier lugar, sin conexión — EPUB en tu teléfono o e-reader; sin wifi, sin pestañas
- Todo en un solo lugar — los capítulos y las preguntas de práctica en un archivo
- Tuyo de por vida — pago único de $14.99, descarga instantánea, sin suscripción
Los detalles
- Verificado con la fuente oficial(Florida Statutes Chapter 475 + FREC rules)
- 416 preguntas de práctica gratis
Un FL 63-hour pre-license course cuesta $100–$400. Este libro enseña el mismo examen — las mismas reglas, verificadas a los estándares actuales — por un pago único de $14.99 que conservas de por vida.
Compra única, acceso de por vida a la descarga. El eBook es la guía completa de Florida Real Estate Sales Associate Exam en PDF y EPUB. Resumen educativo, no asesoría profesional ni legal — confirma siempre las reglas vigentes con la fuente oficial.