学习指南 · 2026 版
IRS Enrolled Agent (SEE) Study Guide — 2026–2027 Testing Window
Tax Year 2025 law, including the One Big Beautiful Bill Act.
版本: For the SEE window July 1, 2026 – February 28, 2027: tax year 2025 law, including the One Big Beautiful Bill Act.
- 篇幅
- 618 页
- 书内练习题
- 585
- 考试事实核对与文件更新
- 2026年10月
- 交付
- PDF + EPUB · 英文 · 即时下载
购买前请阅读: This is an independent study aid, not affiliated with or endorsed by the IRS or PSI Services.
阅读本声明的其余部分
It is written from the public Internal Revenue Code, IRS publications and forms, and Circular 230, and states the 2025 figures that the July 1, 2026 – February 28, 2027 SEE window tests; later years' figures differ. It is general educational information, not tax or legal advice.
关于本书
Tax Year 2025 law, including the One Big Beautiful Bill Act — Parts 1, 2 and 3 of the SEE, with three 100-question practice exams and every 2025 figure dated and sourced.
考试费(每部分):每次 $317,缴给 PSI Services LLC。补考要再交一次。本指南:$22.99,一次买断。
考试事实、适合谁与变化
关于这场考试本身
| 主管机构 | Internal Revenue Service (IRS) —— 考试由 PSI Services LLC 承办 来源: IRS — Become an enrolled agent (Testing Vendor Transition notice) |
|---|---|
| 题目数量 | 100 道题 (85 道计分,15 道不计分预试题) |
| 考试时限 | 210 分钟 |
| 及格标准 | 标准分 500(量表范围 200–800) |
| 费用 |
|
| 考试语言 | Internal Revenue Service (IRS) 未公布 我们查阅但未找到该数据的来源: IRS — Enrolled agents: Frequently asked questions (SEE content/scoring and Test results answers, reviewed/updated March–August 2026) |
翻开这本书看看
三页真实内页,直接从你将下载的 PDF 渲染而来 —— 依次是一页速查、一页讲解、一道带解析的例题。没有任何一页是为了好看而重画的。
- 速查页Chapter 25 — Preparer Rules, Penalties and Written Advice · PDF 第 434 页
一页可以随时翻回来的内容:把数字、期限或术语集中在一处。
- 怎么讲Chapter 31 — The Filing Process: E-File, Accuracy, Records, Data Security · PDF 第 502 页
讲解页:用文字把知识讲清楚,顺序与考试考查的顺序一致。
- 一道题的完整解析Chapter 31 — The Filing Process: E-File, Accuracy, Records, Data Security · PDF 第 505 页
一道练习题,连同答案和背后的推理 —— 不只是一个答案键。
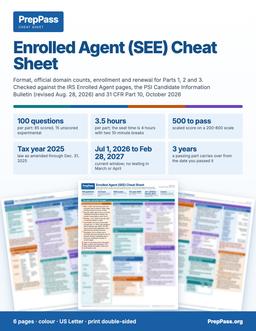
两周内就要考试?
这本指南是系统讲解,要花几周读。如果两周内就考,可打印的彩色速查表是另一款产品:考试涉及的关键数字,按章节排好。
6 页 · US Letter · 可打印 PDF · 永久保存
How this book compares
The IRS publishes free sample questions for all three parts of the Special Enrollment Examination. This book teaches all three parts with full practice exams; Gleim sells online EA review courses.
| Resource | Price | What you get | Choose it if |
|---|---|---|---|
| This bookIRS Enrolled Agent (SEE) Study Guide — 2026–2027 Testing WindowPrepPass | $22.99 | Downloadable study guide covering all three SEE parts
| Choose this book if you want all three parts in one self-study guide with full practice exams, at a book price rather than a course price. |
| From the exam bodySample Special Enrollment Examination questions and answers (opens the publisher's page in a new tab)Internal Revenue Service | Free (PDF and HTML) | Sample questions written to show the style of the exam
| Use them in any case to see the question style; they are samples, not a course. |
| AlternativeGleim EA Review (opens the publisher's page in a new tab)Gleim Exam Prep | Traditional EA Review $699.00; Premium EA Review $799.00; EA Test Bank $499.00 | Online review courses with an adaptive test bank | Choose Gleim if you want a structured online course with an adaptive test bank rather than a book. |
This book
IRS Enrolled Agent (SEE) Study Guide — 2026–2027 Testing Window
PrepPass
- Price
- $22.99
- What you get
Downloadable study guide covering all three SEE parts
- 585 practice questions with explanations
- 618 pages, PDF + EPUB
- Choose it if
- Choose this book if you want all three parts in one self-study guide with full practice exams, at a book price rather than a course price.
From the exam body
Internal Revenue Service
- Price
- Free (PDF and HTML)
- What you get
Sample questions written to show the style of the exam
- Sample sets for Part 1 (Individuals), Part 2 (Businesses) and Part 3 (Representation, Practices, and Procedures)
- Written on tax law through December 31, 2025; never used on a real exam
- Choose it if
- Use them in any case to see the question style; they are samples, not a course.
Alternative
Gleim EA Review (opens the publisher's page in a new tab)
Gleim Exam Prep
- Price
- Traditional EA Review $699.00; Premium EA Review $799.00; EA Test Bank $499.00
- What you get
Online review courses with an adaptive test bank
- Choose it if
- Choose Gleim if you want a structured online course with an adaptive test bank rather than a book.
Other resources' prices and contents are as listed on each publisher's or seller's own page, checked September 24, 2026. Prices change; confirm on the linked page before you buy. This book's price and contents come from our own catalog.
Sources (2)
- https://www.irs.gov/tax-professionals/enrolled-agents/sample-special-enrollment-examination-questions-and-answers — read September 24, 2026
- https://www.gleim.com/enrolled-agent-review/ — read September 24, 2026
包含什么,不包含什么
包含
- Exam review, not an introduction: written to the PSI outline for people who already know what a tax return is and the basic vocabulary (income, deduction, credit, basis)
- Written to the PSI bulletin revised October 9, 2026, for the July 2026 – Feb 2027 window: tax year 2025 law, including the One Big Beautiful Bill Act
不包含
- 不寄送纸质书 —— 这是一份你下载后可自行打印的文件
- 购书不含视频课程、讲师或一对一辅导 —— 站上的免费视频是另一回事
完整的包含项与不包含项
包含
- 31 chapters that follow the bulletin's content outline domain by domain, for all three SEE parts, including trusts, exempt organizations, representation before the IRS and the e-file filing process
- 585 practice questions in all: three 100-question practice exams plus domain practice sets, weighted to the PSI outline, every answer explained and sourced
- A full OBBBA chapter: tips, overtime, car-loan interest, senior deduction, $40,000 SALT, $2,200 CTC
- Key Figures for Tax Year 2025: every indexed number filled in, with its source
- PDF (print & tab it) + EPUB (phone / e-reader)
不包含
- 不含考试报名费与考点费用,这些仍需向官方机构缴纳
目录
查看 60 个部分及各部分起始页
- Part 1 — Individuals Preliminary Work and Taxpayer Data (14) ·第 5 页
- Part 2 — Businesses Business Entities and Considerations (30) ·第 5 页
- Part 3 — Representation, Practices Practices and Procedures (26) ·第 5 页
- Part 1 — Preliminary Work 1, 2 Part I exam and domain sets and Taxpayer Data第 8 页
- Part 2 — Business Entities 15, 16, 19 Part II exam and domain and Considerations sets第 8 页
- Part 3 — Practices and 24, 25 Part III exam and domain第 8 页
- PART I — INDIVIDUALS (SEE Part 1)第 11 页
- Chapter 1 — Filing Status and Dependents第 12 页
- Part I Practice Exam, questions 1–9, 13, 15–16, 79, 81; Part I Domain Practice Sets, questions 152, 168 (16 questions).第 17 页
- Chapter 2 — Preliminary Work, Residency and Filing Requirements第 18 页
- Part I Domain Practice Sets, questions 101–114 (14 questions).第 32 页
- Chapter 3 — Gross Income: Inclusions and Exclusions第 33 页
- Part I Practice Exam, questions 18–22, 80 (6 questions).第 37 页
- Chapter 4 — Other Income and Information Returns第 38 页
- Part I Domain Practice Sets, questions 115–121 (7 questions).第 51 页
- Chapter 5 — Adjustments, the Standard Deduction, and Itemized Deductions第 52 页
- Practice questions for this chapter第 57 页
- Part I Practice Exam, questions 35–38, 41–44, 84, 87 (10 questions).第 57 页
- Chapter 6 — Itemized Deductions, QBI and Credits in Depth第 58 页
- Part I Domain Practice Sets, questions 135–151 (17 questions).第 74 页
- Chapter 7 — Tax Credits第 75 页
- Part I Practice Exam, questions 12, 14, 45–54; Part I Domain Practice Sets, questions 169 (13 questions).第 80 页
- Chapter 8 — Basis, Capital Gains and Losses, and the Sale of a Home第 81 页
- Part I Practice Exam, questions 23–29, 82; Part I Domain Practice Sets, questions 153–155 (11 questions).第 86 页
- Chapter 9 — Investments: Options, Digital Assets, Traders, Inherited Property第 87 页
- Part I Domain Practice Sets, questions 122–128 (7 questions).第 100 页
- Chapter 10 — Retirement Accounts and Distributions第 101 页
- Part I Practice Exam, questions 30–34, 83, 85 (7 questions).第 105 页
- Chapter 11 — Retirement Plans and HSAs in Depth第 106 页
- Part I Domain Practice Sets, questions 129–134, 170 (7 questions).第 121 页
- Chapter 12 — Self-Employment Tax, Estimated Tax, AMT, NIIT, and Transfer Taxes第 122 页
- Part I Practice Exam, questions 10–11, 57–73, 88–100; Part I Domain Practice Sets, questions 156–159 (36 questions).第 130 页
- Chapter 13 — Tax Year 2025: The One Big Beautiful Bill Act for Individuals第 131 页
- Part I Practice Exam, questions 17, 39–40, 55–56, 74–78 (10 questions).第 138 页
- Chapter 14 — Specialized Taxes and Advising the Individual Taxpayer第 139 页
- Part I Domain Practice Sets, questions 160–167, 171–177, 179–189 (26 questions).第 153 页
- Part I Practice Exam — Individuals (100 Questions)第 154 页
- Part I Practice Exam — Answers and Explanations第 178 页
- Part I Domain Practice Sets — Individuals (89 Questions)第 194 页
- Part I Domain Practice Sets — Answers and Explanations第 220 页
- PART II — BUSINESSES (SEE Part 2)第 236 页
- Chapter 15 — Choice of Entity and Accounting Methods第 237 页
- Part II Practice Exam, questions 1–3, 23, 31–32, 37, 72–74, 76–79 (14 questions).第 243 页
- Chapter 16 — Entity Classification, Partnerships and Corporations in Detail第 244 页
- Part II Domain Practice Sets, questions 101–130 (30 questions).第 262 页
- Chapter 17 — Business Income, §162 Expenses, and Depreciation第 263 页
- Part II Practice Exam, questions 36, 38–54, 60, 71, 75 (21 questions).第 270 页
- Chapter 18 — Business Income Computation, Records and Worker Classification第 271 页
- Part II Domain Practice Sets, questions 131–167 (37 questions).第 287 页
- Chapter 19 — Partnership and S Corporation Taxation and Basis第 288 页
- Part II Practice Exam, questions 4–22 (19 questions).第 295 页
- Chapter 20 — C Corporations, Payroll, and Employment Taxes第 296 页
- Part II Practice Exam, questions 24–30, 33–35, 67–70 (14 questions).第 302 页
- Chapter 21 — NOLs, Business Credits, QBI, and Property Dispositions第 303 页
- Part II Practice Exam, questions 55–59, 61–66 (11 questions).第 308 页
- Chapter 22 — Specialized Returns: Trusts and Estates, Exempt Organizations, Retirement Plans, Farmers, and Rental Property第 309 页
- Part II Practice Exam, questions 80–100 (21 questions).第 314 页
- Chapter 23 — Trusts, Exempt Organizations, Plans, Farmers and Rentals in Depth第 315 页
- Part II Domain Practice Sets, questions 168–185 (18 questions).第 334 页
- Part II Practice Exam — Businesses (100 Questions)第 335 页
取自你将下载的那份 PDF,并标明各章起始页 —— 不是在此手工录入的。 此处列出的是文件中 84 个标题的前一部分。
免费读完整一章
完整的一章,与电子书正文一字不差。直接在此窗口滚动阅读;无需下载,无需邮箱。
在本页直接阅读第 13 章
The free chapter is Chapter 13, the One Big Beautiful Bill Act for individuals: a fair middle-difficulty sample of the book's style, with a worked example and a key-figures list.
The rule: the current window already tests OBBBA
The One Big Beautiful Bill Act (Public Law 119-21, signed July 4, 2025) is not a problem for some future SEE window. It is in the window you are sitting now. The IRS says the July 1, 2026 – February 28, 2027 exam refers to the Code, forms and publications "as amended through Dec. 31, 2025," and that "all questions relate to the calendar year 2025." Every OBBBA provision effective for 2025 is therefore testable. Provisions that start in 2026 are not, and neither is any legislation or penalty amount after December 31, 2025.
The IRS now calls these provisions the "Working Families Tax Cuts." This chapter teaches the individual changes with their 2025 numbers. The business changes (§179, 100% bonus depreciation, §174A research expensing, the commercial clean-vehicle credit) are taught in Chapter 17.
| Provision | 2025 rule | Where claimed |
|---|---|---|
| Standard deduction | $15,750 single/MFS; $31,500 MFJ/QSS; $23,625 HoH | Form 1040 line 12e |
| No tax on tips | Up to $25,000; phase-down over $150,000 MAGI ($300,000 MFJ) | Schedule 1-A Part II |
| No tax on overtime | Up to $12,500 ($25,000 MFJ) of the FLSA premium; same phase-down | Schedule 1-A Part III |
| Car loan interest | Up to $10,000; phase-down over $100,000 MAGI ($200,000 MFJ) | Schedule 1-A Part IV |
| Enhanced senior deduction | $6,000 per person 65+; phase-down over $75,000 MAGI ($150,000 MFJ) | Schedule 1-A Part V |
| SALT cap | $40,000 ($20,000 MFS); reduced over $500,000 MAGI ($250,000 MFS), never below $10,000 ($5,000) | Schedule A line 5e |
| Child tax credit | $2,200 per child, up to $1,700 refundable; SSN rules | Schedule 8812 |
| Adoption credit | Up to $5,000 refundable | Form 8839 |
| Clean vehicle credits (§30D, §25E, §45W) | No credit for vehicles acquired after Sept. 30, 2025 | Form 8936 |
| Home energy credits (§25C, §25D) | End after Dec. 31, 2025 | Form 5695 |
Sources: IRS FAQ "What tax law is the examination based on?"; IRS, "How to update withholding to account for tax law changes for 2025"; 2025 Instructions for Form 1040 (What's New); 2025 Schedule 1-A; IRS, One Big Beautiful Bill provisions page. All read 2026-09-23.
The rule: the four Schedule 1-A deductions
Tips, overtime, car loan interest and the senior deduction share four features, and the exam tests all four:
- They are available whether or not the taxpayer itemizes.
- They do not reduce AGI. Schedule 1-A totals on Form 1040 line 13b, after AGI. Anything keyed to AGI (the medical floor, IRA phase-outs, the NIIT) is unaffected.
- Married taxpayers must file jointly to claim the tips, overtime or senior deduction, and the person claiming must have an SSN valid for employment.
- They are temporary: 2025 through 2028.
No tax on tips. Tips stay in gross income and stay subject to Social Security and Medicare tax. The deduction covers up to $25,000 of qualified tips: voluntary cash or charged tips received in an occupation the IRS lists as customarily and regularly receiving tips on or before December 31, 2024. Mandatory service charges are not qualified tips. Neither are tips received in a specified service trade or business. A self-employed person's qualified tips are limited to the net profit of the business that received them. The deduction is reduced by $100 for each full $1,000 of MAGI over $150,000 ($300,000 MFJ); a fraction of $1,000 is rounded down.
No tax on overtime. Only the premium portion counts: the pay above the regular rate that the Fair Labor Standards Act requires. For time-and-a-half, that is the "half." The cap is $12,500 ($25,000 MFJ), and the phase-down works like the tips deduction.
No tax on car loan interest. Interest of up to $10,000 a year on a loan that:
- originated after December 31, 2024;
- was used to buy a vehicle whose original use began with the taxpayer (used vehicles do not qualify);
- is secured by a first lien on the vehicle; and
- financed a car, minivan, van, SUV, pickup or motorcycle under 14,000 pounds, bought for personal use, that had final assembly in the United States.
Leases do not qualify, and the VIN must be reported. The phase-down is $200 for each $1,000 of MAGI over $100,000 ($200,000 MFJ), and here a fraction of $1,000 is rounded up.
Enhanced deduction for seniors. $6,000 for each taxpayer who is 65 or older by year-end, or $12,000 on a joint return if both spouses qualify. It is in addition to the existing additional standard deduction for age ($2,000 single or HoH, $1,600 per married individual). Each $6,000 is reduced by 6% of MAGI over $75,000 ($150,000 MFJ).
Worked example — overtime and tips together
Dana is single, a restaurant server, and her MAGI is $162,400. Her W-2 shows $14,000 of qualified tips. She also worked 200 FLSA overtime hours at $36 an hour when her regular rate is $24.
- Qualified overtime = 200 × (36 − 24) = 200 × $12 = $2,400. The full $7,200 of overtime pay is not the measure.
- MAGI over $150,000 = $12,400. Full thousands = 12, so each deduction is reduced by 12 × $100 = $1,200.
- Tips deduction = 14,000 − 1,200 = $12,800.
- Overtime deduction = 2,400 − 1,200 = $1,200.
- Both go on Schedule 1-A and reduce taxable income. Her AGI stays $162,400.
Worked example — car loan interest and the senior deduction
Mr. and Mrs. Ortiz, both 67, file jointly with MAGI of $212,300. In March 2025 they bought a new U.S.-assembled SUV for personal use and paid $2,900 of interest on the loan that year.
- Car loan: MAGI over $200,000 = $12,300 → 12.3, rounded up to 13 → 13 × $200 = $2,600 reduction. Deduction = 2,900 − 2,600 = $300.
- Senior: MAGI over $150,000 = $62,300; 6% × 62,300 = $3,738. Each spouse gets 6,000 − 3,738 = $2,262, so $4,524 in total.
- Standard deduction: $31,500 + 2 × $1,600 = $34,700, with the Schedule 1-A deductions on top.
The rule: the SALT cap is $40,000, with a phase-down
For 2025 an itemizer may deduct up to $40,000 of state and local income (or sales), real property and personal property taxes, or $20,000 if married filing separately. That is up from $10,000 ($5,000). The limit is reduced by 30% of MAGI over $500,000 ($250,000 MFS), but never below $10,000 ($5,000 MFS). MAGI here is AGI plus certain excluded foreign and territory income.
Worked example — the SALT phase-down
A couple filing jointly has MAGI of $560,000 and paid $45,000 of state income and property tax.
- Excess MAGI = 560,000 − 500,000 = $60,000; 30% × 60,000 = $18,000.
- Limit = 40,000 − 18,000 = $22,000 (above the $10,000 floor).
- SALT deduction = lesser of $45,000 paid or $22,000 = $22,000.
At MAGI of $600,000 or more, 30% of the excess is at least $30,000, and the limit bottoms out at the $10,000 floor.
The rule: credits that changed for 2025
- Child tax credit: $2,200 per qualifying child, of which up to $1,700 is refundable as the ACTC. The $200,000 ($400,000 MFJ) phase-out and the $50-per-$1,000 reduction are unchanged. The taxpayer must have an SSN valid for employment, issued by the return due date, and on a joint return one spouse is enough if the other has an SSN or ITIN. The child must also have a valid SSN. The $500 credit for other dependents is unchanged.
- Adoption credit: the 2025 maximum is $17,280, and up to $5,000 of it is now refundable.
- Clean vehicles: the new (§30D), used (§25E) and commercial (§45W) clean vehicle credits are not allowed for any vehicle acquired after September 30, 2025.
- Home energy: the energy efficient home improvement credit (§25C) ends for property placed in service after December 31, 2025. The residential clean energy credit (§25D, 30%) ends for expenditures made after December 31, 2025. Both are still available for qualifying 2025 work.
The rule: what OBBBA changed that is not on this window
These provisions take effect after 2025. A question about "the current year" means 2025, so answer as though they do not exist yet:
- a charitable deduction for non-itemizers of up to $1,000 ($2,000 MFJ), and a 0.5%-of-AGI floor on itemized charitable gifts, both beginning in 2026;
- a $15,000,000 basic exclusion amount for decedents dying in 2026 (2025 is $13,990,000);
- removal of the repayment cap on excess advance premium tax credit, for tax years beginning after December 31, 2025. For 2025 the cap still applies.
Worked example — putting 2025 together
Leo, 45, single, has wages of $120,000, including $6,000 of qualified overtime premium. He has no other income, so his MAGI is $120,000. He pays $9,000 of state income tax and $7,000 of property tax, and $8,000 of mortgage interest.
- Itemized: SALT $16,000 (under the $40,000 limit, no phase-down) + mortgage $8,000 = $24,000, which beats the $15,750 standard deduction.
- Overtime: $6,000 (MAGI under $150,000, so no reduction).
- Taxable income = 120,000 − 24,000 − 6,000 = $90,000. Under the old $10,000 SALT cap he would have itemized only $18,000, and there would have been no overtime deduction.
Key figures — tax year 2025 (OBBBA) - Standard deduction $15,750 / $31,500 / $23,625; additional for 65+/blind $2,000 (unmarried) / $1,600 (married). - Senior deduction $6,000 per person; −6% of MAGI over $75,000 / $150,000. - Tips $25,000; overtime $12,500 / $25,000 MFJ; both −$100 per full $1,000 over $150,000 / $300,000. - Car loan interest $10,000; −$200 per $1,000 (rounded up) over $100,000 / $200,000. - SALT $40,000 / $20,000 MFS; −30% of MAGI over $500,000 / $250,000 MFS; floor $10,000 / $5,000. - CTC $2,200 (ACTC up to $1,700); ODC $500; adoption credit $17,280, up to $5,000 refundable. - §30D/§25E/§45W: none for vehicles acquired after 9/30/2025. §25C/§25D: end after 12/31/2025.
Common traps
- Calling the tips or overtime deduction an exclusion. The income stays in wages and in FICA. The deduction comes later, below AGI.
- Deducting the whole overtime paycheck. Only the FLSA premium, the "half," is qualified.
- Letting a married-filing-separately taxpayer claim tips, overtime or the senior deduction. A joint return is required.
- Using $10,000 as the 2025 SALT cap, or treating the phase-down as a phase-out to zero. The floor is $10,000.
- Rounding the car loan phase-down the same way as tips. Tips and overtime round the excess down to full thousands; car loan interest rounds up.
- Applying 2026 rules to a 2025 question, such as the non-itemizer charitable deduction or the $15 million estate exclusion.
Practice questions for this chapter
Part I Practice Exam, questions 17, 39–40, 55–56, 74–78 (10 questions).
购买者常问的问题
怎么拿到?
付款后下载入口立即出现在本页,链接同时发到你的邮箱。无需注册账号。
不合适怎么办?
14 天内发邮件即可全额退款,无需理由。
免费练习会取消吗?
不会。站上的每一道练习题、计时模考和免费章节都继续免费。这本书是「学」的那一半,不是把免费部分围起来的门。
更多问题 (1)
能在手机上看吗?
可以 —— EPUB 适合手机和电子书阅读器,PDF 适合打印和贴标签,两种都给你。
练习免费,为什么还要买书?
我们的练习题和计时模考一直免费 —— 网站上的东西不会因为这本书而收起来。这本 $22.99 的书是「学」的那一半:知识本身,按顺序讲清楚,存成一份属于你的文件。
- 系统讲解 —— 每个考试部分按章节从头讲到尾,不只是题目
- 可打印可贴标签 —— 一份适合打印的 PDF,能划重点、做批注、带到书桌前
- 随处离线学 —— EPUB 放手机或电子书阅读器;不用 wifi,不用一堆浏览器标签
- 全在一处 —— 章节和练习题都在同一份文件里
- 永久归你 —— 一次 $22.99,即时下载,无订阅
详细信息
- 官方来源核验(public Internal Revenue Code, IRS publications, and Circular 230)
- 913 道免费练习题
EA review course 要 $500–$1,500。这本书讲的是同一门考试 —— 同样的规则、核对到最新标准 —— 只需一次性 $22.99,永久归你。
一次购买,永久下载访问。此电子书是完整的 IRS Enrolled Agent Exam (SEE) 学习指南,含 PDF 与 EPUB。仅为教育性摘要,非专业或法律意见 —— 请始终以官方来源核实当前规定。最后更新:October 2026。