学习指南 · 2026 版
Series 66 — Uniform Combined State Law — Complete Study Guide (2026)
Nineteen chapters that follow NASAA's four content areas, law first.
- 篇幅
- 747 页(讲解 193 页 + 题库)
- 书内练习题
- 1,161
- PrepPass 在线计时模考
- 100 题 · 150 分钟
- 考试事实核对与文件更新
- 2026年10月
- 交付
- PDF + EPUB · 英文 · 即时下载
购买前请阅读: This is an independent study aid, not affiliated with or endorsed by NASAA, FINRA, or Prometric.
阅读本声明的其余部分
The Series 66 is a NASAA exam administered by FINRA; this guide is authored from the public Uniform Securities Act, NASAA model rules, and the Investment Advisers Act of 1940. Some dollar thresholds (the qualified-client net worth/AUM figures, the gift-tax exclusion) are indexed and change — this guide teaches the underlying rules and flags indexed figures to 'verify current year'; it is general educational information, not legal or investment advice.
关于本书
Nineteen chapters that follow NASAA's four content areas, law first: the Uniform Securities Act, NASAA model rules and the Investment Advisers Act of 1940, plus the economics and product knowledge the Series 66 tests.
考试费:每次 $177,缴给 FINRA。补考要再交一次。本指南:$24.99,一次买断。
考试事实、适合谁与变化
关于这场考试本身
| 主管机构 | North American Securities Administrators Association (NASAA) —— 考试由 FINRA 承办 |
|---|---|
| 题目数量 | 110 道题 (100 道计分,10 道不计分预试题) |
| 考试时限 | 150 分钟 |
| 及格标准 | 100 题中答对 73 题 |
| 费用 |
|
| 考试语言 | 英语 |
翻开这本书看看
三页真实内页,直接从你将下载的 PDF 渲染而来 —— 依次是一页速查、一页讲解、一道带解析的例题。没有任何一页是为了好看而重画的。
- 速查页Appendix — Question Bank 1,161 practice questions with answers and explanations · PDF 第 628 页
一页可以随时翻回来的内容:把数字、期限或术语集中在一处。
- 怎么讲Chapter 14 — Equity and Valuation Common stock, ADRs and shareholder rights · PDF 第 153 页
讲解页:用文字把知识讲清楚,顺序与考试考查的顺序一致。
- 一道题的完整解析Appendix — Question Bank 1,161 practice questions with answers and explanations · PDF 第 356 页
一道练习题,连同答案和背后的推理 —— 不只是一个答案键。
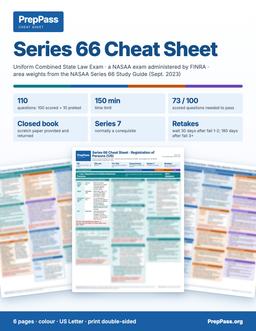
两周内就要考试?
这本指南是系统讲解,要花几周读。如果两周内就考,可打印的彩色速查表是另一款产品:考试涉及的关键数字,按章节排好。
6 页 · US Letter · 可打印 PDF · 永久保存
包含什么,不包含什么
包含
- Nineteen chapters covering NASAA's four content areas, law first (45%), with a table mapping the chapters to the official weights
- Every chapter closes with a key-facts box and a named exam-traps list
不包含
- 不寄送纸质书 —— 这是一份你下载后可自行打印的文件
- 购书不含视频课程、讲师或一对一辅导 —— 站上的免费视频是另一回事
完整的包含项与不包含项
包含
- Registration of broker-dealers, agents, advisers and representatives, exempt securities versus exempt transactions, Administrator powers, the Investment Advisers Act of 1940 and fiduciary duty
- Worked math: Sharpe ratio, beta, CAPM, taxable-equivalent yield, duration, time value of money
- Prohibited and unethical business practices, the most heavily tested trap area
- 193 pages of teaching, then a question bank of 1161 practice questions, grouped by topic, with answers and explanations
- PDF (print & tab it) + EPUB (phone / e-reader)
不包含
- 不含考试报名费与考点费用,这些仍需向官方机构缴纳
目录
查看 21 个部分及各部分起始页
- Chapter 1 — Federal Law Foundations第 11 页
- Section 15: broker-dealers register with the SEC, join a self-regulatory第 21 页
- Chapter 2 — Adviser Registration and Compliance Investment adviser representatives, qualification第 24 页
- Chapter 3 — Broker-Dealer and Agent Registration, Records and Supervision第 33 页
- Chapter 4 — The State Act, 1956 and 2002, and Communications第 42 页
- Chapter 5 — Conduct, AML, Privacy, Seniors and Due Diligence第 54 页
- Chapter 6 — FINRA Rules and Regulation Best Interest第 64 页
- Chapter 7 — Client Types and Profiling第 70 页
- Chapter 8 — Strategies and Techniques Modern portfolio theory and the efficient frontier第 78 页
- Chapter 9 — Taxation Income tax brackets and marginal rates (2026)第 85 页
- Chapter 10 — Retirement Plans and ERISA Retirement plan types and 2026 limits第 95 页
- Chapter 11 — Education, Health, Ownership and Estate第 107 页
- Chapter 12 — Trading and Returns Order types and how they execute第 119 页
- Chapter 13 — Cash and Fixed Income Insured deposits and the money market第 130 页
- Chapter 14 — Equity and Valuation Common stock, ADRs and shareholder rights第 142 页
- Chapter 15 — Offerings and Equity Compensation第 151 页
- Chapter 16 — Pooled Products and Derivatives Unit investment trusts, ETFs and REITs第 160 页
- Chapter 17 — Annuities, Insurance, Alternatives and Digital Assets第 172 页
- Chapter 18 — Quantitative Methods第 181 页
- Chapter 19 — Financial Ratios and Valuation Models第 188 页
- Appendix — Question Bank 1,161 practice questions with answers and explanations第 194 页
取自你将下载的那份 PDF,并标明各章起始页 —— 不是在此手工录入的。
免费读完整一章
完整的一章,与电子书正文一字不差。直接在此窗口滚动阅读;无需下载,无需邮箱。
在本页直接阅读第 18 章
我们没有拿轻松的绪论充数 —— 免费章节直接翻到书里最见功力的部分,让你在考试真正难的地方检验这本书讲得好不好。
Time value of money: future value, present value, NPV and IRR
Money received sooner is worth more than money received later, because it can be invested. All the formulas below use one idea: moving a dollar amount across time at a rate of return.
Future value
FV = PV x (1 + r)^n
Worked example. $10,000 invested at 6% a year for 8 years: $10,000 x 1.06^8 = $10,000 x 1.5938 = $15,938.48.
If interest compounds quarterly the rate per period is 6% / 4 = 1.5% and there are 8 x 4 = 32 periods: $10,000 x 1.015^32 = $16,103.24. More frequent compounding gives a larger amount.
Rule of 72. Years to double is about 72 divided by the annual rate in percent. At 6%, 72 / 6 = 12 years. Check: $10,000 x 1.06^12 = $20,121.96. The rule is an approximation that works best between 6% and 10%.
Present value
PV = FV / (1 + r)^n
Worked example. A client wants $20,000 in 5 years and can earn 7%. PV = $20,000 / 1.07^5 = $20,000 / 1.4026 = $14,259.72. The client needs $14,259.72 today.
Present value of a series. To receive $1,000 at the end of each year for 5 years with a 6% discount rate, discount each payment: $943.40 + $890.00 + $839.62 + $792.09 + $747.26 = $4,212.36.
A higher discount rate gives a lower present value; a longer time gives a lower present value.
Net present value
NPV is the sum of the present values of all cash flows, including the initial outlay, discounted at the required rate of return.
Worked example. A project costs $10,000 now and returns $3,000, $4,000 and $5,000 at the end of years 1, 2 and 3. The required return is 8%.
| Year | Cash flow | Discount factor | Present value |
|---|---|---|---|
| 0 | -$10,000 | 1.0000 | -$10,000.00 |
| 1 | $3,000 | 1/1.08 | $2,777.78 |
| 2 | $4,000 | 1/1.08^2 | $3,429.36 |
| 3 | $5,000 | 1/1.08^3 | $3,969.16 |
| NPV | +$176.29 |
NPV is positive, so the project earns more than 8% and adds value. Decision rule: accept if NPV is greater than zero; reject if negative. The profitability index (present value of inflows / outlay) is 10,176.29 / 10,000 = 1.018.
Internal rate of return
IRR is the discount rate at which NPV equals zero. There is no direct formula. Solve by trying rates.
Worked example (same project).
| Trial rate | NPV |
|---|---|
| 8% | +$176.29 |
| 9% | -$20.07 |
| 10% | -$210.37 |
The sign changes between 8% and 9%, so the IRR is just under 9%. Linear interpolation between 8% and 10%: 8% + 2% x 176.29 / (176.29 + 210.37) = 8% + 0.91% = 8.91%. Refining gives IRR = 8.90%. At 8.90%, NPV is almost exactly zero.
Decision rule: accept if IRR is greater than the required return (8.90% > 8%: accept). The NPV and IRR rules agree here.
When NPV and IRR disagree. For mutually exclusive projects of different size or cash-flow timing, IRR can rank the projects differently than NPV. NPV assumes cash flows are reinvested at the required rate; IRR assumes reinvestment at the IRR itself, which is less realistic. A project with cash flows that change sign more than once can have more than one IRR. In these cases NPV is the better guide because it measures the dollar value added.
Where it appears in advice. IRR is used to compare investments with irregular cash flows, such as private equity. The money-weighted return of a portfolio with deposits and withdrawals is an IRR.
Key facts — Time value of money: future value, present value, NPV and IRR - FV = PV x (1 + r)^n; PV = FV / (1 + r)^n. - Rule of 72: doubling time = 72 / rate. - NPV > 0: accept. IRR > required return: accept. - IRR is the rate at which NPV = 0. - NPV is preferred when NPV and IRR conflict.
Exam traps
- Using the annual rate with monthly periods.
- Forgetting the initial outlay in NPV.
- Assuming a higher IRR project is always better than a larger project with a higher NPV.
Descriptive statistics: mean, median, mode, range and standard deviation
Mean, median, mode and range
Worked example. A fund's monthly returns (in percent) over seven months: 4, 8, 6, 5, 3, 8, 9.
- Sort: 3, 4, 5, 6, 8, 8, 9.
- Mean = (4 + 8 + 6 + 5 + 3 + 8 + 9) / 7 = 43 / 7 = 6.14.
- Median = the middle value of the sorted list = 6. With an even count, the median is the average of the two middle values; for 2, 4, 7, 9 the median is (4 + 7) / 2 = 5.5.
- Mode = the most frequent value = 8.
- Range = highest minus lowest = 9 - 3 = 6.
The median is not changed by an outlier; the mean is. If the last value were 90, the mean would jump while the median would stay at 6.
Arithmetic and geometric mean. The arithmetic mean averages the returns. The geometric mean gives the true compound rate. A fund that gains 50% one year and loses 50% the next has an arithmetic mean of (50% + (-50%)) / 2 = 0%, but $100 becomes $150 then $75. The geometric mean is the square root of (1.50 x 0.50) minus 1 = square root of 0.75 minus 1 = -13.40% a year. The geometric mean is always at most the arithmetic mean, and the gap grows with volatility.
Standard deviation, calculated by hand
Standard deviation (SD) measures how far returns scatter around their mean. It is the square root of the variance.
Worked example. Four annual returns: 10%, 4%, -2%, 8%.
- Mean = (10 + 4 - 2 + 8) / 4 = 5.
- Deviations from the mean: 5, -1, -7, 3.
- Squared deviations: 25, 1, 49, 9. Sum = 84.
- Population variance (divide by n = 4) = 84 / 4 = 21. SD = square root of 21 = 4.58%.
- Sample variance (divide by n - 1 = 3) = 84 / 3 = 28. SD = square root of 28 = 5.29%.
Use the sample SD when the returns are a sample of a longer record (the usual case for a fund's history); use the population SD when the data are the whole group.
Interpretation. For a roughly normal distribution, about 68% of outcomes fall within one SD of the mean, 95% within two, and 99.7% within three. A fund with a mean return of 8% and an SD of 12% has a 68% range of -4% to 20% and a 95% range of -16% to 32%.
Coefficient of variation = SD / mean, the risk per unit of return. Fund A has mean 8%, SD 12%: 1.50. Fund B has mean 6%, SD 6%: 1.00. Fund B has less risk per unit of return.
Key facts — Descriptive statistics: mean, median, mode, range and standard deviation - Mean is sensitive to outliers; median is not. - Range = highest - lowest. - Population SD divides by n; sample SD divides by n - 1. - About 68%, 95%, 99.7% within 1, 2, 3 SDs for normally distributed returns. - Geometric mean is at most the arithmetic mean.
Exam traps
- Reading SD as a loss measure. It measures dispersion in both directions.
- Using the arithmetic mean to describe multi-year growth.
- A data set can have no mode, or more than one mode.
Covariance, correlation and combined risk
Covariance measures whether two assets tend to move together. Correlation rescales covariance to a number between -1 and +1:
Correlation = covariance(X, Y) / (SD of X x SD of Y)
Worked example. Annual returns of two funds over four years (in percent):
| Year | Fund X | Fund Y |
|---|---|---|
| 1 | 10 | 6 |
| 2 | 4 | 3 |
| 3 | -2 | 5 |
| 4 | 8 | -2 |
| Mean | 5 | 3 |
- Deviations of X: 5, -1, -7, 3. Deviations of Y: 3, 0, 2, -5.
- Products: 5 x 3 = 15; -1 x 0 = 0; -7 x 2 = -14; 3 x -5 = -15. Sum = -14.
- Sample covariance = -14 / 3 = -4.667.
- SD of X (sample) = 5.29 (from the earlier example). Squared deviations of Y: 9, 0, 4, 25 = 38; variance = 38 / 3 = 12.667; SD of Y = 3.56.
- Correlation = -4.667 / (5.29 x 3.56) = -0.248.
The correlation is weakly negative. Combining the funds should reduce portfolio risk.
Why correlation matters: a two-asset portfolio. Portfolio SD is not the weighted average of the SDs. For weights w1 and w2:
SD(portfolio) = square root of [ (w1 x SD1)^2 + (w2 x SD2)^2 + 2 x w1 x w2 x SD1 x SD2 x correlation ]
With 60% in a stock fund (SD 20%) and 40% in a bond fund (SD 10%), correlation 0.3:
- (0.60 x 20)^2 = 144
- (0.40 x 10)^2 = 16
- 2 x 0.60 x 0.40 x 20 x 10 x 0.3 = 28.8
- Variance = 144 + 16 + 28.8 = 188.8. SD = 13.74%.
The weighted average of the SDs is 0.6 x 20 + 0.4 x 10 = 16%. Diversification cut the risk to 13.74%. If the correlation were +1, the portfolio SD would equal 16%, so there would be no diversification benefit. The lower the correlation, the larger the benefit; at -1 risk can be eliminated with the right weights. Diversification reduces unsystematic risk only; it cannot reduce market risk.
R-squared is the square of the correlation with a benchmark: the share of a fund's movement explained by the benchmark. A correlation of 0.9 gives R-squared of 0.81, meaning 81%.
R-squared is usually read together with tracking error, the amount by which a fund's returns deviate from its benchmark's. A high R-squared says the fund moves with the benchmark. A low tracking error says its returns stay close to the benchmark's. An adviser who wants to know how closely a fund follows its index looks at both: R-squared close to 1 (100%) and a small tracking error describe an index-like fund. Sharpe ratio and standard deviation describe risk-adjusted return and volatility, and beta describes sensitivity to the market; none of them measures how closely a fund follows a benchmark.
Key facts — Covariance, correlation and combined risk - Correlation ranges from -1 to +1. Covariance has no fixed range. - Portfolio SD is less than the weighted average SD unless correlation is +1. - R-squared = correlation squared. - R-squared plus tracking error measure how closely a fund follows its benchmark.
Exam traps
- Correlation of zero means no linear relationship, not no risk.
- A negative covariance does not mean negative returns.
- Diversification does not remove systematic risk.
购买者常问的问题
怎么拿到?
付款后下载入口立即出现在本页,链接同时发到你的邮箱。无需注册账号。
不合适怎么办?
14 天内发邮件即可全额退款,无需理由。
免费练习会取消吗?
不会。站上的每一道练习题、计时模考和免费章节都继续免费。这本书是「学」的那一半,不是把免费部分围起来的门。
更多问题 (1)
能在手机上看吗?
可以 —— EPUB 适合手机和电子书阅读器,PDF 适合打印和贴标签,两种都给你。
练习免费,为什么还要买书?
我们的练习题和计时模考一直免费 —— 网站上的东西不会因为这本书而收起来。这本 $24.99 的书是「学」的那一半:知识本身,按顺序讲清楚,存成一份属于你的文件。
- 系统讲解 —— 每个考试部分按章节从头讲到尾,不只是题目
- 可打印可贴标签 —— 一份适合打印的 PDF,能划重点、做批注、带到书桌前
- 随处离线学 —— EPUB 放手机或电子书阅读器;不用 wifi,不用一堆浏览器标签
- 全在一处 —— 章节和练习题都在同一份文件里
- 永久归你 —— 一次 $24.99,即时下载,无订阅
详细信息
- 官方来源核验(Uniform Securities Act, NASAA test specifications and model rules, and the Investment Advisers Act of 1940)
- 1,161 道免费练习题
Series 66 prep course 要 $400–$800。这本书讲的是同一门考试 —— 同样的规则、核对到最新标准 —— 只需一次性 $24.99,永久归你。
一次购买,永久下载访问。此电子书是完整的 NASAA Series 66 (Uniform Combined State Law) 学习指南,含 PDF 与 EPUB。仅为教育性摘要,非专业或法律意见 —— 请始终以官方来源核实当前规定。最后更新:October 2026。