Guía de estudio · Edición 2026
Series 7 — General Securities Representative Study Guide (2026)
Thirty-three chapters written to FINRA's Series 7 content outline.
- Extensión
- 1,031 páginas (528 de enseñanza + banco de preguntas)
- Preguntas de práctica en el libro
- 1,176
- Simulacro en línea de PrepPass
- 125 preguntas · 225 min
- Datos verificados y archivo actualizado
- octubre de 2026
- Entrega
- PDF + EPUB · en inglés · descarga inmediata
Léelo antes de comprar: This is an independent study aid, not affiliated with or endorsed by FINRA, the SEC, MSRB, the OCC, or any test-delivery vendor (including Prometric).
Leer el resto de este aviso
Securities rules change and many figures (contribution limits, gift limits) are indexed or were recently updated; confirm the current rules before you rely on any figure.
Sobre este libro
Thirty-three chapters written to FINRA's Series 7 content outline: options, margin, municipals, bonds and every product a representative recommends, with the math worked step by step.
Tarifa del examen: $395 por intento, que se paga a FINRA. Repetir el examen vuelve a costarlo. Esta guía: $24.99, pago único.
Datos del examen, a quién le sirve y qué cambió
Sobre el examen en sí
| Organismo administrador | Financial Industry Regulatory Authority (FINRA) Fuente: FINRA — Series 7 – General Securities Representative Exam (GS) |
|---|---|
| Preguntas | 130 preguntas (125 calificadas, 5 de prueba sin calificar) |
| Tiempo límite | 225 minutos |
| Puntuación para aprobar | No publicado por FINRA (scale range) Lo que leímos y donde no aparece: FINRA — Series 7 – General Securities Representative Exam (GS) |
| Tarifas |
Fuente: FINRA — Series 7 – General Securities Representative Exam (GS) |
| Idiomas disponibles | No publicado por FINRA Lo que leímos y donde no aparece: FINRA — Series 7 – General Securities Representative Exam (GS) |
Mira dentro del libro
Tres páginas reales, renderizadas directamente del PDF que descargas — una página de referencia, una de explicación y una pregunta resuelta, siempre en ese orden. Nada se rediseñó para verse mejor.
- Referencia rápidaSection 7 — Government securities, CMOs and CDs · Página 29 del PDF
Una página a la que puedes volver: cifras, plazos o términos reunidos en un solo lugar.
- Cómo se enseñaChapter 8 — Margin Accounts and Margin Calculations · Página 240 del PDF
Una página de explicación: el material enseñado en prosa, en el orden en que lo evalúa el examen.
- Una pregunta resueltaSection 1 — FINRA Rule 2210: the master rule for communications · Página 16 del PDF
Una pregunta de práctica con su respuesta y el razonamiento detrás — no solo la clave.
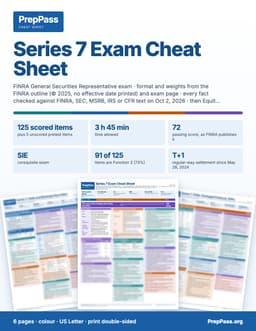
¿Examen en menos de dos semanas?
Esta guía es la enseñanza, para leer durante semanas. Si tu examen es en menos de dos semanas, la hoja de referencia a color imprimible es el otro producto: las cifras clave, por secciones.
6 páginas · US Letter · PDF imprimible · tuyo para siempre
Qué incluye — y qué no
Incluido
- Thirty-three chapters organised by topic, with a table mapping them to FINRA's four outline functions; most of the book is the recommendation and product knowledge that is most of the exam
- Key-facts boxes and named exam-traps lists inside the chapters
No incluido
- No se envía copia impresa — es un archivo que descargas y puedes imprimir tú
- El libro no incluye curso en vídeo, instructor ni tutorías — los vídeos gratis del sitio van aparte
Todo lo incluido y todo lo que no
Incluido
- The options math worked step by step: breakeven, maximum gain and loss, spreads, straddles, hedging
- Margin and Regulation T, bond and municipal math, MSRB rules, packaged products and customer accounts
- Dated 2026 changes called out: the $300 gift limit, the new intraday margin standards, FINRA Rule 3290 (approved, no effective date yet)
- 528 pages of teaching, then a question bank of 1176 practice questions, grouped by topic, with answers and explanations
- PDF (print & tab it) + EPUB (phone / e-reader)
No incluido
- No incluye tu inscripción al examen ni la tasa del centro, que sigues pagando al organismo oficial
Contenido
Ver 60 secciones y la página en la que empieza cada una
- Chapter 1 — Communications, Contact Rules and Protecting Customers From Fraudp. 12
- Section 1 — FINRA Rule 2210: the master rule for communicationsp. 12
- Section 2 — Seminars, lectures and other group forumsp. 19
- Section 3 — Investment company and variable contract communicationsp. 21
- Section 4 — Options communications and the Options Disclosure Documentp. 23
- Section 5 — Municipal securities advertising: MSRB Rule G-21p. 26
- Section 6 — Research reports and quiet periodsp. 27
- Section 7 — Government securities, CMOs and CDsp. 29
- Section 9 — Identity theft (Regulation S-ID), AML red flags and senior investorsp. 35
- Chapter 2 — How New Securities Reach the Marketp. 39
- Section 2.1 The sequence of a registered corporate offeringp. 39
- Section 2.2 IPO communications and the anti- abuse rulesp. 47
- Section 2.3 Underwriters, syndicates and the spreadp. 51
- Section 2.4 Municipal primary offeringsp. 56
- Section 2.5 Other statutes touching an offeringp. 60
- Section 2.6 FINRA rules for offerings and firm arrangementsp. 63
- Section 2.7 — Exempt Offerings, Private Placements and Resalesp. 66
- Chapter 3 — Opening and Maintaining Customer Accountsp. 83
- Section 3.1 — Account types: day trading, prime brokerage, DVP/RVP, advisoryp. 83
- Section 3.2 — Account registration typesp. 87
- Section 3.3 — Opening an account: FINRA Rule 4512 and the new account formp. 91
- Section 3.4 — Retirement plans: IRAsp. 94
- Section 3.5 — Employer plans, ERISA, and equity compensationp. 98
- Section 3.6 — Education savings: 529 plans and Coverdell ESAsp. 104
- Section 3.7 — Wealth events, decedent accounts, and changes in registrationp. 107
- Section 3.8 — Customer screening: CIP, KYC, residency, insiders and industry employeesp. 109
- Section 3.9 — Privacy and information security: Regulation S-Pp. 113
- Section 3.10 — Authority to act: POA, trading authorization, discretion, entity documentsp. 116
- Section 3.11 — Putting it together: the account- opening sequencep. 119
- Chapter 4 — Knowing the Customer, Recommending, and Supervising the Accountp. 120
- Section 1 — The essential facts about every customerp. 120
- Section 2 — The financial factors and how each steers a recommendationp. 123
- Section 3 — Investment objectivesp. 128
- Section 4 — Suitability under Rule 2111, and what Reg BI replacedp. 129
- Section 5 — Strategies, “hold” recommendations, and verifying accreditation and sophisticationp. 132
- Section 6 — Regulation Best Interest, Form CRS, and Rule 2214p. 135
- Section 7 — Principal review, approvals and documentationp. 141
- Section 8 — Receipt, delivery and safeguarding of cash, checks and securitiesp. 144
- Section 9 — Refusing, restricting and closing accountsp. 148
- Chapter 5 — Trading, Orders and Market Structurep. 153
- Section 1 — Taking the order: solicited, unsolicited, and the order ticketp. 153
- Section 2 — Quotes: what a price on the screen meansp. 156
- Section 3 — Basic order types, and what triggers whatp. 158
- Section 4 — Special orders and instructions Instruction What it doesp. 162
- Section 5 — Short salesp. 164
- Section 6 — Securities lending, hard-to-borrow stocks, and failsp. 167
- Section 7 — Best execution, interpositioning and order handlingp. 169
- Section 8 — Execution mechanics: priority, precedence, crossing, auctionsp. 171
- Section 9 — Market makers, principal vs agency, riskless principal, and markupsp. 173
- Section 10 — Halts, limit up-limit down, and circuit breakersp. 176
- Section 11 — Alternative trading systems, OTC quotations, and automated executionp. 179
- Chapter 6 — Delivery, Settlement and Trade Reportingp. 182
- Chapter 7 — Errors, Complaints, Disputes and Disciplinep. 196
- Chapter 8 — Margin Accounts and Margin Calculationsp. 208
- Chapter 9 — Conduct, Registration, Customer Protection and the Tax and Economic Backdropp. 237
- Chapter 10 — Matching Securities to the Customer, and Portfolio Theoryp. 266
- Chapter 11 — Annual Reports, Corporate Actions and Tender- Offer Informationp. 274
- Chapter 12 — Reading Financial Statements: Statements, Inventory, Depreciation and Ratiosp. 283
- Chapter 13 — Debt Instruments: Money Market, Corporate Bonds, Structured Products, Foreign Debt, Ratings and Convertiblesp. 296
- Chapter 14 — Bond Yields, Price Behavior, Accrued Interest and the Tax Treatment of Taxable Debtp. 312
Tomado del PDF que descargas, con la página en la que empieza cada uno — no escrito a mano aquí. Esta lista es la primera parte de 101 encabezados del archivo.
Lee un capítulo completo gratis
Un capítulo completo, tal como viene en el eBook. Desplázate en la ventana para leerlo aquí; sin descargas ni correo.
Lee el capítulo 22 aquí, sin salir de la página
The free chapter is Options, the hardest and highest-yield part of the Series 7, so you can judge the teaching exactly where the exam decides pass or fail.
The Series 7 asks you for three numbers on every strategy: maximum gain, maximum loss and breakeven. If you can produce them for the positions in this chapter, with the arithmetic, you have the option questions that account for a large share of the exam. All examples use standard 100-share contracts and ignore commissions. Premiums are per share; multiply by 100 for dollars.
Start with the four basic positions
| Position | Outlook | Maximum gain | Maximum loss | Breakeven |
|---|---|---|---|---|
| Long call | Bullish | Unlimited | Premium paid | Strike + premium |
| Short call (uncovered) | Neutral to bearish | Premium received | Unlimited | Strike + premium |
| Long put | Bearish | (Strike − premium) × 100: stock to zero | Premium paid | Strike − premium |
| Short put | Neutral to bullish | Premium received | (Strike − premium) × 100: stock to zero | Strike − premium |
Two reflexes make the rest easy. First, the breakeven for any single option is strike ± premium (plus for calls, minus for puts), whether you bought or sold it. Second, the buyer's maximum loss is the writer's maximum gain, and the reverse.
Covered call writing (and the covered put)
A covered call is long 100 shares plus a short call on the same shares. The stock covers the call: if the call is assigned, the customer delivers shares already owned.
The purpose is income and a small cushion against loss. The cost is that upside is capped at the strike.
Worked example. A customer buys 100 XYZ at 48 and sells one XYZ 50 call for 3.
| Item | Calculation | Result |
|---|---|---|
| Breakeven | Stock cost − premium = 48 − 3 | $45 |
| Maximum gain | (Strike − cost + premium) × 100 = (50 − 48 + 3) × 100 | $500 |
| Maximum loss | (Cost − premium) × 100 = (48 − 3) × 100 | $4,500 (stock goes to zero) |
If XYZ finishes at 52 the call is assigned: the customer sells at 50 and keeps the 3. The gain is $500, not the $700 the stock alone would have produced. If XYZ finishes at 47, the call expires, the customer keeps the $300, and the stock has lost $100: net +$200. Maximum gain occurs at any price from 50 up.
A covered call is considered a conservative strategy but not a risk-free one. The loss on the stock is cushioned only by the premium. The risk the exam wants named is opportunity cost: giving up gains above the strike.
A covered put is the mirror image: short 100 shares plus a short put. The short put is "covered" in the sense that if it is assigned, the customer buys the stock at the strike and uses it to close the short position. The short stock is unprotected on the upside, so the loss is unlimited if the stock rises. The gain is limited to the premium plus any gap between the short-sale price and the strike: maximum gain = premium + (short price − strike) × 100.
Example. Short 100 at 40, sell one 40 put at 2. Breakeven = 40 + 2 = 42. Maximum gain = $200 (the premium) if the stock falls: the put is assigned at 40, the customer buys 100 at 40 and uses them to close the short position, which was opened at 40, leaving only the premium. Maximum loss is unlimited above 42.
A cash-secured put (short put with cash set aside to buy the stock) is not a "covered put" in the exam's sense, but its numbers equal those of a short put.
Protective put and protective call (hedging with options)
A protective put is long stock plus long put. It sets a floor under a position: the customer can sell at the strike no matter how far the stock falls. Think of it as insurance: the premium is the price of the policy.
Example. A customer owns 100 XYZ bought at 60 and buys a 55 put for 2.50.
- Breakeven = 60 + 2.50 = 62.50.
- Maximum loss = (60 − 55 + 2.50) × 100 = $750, no matter how low the stock goes.
- Maximum gain: unlimited (stock rises, put expires).
Compare with a covered call: the covered call pays the customer premium and limits gains; the protective put costs the customer premium and limits losses.
A protective call is short stock plus long call. It caps the loss on a short sale. Example: short 100 at 40, buy a 45 call for 1.50. Breakeven = 40 − 1.50 = 38.50. Maximum loss = (45 − 40 + 1.50) × 100 = $650. Maximum gain = (40 − 1.50) × 100 = $3,850 if the stock goes to zero.
Hedging a portfolio with index options
Index puts hedge a diversified portfolio because the index moves with it. The number of contracts is:
Contracts = portfolio value ÷ (index level × multiplier), then adjusted for the portfolio's beta.
Illustration (hypothetical index level). A $1,000,000 portfolio that tracks the broad market, with a broad-based index at 5,000 and a $100 multiplier. Each contract covers 5,000 × 100 = $500,000 of index value, so 2 puts hedge the portfolio. If the portfolio's beta against the index is 1.2, the hedge ratio is 1,000,000 × 1.2 ÷ 500,000 = 2.4, or about 2 or 3 contracts. The hedge is imperfect (basis risk): the portfolio may fall by more or less than the index. Index options are cash-settled, which is convenient, and if the market rises the portfolio profits while the puts lose their premium.
Collars
A collar is long stock, long put (below the market), short call (above the market). The short call premium pays for all or part of the put. The customer gives up upside above the call strike in return for a floor under the put strike.
Example. A customer buys 100 XYZ at 50, buys one 45 put for 1.50, and sells one 55 call for 2.
- Net option cost = 1.50 − 2.00 = a 0.50 credit. Effective cost per share = 50 − 0.50 = 49.50.
- Maximum gain = 55 − 49.50 = 5.50, or $550.
- Maximum loss = 49.50 − 45 = 4.50, or $450.
- Breakeven = $49.50.
When the premiums are equal, the collar costs nothing: a "zero-cost" collar. Collars are used for concentrated stock positions where the customer wants protection without cash outlay. Note that a collar is a hedge, not a speculation: both gain and loss are capped.
Spreads
A spread is the purchase of one option and sale of another of the same type (both calls or both puts) on the same underlying stock. The classification:
| Type | What differs | Also called |
|---|---|---|
| Vertical | Different strikes, same expiration | Price spread |
| Horizontal | Same strike, different expirations | Calendar or time spread |
| Diagonal | Different strikes and different expirations | Combination of the above |
A debit spread costs money to open (the long option is the more expensive). A credit spread receives money (the short option is the more expensive). A trader with a debit spread wants the spread to widen; a trader with a credit spread wants it to narrow.
For a vertical spread, maximum gain + maximum loss = difference between the strikes (× 100). Use this to check your work.
Debit spreads
Bull call spread. Buy the lower-strike call, sell the higher-strike call. Example: buy 50 call at 6, sell 55 call at 3.
- Net debit = 6 − 3 = 3, or $300. This is the maximum loss, reached if the stock is at or below 50 at expiration.
- Maximum gain = (55 − 50 − 3) × 100 = $200, reached at or above 55.
- Breakeven = 50 + 3 = 53.
- Check: 300 + 200 = 500 = 5 points × 100.
Bear put spread. Buy the higher-strike put, sell the lower-strike put. Example: buy 55 put at 4, sell 50 put at 1.50.
- Net debit = 2.50, or $250 (maximum loss, at or above 55).
- Maximum gain = (55 − 50 − 2.50) × 100 = $250, at or below 50.
- Breakeven = 55 − 2.50 = 52.50.
Credit spreads
Bear call spread. Sell the lower-strike call, buy the higher-strike call. Example: sell 50 call at 5, buy 55 call at 2.
- Net credit = 3, or $300 (maximum gain, if the stock is at or below 50).
- Maximum loss = (55 − 50 − 3) × 100 = $200, at or above 55.
- Breakeven = 50 + 3 = 53.
Bull put spread. Sell the higher-strike put, buy the lower-strike put. Example: sell 50 put at 3, buy 45 put at 1.
- Net credit = 2, or $200 (maximum gain, stock at or above 50).
- Maximum loss = (50 − 45 − 2) × 100 = $300, at or below 45.
- Breakeven = 50 − 2 = 48.
A quick way to classify. For calls, buying the lower strike is a debit and bullish; selling the lower strike is a credit and bearish. For puts, buying the higher strike is a debit and bearish; selling the higher strike is a credit and bullish. The exam tests this by giving you positions and asking whether the spread is a debit or credit and bullish or bearish.
Margin. A debit spread requires the customer to pay the net debit in full. A credit spread requires a deposit of the difference between the strikes less the credit, which equals the maximum loss: the bear call spread above needs ($500 − $300) = $200 in addition to the credit received.
Calendar and diagonal spreads
A calendar (time or horizontal) spread sells a near-term option and buys a longer-dated option of the same strike. It profits from the faster decay of the near-term option. It is a debit spread because the longer-dated option is worth more.
Example. Sell the March 50 call at 1.50, buy the June 50 call at 3.50. Net debit = 2.00 ($200), which is the maximum loss for the position at the time the near-term option expires. The best result occurs if the stock is near 50 when the March option expires: the short option expires worthless and the long June call retains time value.
A diagonal spread changes both strike and month (for example, buy the June 50 call, sell the March 55 call). It combines a vertical and a calendar view and is a debit or credit depending on the prices.
Straddles, strangles and combinations
A straddle is a call and a put on the same stock with the same strike and same expiration. A strangle is a call and a put with the same expiration but different strikes, usually both out of the money. A combination is any other call-and-put pair, including different strikes and/or different expirations.
A long position is a bet on volatility: the customer profits if the stock moves a lot in either direction. A short position is a bet on little movement.
Long straddle. Buy a 50 call at 3 and a 50 put at 2.50.
- Total premium = 5.50, or $550: the maximum loss, at exactly 50 at expiration.
- Upper breakeven = 50 + 5.50 = 55.50; lower breakeven = 50 − 5.50 = 44.50.
- Maximum gain: unlimited on the upside; (50 − 5.50) × 100 = $4,450 on the downside.
Short straddle. Sell both: maximum gain $550 (stock at 50), unlimited loss on the upside, and loss down to (50 − 5.50) × 100 = $4,450 on the downside. The breakevens are the same 44.50 and 55.50.
Long strangle. Buy a 55 call at 1.50 and a 45 put at 1.00.
- Total premium = 2.50, or $250 (maximum loss, anywhere between 45 and 55).
- Upper breakeven = 55 + 2.50 = 57.50; lower breakeven = 45 − 2.50 = 42.50.
A strangle costs less than a straddle but needs a larger move to profit. A short strangle collects less, but has a wider zone where the writer keeps the whole premium; the risk is large moves either way and, on the upside, unlimited.
For a long straddle, strangle or combination: breakeven points = strikes ± total premium. For a short one, the same points apply, but they bound the profit zone instead of the loss zone.
Preguntas frecuentes
¿Cómo lo recibo?
Paga y la descarga aparece en esta página al instante. Los enlaces también se te envían por correo. No hace falta cuenta.
¿Y si no es para mí?
Escríbenos dentro de 14 días para un reembolso total, sin preguntas.
¿Va a desaparecer la práctica gratis?
No. Todas las preguntas, el simulacro cronometrado y los capítulos gratis del sitio siguen gratis. Este libro es la mitad de estudio, no una valla alrededor de lo gratuito.
Más preguntas (1)
¿Puedo leerlo en el móvil?
Sí — el EPUB es para móviles y e-readers, el PDF para imprimir y marcar. Recibes ambos.
¿Por qué comprar el libro si la práctica es gratis?
Nuestras preguntas de práctica y el simulacro cronometrado siguen gratis: nada del sitio se esconde tras este libro. El libro de $24.99 es la mitad de estudio: el material en sí, explicado en orden, en un archivo tuyo.
- Enseñanza sistemática — cada sección del examen explicada capítulo a capítulo, de principio a fin, no solo preguntas
- Imprímelo y márcalo — un PDF listo para papel que puedes resaltar, anotar y llevar a tu mesa de estudio
- Estudia en cualquier lugar, sin conexión — EPUB en tu teléfono o e-reader; sin wifi, sin pestañas
- Todo en un solo lugar — los capítulos y las preguntas de práctica en un archivo
- Tuyo de por vida — pago único de $24.99, descarga instantánea, sin suscripción
Los detalles
- Verificado con la fuente oficial(FINRA content outline / SEC, FINRA, MSRB and OCC rules)
- 1,176 preguntas de práctica gratis
Un Series 7 exam prep course cuesta $300–$900. Este libro enseña el mismo examen — las mismas reglas, verificadas a los estándares actuales — por un pago único de $24.99 que conservas de por vida.
Compra única, acceso de por vida a la descarga. El eBook es la guía completa de Series 7 en PDF y EPUB. Resumen educativo, no asesoría profesional ni legal — confirma siempre las reglas vigentes con la fuente oficial. Última actualización: October 2026.