学习指南 · 2026 版
Series 6 — Funds & Variable Contracts Study Guide (2026)
Seventeen chapters written to FINRA's Series 6 content outline.
- 篇幅
- 788 页(讲解 287 页 + 题库)
- 书内练习题
- 1,096
- PrepPass 在线计时模考
- 50 题 · 90 分钟
- 考试事实核对与文件更新
- 2026年10月
- 交付
- PDF + EPUB · 英文 · 即时下载
购买前请阅读: This is an independent study aid, not affiliated with or endorsed by FINRA, the SEC, MSRB, or any test-delivery vendor (including Prometric).
阅读本声明的其余部分
Securities rules change and many dollar figures (contribution limits, phase-outs) are indexed or were recently updated; every rule and figure here is written to the current level, but confirm the current-year figures before you rely on any of them.
关于本书
Seventeen chapters written to FINRA's Series 6 content outline: mutual funds, variable annuities and life, 529s and the 1940 Act, with the pricing and suitability math worked step by step.
考试费:每次 $100,缴给 FINRA。补考要再交一次。本指南:$24.99,一次买断。
考试事实、适合谁与变化
关于这场考试本身
| 主管机构 | Financial Industry Regulatory Authority (FINRA) 来源: FINRA — Series 6 – Investment Company and Variable Contracts Products Representative Exam (IR) |
|---|---|
| 题目数量 | 55 道题 (50 道计分,5 道不计分预试题) |
| 考试时限 | 90 分钟 |
| 及格标准 | FINRA (scale range) 未公布 我们查阅但未找到该数据的来源: FINRA — Series 6 – Investment Company and Variable Contracts Products Representative Exam (IR) |
| 费用 |
来源: FINRA — Series 6 – Investment Company and Variable Contracts Products Representative Exam (IR) |
| 考试语言 | FINRA 未公布 我们查阅但未找到该数据的来源: FINRA — Series 6 – Investment Company and Variable Contracts Products Representative Exam (IR) |
翻开这本书看看
三页真实内页,直接从你将下载的 PDF 渲染而来 —— 依次是一页速查、一页讲解、一道带解析的例题。没有任何一页是为了好看而重画的。
- 速查页Appendix — Question Bank 1,096 practice questions with answers and explanations · PDF 第 722 页
一页可以随时翻回来的内容:把数字、期限或术语集中在一处。
- 怎么讲Appendix — Question Bank 1,096 practice questions with answers and explanations · PDF 第 731 页
讲解页:用文字把知识讲清楚,顺序与考试考查的顺序一致。
- 一道题的完整解析Chapter 1 — Bringing Securities to Market: Registration, Prospectuses and Exemptions · PDF 第 22 页
一道练习题,连同答案和背后的推理 —— 不只是一个答案键。
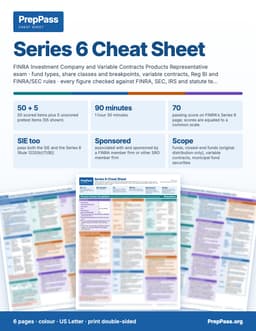
两周内就要考试?
这本指南是系统讲解,要花几周读。如果两周内就考,可打印的彩色速查表是另一款产品:考试涉及的关键数字,按章节排好。
6 页 · US Letter · 可打印 PDF · 永久保存
包含什么,不包含什么
包含
- Seventeen chapters organised by topic, from new issues and communications to complaints and arbitration, with a table mapping them to FINRA's outline
- Every chapter closes with a key-facts box and a named exam-traps list
不包含
- 不寄送纸质书 —— 这是一份你下载后可自行打印的文件
- 购书不含视频课程、讲师或一对一辅导 —— 站上的免费视频是另一回事
完整的包含项与不包含项
包含
- Mutual-fund pricing worked step by step: NAV, public offering price, sales charges, breakpoints, letters of intent and rights of accumulation
- Variable annuities and variable life: the separate account, accumulation and annuity units, the assumed interest rate and 1035 exchanges
- Dated 2026 changes called out: the $300 gift limit, the new intraday margin standards, the ABLE account limit, FINRA Rule 3290
- 287 pages of teaching, then a question bank of 1096 practice questions, grouped by topic, with answers and explanations
- PDF (print & tab it) + EPUB (phone / e-reader)
不包含
- 不含考试报名费与考点费用,这些仍需向官方机构缴纳
目录
查看 19 个部分及各部分起始页
- Chapter 1 — Bringing Securities to Market: Registration, Prospectuses and Exemptions第 11 页
- Chapter 2 — Communications with the Public: Advertising, Sales Literature, Seminars and Gifts第 26 页
- Chapter 3 — The Investment Company Act of 1940: How a Fund Is Built and Policed第 42 页
- Chapter 4 — Mutual Funds: Types, Structure, Objectives and Fees第 58 页
- Chapter 5 — NAV, Offering Price and Sales Charges: Pricing and Breakpoint Math第 73 页
- Chapter 6 — Redemption, Exchanges, Withdrawal Plans, and How Funds and Shareholders Are Taxed第 86 页
- Chapter 7 — Closed-End Funds, Unit Investment Trusts, ETFs, Other Packaged Products and Government Pools第 101 页
- Chapter 8 — Variable Annuities第 116 页
- Chapter 9 — Variable Life Insurance第 132 页
- Chapter 10 — Municipal Fund Securities, 529 Plans and ABLE Accounts第 140 页
- Chapter 11 — Retirement Plans, Employer Plans, ERISA, Wealth Events, and Gift and Estate Tax第 154 页
- Chapter 12 — Opening Accounts, Authorizations, Privacy and Supervision第 172 页
- Part 1. Privacy notices and opt-out (17 CFR 248.4 to 248.15):第 189 页
- Chapter 13 — Suitability, Regulation Best Interest and Portfolio Analysis第 195 页
- Chapter 14 — Securities Products, Tax Rules and Financial Statements第 221 页
- Chapter 15 — Records, Confirmations, Statements and Account Transfers第 244 页
- Chapter 16 — Orders, Execution, Settlement and Margin第 259 页
- Chapter 17 — Errors, Complaints, Arbitration and the Regulatory Process第 277 页
- Appendix — Question Bank 1,096 practice questions with answers and explanations第 288 页
取自你将下载的那份 PDF,并标明各章起始页 —— 不是在此手工录入的。
免费读完整一章
完整的一章,与电子书正文一字不差。直接在此窗口滚动阅读;无需下载,无需邮箱。
在本页直接阅读第 14 章
我们没有拿轻松的绪论充数 —— 免费章节直接翻到书里最见功力的部分,让你在考试真正难的地方检验这本书讲得好不好。
The Series 6 outline lists equities, debt, options, Treasuries, agency securities and money market instruments under the product knowledge section, and it lists the tax and financial statement topics beside them. A representative who cannot explain these cannot make a suitable recommendation, so this chapter works through each product, then the tax rules that apply to gains and losses, then the financial statements.
14.1 Equity securities
Common stock
Common stock is ownership. Holders have residual claims on assets and earnings, voting rights (statutory or cumulative), preemptive rights if the charter grants them, the right to inspect the books, and a share of dividends if declared. They are paid last in a liquidation, after creditors and preferred holders. Dividends are not guaranteed; the board declares them.
| Term | Meaning |
|---|---|
| Authorized, issued, outstanding, treasury | Authorized is the maximum the charter allows; issued has been sold; outstanding = issued less treasury; treasury stock is repurchased stock that does not vote or receive dividends |
| Statutory voting | One vote per share per director seat, no cumulating |
| Cumulative voting | Shares x number of seats can be put all on one candidate, helping minority holders |
| Stock split | More shares, lower price; no change in total value or the company's equity |
| Reverse split | Fewer shares, higher price |
| Stock dividend | Additional shares paid to holders; same total value |
Example 1. Splits. A holder owns 300 shares at $90 ($27,000). In a 3-for-2 split the holder has 300 x 3/2 = 450 shares at $90 x 2/3 = $60 ($27,000). In a 1-for-5 reverse split the holder has 300 / 5 = 60 shares at $90 x 5 = $450 ($27,000).
Example 2. Dividend yield and the ex-date. A stock pays $0.60 each quarter and trades at $48. Annual dividend $2.40; yield = 2.40 / 48 = 5.0%. Under Rule 11140, the stock goes ex-dividend on the record date under the T+1 settlement cycle (for ordinary dividends below 25% of the stock's value); a buyer who purchases on or after the ex-date does not receive the dividend. Chapter 16 covers the dividend calendar.
Preferred stock
Preferred has a fixed dividend, ranks ahead of common in dividends and liquidation, usually has no vote, and trades mainly on yield and the issuer's credit.
| Type | Feature |
|---|---|
| Cumulative | Missed dividends accumulate as "arrears" and must be paid before any common dividend |
| Non-cumulative | Missed dividends are lost |
| Participating | Shares in extra earnings beyond the stated dividend |
| Convertible | Convertible into common at a set ratio |
| Callable | The issuer can redeem, usually at a premium |
| Putable | The holder can force redemption |
| Adjustable-rate | Dividend resets with a reference rate |
Preferred prices move opposite to interest rates, as bond prices do. The par value is typically $25 or $100.
Example 3. Preferred yield. A $100 par, 5% preferred pays $5 a year. At a market price of $80, current yield = 5 / 80 = 6.25%. If the price rises to $100, the yield is 5.00%.
Example 4. Convertible parity. A convertible bond with $1,000 par is convertible at $40 a share: conversion ratio = $1,000 / $40 = 25 shares. If the stock trades at $45, parity (conversion value) = 25 x $45 = $1,125. The bond will trade at or above parity. If the bond trades at $1,150 the premium over parity is $25.
ADRs, rights and warrants
- American depositary receipts (ADRs) are receipts issued by a US depositary bank for shares of a foreign company held by a custodian abroad. They trade in dollars, pay dividends in dollars, and carry currency risk and foreign-market risk. Sponsored ADRs involve the issuer; unsponsored do not. Foreign withholding tax may apply on dividends.
- Rights are short-term (usually 30 to 60 days) offers to existing holders to buy new shares at a subscription price below market, in proportion to existing holdings, protecting preemptive rights. They are issued on a rights offering.
- Warrants are long-term (years, sometimes perpetual) options to buy stock at a fixed price above the market price at issue. They are often attached to a bond or preferred issue as a "sweetener".
Example 5. Value of a right. The stock trades at $50 cum-rights. The subscription price is $40, and 4 rights plus $40 buy one share. Value of a right while the stock still carries the right = (50 - 40) / (4 + 1) = $2.00. After the stock goes ex-rights, it should trade near $48. Then the value of one right = (48 - 40) / 4 = $2.00. The holder who sells the rights gets the same economic value as exercising them.
14.2 Debt securities
A bond is a loan. The issuer promises to pay interest (the coupon) and return the principal (par, face) at maturity. Bonds are quoted as a percentage of par, so a quote of 98 is $980 per $1,000 bond.
| Term | Meaning |
|---|---|
| Coupon rate | Annual interest as a percentage of par |
| Current yield | Annual interest / current market price |
| Yield to maturity (YTM) | The annual return if held to maturity, including the gain or loss against par and reinvestment of coupons at the same rate |
| Yield to call (YTC) | The same, assuming the bond is called on the first call date |
| Nominal yield | Coupon yield |
| Discount / par / premium | Price below / equal / above par |
The relationships to memorize:
- Price and yield move in opposite directions.
- Premium bond: coupon rate > current yield > YTM (and YTC lower still if the call price is below the bond's price).
- Discount bond: coupon rate < current yield < YTM.
- Par bond: coupon = current yield = YTM.
- Longer maturity and lower coupon mean more price sensitivity (greater duration) for a given rate change.
- Callable bonds: the investor is hurt when rates fall because the bond is called at a time of lower rates (call risk and reinvestment risk), so callable bonds pay more.
- Basis point: 0.01%. A move of 50 basis points is 0.50%.
Example 6. Current yield and yield to maturity. A 6% coupon, 10-year bond with $1,000 par trades at 95 ($950).
- Annual interest = 6% x $1,000 = $60.
- Current yield = 60 / 950 = 6.32%.
- Approximate YTM = (60 + (1,000 - 950) / 10) / ((1,000 + 950) / 2) = (60 + 5) / 975 = 6.67%. The exact YTM, solved by present value, is 6.70%. The exam asks for the order (coupon 6.00% < current yield 6.32% < YTM 6.70%), not for the exact solve.
Example 7. Accrued interest. The bond above is a corporate bond with a 6% coupon paid January 1 and July 1, and the trade settles April 15. Corporate and municipal bonds count interest on a 30/360 basis (30-day months, 360-day year): January 1 to April 15 is 3 x 30 + 14 = 104 days. Accrued interest = $1,000 x 0.06 x 104 / 360 = $17.33 per bond. The buyer pays the price plus accrued interest, and receives the full coupon on July 1. Treasury notes and bonds use actual days/actual days. A bond that trades "flat" (bonds in default, income bonds) has no accrued interest added.
Types of corporate bonds.
| Type | Feature |
|---|---|
| Secured / mortgage / equipment trust | Backed by specific assets |
| Debenture | Unsecured; backed by the issuer's credit |
| Subordinated debenture | Ranks below other debt |
| Convertible | Convertible to stock |
| Zero-coupon | Sold at a deep discount; no interest paid; accretion is taxable each year as phantom income |
| Income / adjustment bond | Pays interest only if earned |
| Floating rate | Coupon resets |
| Callable / puttable / extendable | Call and put features |
| High yield ("junk") | Rated below BBB-/Baa3 |
| Investment grade | BBB-/Baa3 and above |
Seniority in liquidation: secured creditors, then unsecured creditors (debentures), then subordinated debt, then preferred stock, then common stock. Bondholders are creditors, with a claim in bankruptcy, while stockholders are owners.
Municipal bonds were covered in Chapter 1 (official statements, and the issuance process) and Chapter 10 (municipal fund securities). The key tax point: interest on most municipal bonds is exempt from federal income tax and, if the investor lives in the issuing state, from state tax. General obligation (GO) bonds are backed by taxing power; revenue bonds by the revenue of the project. Municipal bond interest is tax-exempt, but a gain on sale is taxable as a capital gain.
Bond ratings. Moody's Aaa/Aa/A/Baa are investment grade; Ba and below are speculative. S&P and Fitch use AAA/AA/A/BBB. A rating change moves price.
14.3 Options
An option is a contract giving the holder the right, but not the obligation, to buy (call) or sell (put) the underlying at the strike price until expiration. A standard equity option covers 100 shares. Standardized listed options are issued and guaranteed by the Options Clearing Corporation (OCC). The buyer pays a premium to the seller (writer).
| Position | Market view | Maximum gain | Maximum loss | Breakeven |
|---|---|---|---|---|
| Long call | Bullish | Unlimited | Premium paid | Strike + premium |
| Short (naked) call | Neutral to bearish | Premium received | Unlimited | Strike + premium |
| Long put | Bearish | Strike - premium (stock goes to zero) | Premium paid | Strike - premium |
| Short put | Neutral to bullish | Premium received | Strike - premium | Strike - premium |
In, at and out of the money. A call is in the money if the stock is above the strike; a put is in the money if the stock is below the strike. Intrinsic value = the amount in the money (zero if not). Time value (extrinsic value) = premium - intrinsic value; it goes to zero at expiration.
Example 8. Long call. A customer buys 2 contracts of an XYZ 50 call at 3.00.
- Cost = 2 x 100 x $3 = $600; this is the maximum loss.
- Breakeven = $50 + $3 = $53.
- If XYZ is $58 at expiration the intrinsic value is $8, so the profit is (8 - 3) x 200 = $1,000.
- If XYZ is $50 or lower at expiration the options expire worthless and the loss is $600.
Example 9. Long put. Buy a 50 put at 3.00. Breakeven = 50 - 3 = $47. The maximum gain (stock to zero) = (50 - 3) x 100 = $4,700 per contract; the maximum loss is $300.
Hedging and income strategies.
| Strategy | Construction | Purpose | Result |
|---|---|---|---|
| Covered call | Own the stock, sell a call | Income; limits upside | Breakeven = stock cost - premium; gain capped at strike + premium - cost |
| Protective put | Own the stock, buy a put | Insurance for a long position | Loss limited to cost + premium - strike; breakeven = stock cost + premium |
| Married put | Buy stock and put together | Same | Same |
| Collar | Own the stock, buy a put, sell a call | Protect downside, give up upside; may be low-cost | |
| Long straddle | Buy call and put, same strike and expiry | Profits from a big move either way | Two breakevens: strike plus total premium and strike minus total premium |
| Spread | Buy and sell options of the same type | Defined risk and reward |
Example 10. Covered call. An investor buys 100 XYZ at $48 and sells a 50 call for $2.
- Breakeven = 48 - 2 = $46.
- Maximum gain = (50 + 2 - 48) x 100 = $400 (if the stock is called away at 50).
- Maximum loss = (48 - 2) x 100 = $4,600 if the stock goes to zero.
Example 11. Straddle. Buy a 50 call at 3 and a 50 put at 2. Total premium $5. Breakevens: 50 + 5 = $55 and 50 - 5 = $45. The maximum loss is $500, at a stock price of exactly $50 at expiration.
Example 12. Bull call spread. Buy a 50 call at 5, sell a 60 call at 2. Net debit $3. Maximum loss = $300; maximum gain = (10 - 3) x 100 = $700; breakeven = 50 + 3 = $53. A debit spread has a maximum loss equal to the net debit.
Other rules. Options accounts require approval and the Options Disclosure Document, and approval by a Registered Options Principal or another principal the rule permits (Rule 2360(b)(16)); a suitability standard applies to each level. Exercise of a stock option settles in the standard stock cycle, which is one business day after exercise (OCC T+1 conversion, effective 2024-05-28). Index options settle in cash. LEAPS are long-dated options. Margin on options is in Chapter 16.
购买者常问的问题
怎么拿到?
付款后下载入口立即出现在本页,链接同时发到你的邮箱。无需注册账号。
不合适怎么办?
14 天内发邮件即可全额退款,无需理由。
免费练习会取消吗?
不会。站上的每一道练习题、计时模考和免费章节都继续免费。这本书是「学」的那一半,不是把免费部分围起来的门。
更多问题 (1)
能在手机上看吗?
可以 —— EPUB 适合手机和电子书阅读器,PDF 适合打印和贴标签,两种都给你。
练习免费,为什么还要买书?
我们的练习题和计时模考一直免费 —— 网站上的东西不会因为这本书而收起来。这本 $24.99 的书是「学」的那一半:知识本身,按顺序讲清楚,存成一份属于你的文件。
- 系统讲解 —— 每个考试部分按章节从头讲到尾,不只是题目
- 可打印可贴标签 —— 一份适合打印的 PDF,能划重点、做批注、带到书桌前
- 随处离线学 —— EPUB 放手机或电子书阅读器;不用 wifi,不用一堆浏览器标签
- 全在一处 —— 章节和练习题都在同一份文件里
- 永久归你 —— 一次 $24.99,即时下载,无订阅
详细信息
- 官方来源核验(FINRA content outline / SEC rules / Investment Company Act of 1940)
- 1,096 道免费练习题
Series 6 exam prep course 要 $150–$500。这本书讲的是同一门考试 —— 同样的规则、核对到最新标准 —— 只需一次性 $24.99,永久归你。
一次购买,永久下载访问。此电子书是完整的 Series 6 学习指南,含 PDF 与 EPUB。仅为教育性摘要,非专业或法律意见 —— 请始终以官方来源核实当前规定。最后更新:October 2026。