Study guide · 2026 Edition
Series 7 — General Securities Representative Study Guide (2026)
PrepPass's independent 2026 study guide for the Series 7 exam is 1,031 pages (528 teaching + question bank) with 1,176 practice questions and a full answer key, PDF + EPUB, $24.99 one-time; it is not affiliated with the exam provider. The book does not include PrepPass's separate online timed mock for this exam (125 questions, 225 minutes).
- Length
- 1,031 pages (528 teaching + question bank)
- Practice questions in the book
- 1,176
- PrepPass online timed mock
- 125 questions · 225 min
- Exam facts checked, file updated
- October 2026
- Delivery
- PDF + EPUB · English · instant download
Please read before you buy: This is an independent study aid, not affiliated with or endorsed by FINRA, the SEC, MSRB, the OCC, or any test-delivery vendor (including Prometric).
Read the rest of this notice
Securities rules change and many figures (contribution limits, gift limits) are indexed or were recently updated; confirm the current rules before you rely on any figure.
What is in the Series 7 study guide?
The real exam: General Securities Representative Qualification Examination (Series 7) — 130 questions (125 scored, 5 unscored pretest) · 225 minutes · Passing score: Not published by FINRA (scale range).
Thirty-three chapters written to FINRA's Series 7 content outline: options, margin, municipals, bonds and every product a representative recommends, with the math worked step by step.
Exam fee: $395 per attempt, paid to FINRA. A retake pays it again. This guide: $24.99, one time.
Exam facts, who it suits and what changed
About the exam itself
| Administering body | Financial Industry Regulatory Authority (FINRA) Source: FINRA — Series 7 – General Securities Representative Exam (GS) |
|---|---|
| Questions | 130 questions (125 scored, 5 unscored pretest) |
| Time limit | 225 minutes |
| Passing score | Not published by FINRA (scale range) What we read and found nothing in: FINRA — Series 7 – General Securities Representative Exam (GS) |
| Fees |
Source: FINRA — Series 7 – General Securities Representative Exam (GS) |
| Languages offered | Not published by FINRA What we read and found nothing in: FINRA — Series 7 – General Securities Representative Exam (GS) |
Look inside the book
Three real pages, rendered straight from the PDF you download — a reference page, a teaching page, and a worked question, always in that order. Nothing here was redrawn to look better.
- Quick referenceSection 7 — Government securities, CMOs and CDs · PDF page 29
A page you can turn back to: the numbers, deadlines or terms gathered in one place.
- How it's taughtChapter 8 — Margin Accounts and Margin Calculations · PDF page 240
An explanation page: the material taught in prose, in the order the exam tests it.
- A question, workedSection 1 — FINRA Rule 2210: the master rule for communications · PDF page 16
A practice question with its answer and the reasoning behind it — not just a key.
Exam inside two weeks?
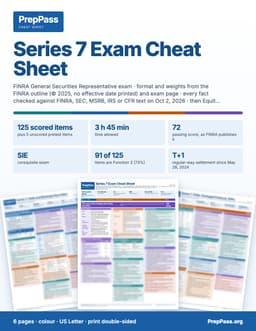
This guide is the teaching, read over weeks. If your exam is inside two weeks, the printable colour cheat sheet is the other product: the figures the exam turns on, laid out by section.
See the Series 7 cheat sheet PDF — $9.99 →
6 pages · US Letter · printable PDF · yours to keep
What's included — and what isn't
Included
- Thirty-three chapters organised by topic, with a table mapping them to FINRA's four outline functions; most of the book is the recommendation and product knowledge that is most of the exam
- Key-facts boxes and named exam-traps lists inside the chapters
Not included
- No printed copy is shipped — this is a file you download and can print yourself
- No video course, instructor or tutoring comes with the book — the free videos on the site are separate
Everything included, and everything that isn't
Included
- The options math worked step by step: breakeven, maximum gain and loss, spreads, straddles, hedging
- Margin and Regulation T, bond and municipal math, MSRB rules, packaged products and customer accounts
- Dated 2026 changes called out: the $300 gift limit, the new intraday margin standards, FINRA Rule 3290 (approved, no effective date yet)
- 528 pages of teaching, then a question bank of 1176 practice questions, grouped by topic, with answers and explanations
- PDF (print & tab it) + EPUB (phone / e-reader)
Not included
- Not your exam registration or the testing centre's fee, which you still pay to the official body
Contents
See 60 sections and the page each one starts on
- Chapter 1 — Communications, Contact Rules and Protecting Customers From Fraudp. 12
- Section 1 — FINRA Rule 2210: the master rule for communicationsp. 12
- Section 2 — Seminars, lectures and other group forumsp. 19
- Section 3 — Investment company and variable contract communicationsp. 21
- Section 4 — Options communications and the Options Disclosure Documentp. 23
- Section 5 — Municipal securities advertising: MSRB Rule G-21p. 26
- Section 6 — Research reports and quiet periodsp. 27
- Section 7 — Government securities, CMOs and CDsp. 29
- Section 9 — Identity theft (Regulation S-ID), AML red flags and senior investorsp. 35
- Chapter 2 — How New Securities Reach the Marketp. 39
- Section 2.1 The sequence of a registered corporate offeringp. 39
- Section 2.2 IPO communications and the anti- abuse rulesp. 47
- Section 2.3 Underwriters, syndicates and the spreadp. 51
- Section 2.4 Municipal primary offeringsp. 56
- Section 2.5 Other statutes touching an offeringp. 60
- Section 2.6 FINRA rules for offerings and firm arrangementsp. 63
- Section 2.7 — Exempt Offerings, Private Placements and Resalesp. 66
- Chapter 3 — Opening and Maintaining Customer Accountsp. 83
- Section 3.1 — Account types: day trading, prime brokerage, DVP/RVP, advisoryp. 83
- Section 3.2 — Account registration typesp. 87
- Section 3.3 — Opening an account: FINRA Rule 4512 and the new account formp. 91
- Section 3.4 — Retirement plans: IRAsp. 94
- Section 3.5 — Employer plans, ERISA, and equity compensationp. 98
- Section 3.6 — Education savings: 529 plans and Coverdell ESAsp. 104
- Section 3.7 — Wealth events, decedent accounts, and changes in registrationp. 107
- Section 3.8 — Customer screening: CIP, KYC, residency, insiders and industry employeesp. 109
- Section 3.9 — Privacy and information security: Regulation S-Pp. 113
- Section 3.10 — Authority to act: POA, trading authorization, discretion, entity documentsp. 116
- Section 3.11 — Putting it together: the account- opening sequencep. 119
- Chapter 4 — Knowing the Customer, Recommending, and Supervising the Accountp. 120
- Section 1 — The essential facts about every customerp. 120
- Section 2 — The financial factors and how each steers a recommendationp. 123
- Section 3 — Investment objectivesp. 128
- Section 4 — Suitability under Rule 2111, and what Reg BI replacedp. 129
- Section 5 — Strategies, “hold” recommendations, and verifying accreditation and sophisticationp. 132
- Section 6 — Regulation Best Interest, Form CRS, and Rule 2214p. 135
- Section 7 — Principal review, approvals and documentationp. 141
- Section 8 — Receipt, delivery and safeguarding of cash, checks and securitiesp. 144
- Section 9 — Refusing, restricting and closing accountsp. 148
- Chapter 5 — Trading, Orders and Market Structurep. 153
- Section 1 — Taking the order: solicited, unsolicited, and the order ticketp. 153
- Section 2 — Quotes: what a price on the screen meansp. 156
- Section 3 — Basic order types, and what triggers whatp. 158
- Section 4 — Special orders and instructions Instruction What it doesp. 162
- Section 5 — Short salesp. 164
- Section 6 — Securities lending, hard-to-borrow stocks, and failsp. 167
- Section 7 — Best execution, interpositioning and order handlingp. 169
- Section 8 — Execution mechanics: priority, precedence, crossing, auctionsp. 171
- Section 9 — Market makers, principal vs agency, riskless principal, and markupsp. 173
- Section 10 — Halts, limit up-limit down, and circuit breakersp. 176
- Section 11 — Alternative trading systems, OTC quotations, and automated executionp. 179
- Chapter 6 — Delivery, Settlement and Trade Reportingp. 182
- Chapter 7 — Errors, Complaints, Disputes and Disciplinep. 196
- Chapter 8 — Margin Accounts and Margin Calculationsp. 208
- Chapter 9 — Conduct, Registration, Customer Protection and the Tax and Economic Backdropp. 237
- Chapter 10 — Matching Securities to the Customer, and Portfolio Theoryp. 266
- Chapter 11 — Annual Reports, Corporate Actions and Tender- Offer Informationp. 274
- Chapter 12 — Reading Financial Statements: Statements, Inventory, Depreciation and Ratiosp. 283
- Chapter 13 — Debt Instruments: Money Market, Corporate Bonds, Structured Products, Foreign Debt, Ratings and Convertiblesp. 296
- Chapter 14 — Bond Yields, Price Behavior, Accrued Interest and the Tax Treatment of Taxable Debtp. 312
Taken from the PDF you download, with the page each one starts on — not typed here. This list is the first part of 101 headings in the file.
Read a chapter free, in full
One complete chapter, exactly as it ships in the eBook. Scroll the window to read it right here; no download, no email.
Read chapter 22 here, without leaving the page
The free chapter is Options, the hardest and highest-yield part of the Series 7, so you can judge the teaching exactly where the exam decides pass or fail.
The Series 7 asks you for three numbers on every strategy: maximum gain, maximum loss and breakeven. If you can produce them for the positions in this chapter, with the arithmetic, you have the option questions that account for a large share of the exam. All examples use standard 100-share contracts and ignore commissions. Premiums are per share; multiply by 100 for dollars.
Start with the four basic positions
| Position | Outlook | Maximum gain | Maximum loss | Breakeven |
|---|---|---|---|---|
| Long call | Bullish | Unlimited | Premium paid | Strike + premium |
| Short call (uncovered) | Neutral to bearish | Premium received | Unlimited | Strike + premium |
| Long put | Bearish | (Strike − premium) × 100: stock to zero | Premium paid | Strike − premium |
| Short put | Neutral to bullish | Premium received | (Strike − premium) × 100: stock to zero | Strike − premium |
Two reflexes make the rest easy. First, the breakeven for any single option is strike ± premium (plus for calls, minus for puts), whether you bought or sold it. Second, the buyer's maximum loss is the writer's maximum gain, and the reverse.
Covered call writing (and the covered put)
A covered call is long 100 shares plus a short call on the same shares. The stock covers the call: if the call is assigned, the customer delivers shares already owned.
The purpose is income and a small cushion against loss. The cost is that upside is capped at the strike.
Worked example. A customer buys 100 XYZ at 48 and sells one XYZ 50 call for 3.
| Item | Calculation | Result |
|---|---|---|
| Breakeven | Stock cost − premium = 48 − 3 | $45 |
| Maximum gain | (Strike − cost + premium) × 100 = (50 − 48 + 3) × 100 | $500 |
| Maximum loss | (Cost − premium) × 100 = (48 − 3) × 100 | $4,500 (stock goes to zero) |
If XYZ finishes at 52 the call is assigned: the customer sells at 50 and keeps the 3. The gain is $500, not the $700 the stock alone would have produced. If XYZ finishes at 47, the call expires, the customer keeps the $300, and the stock has lost $100: net +$200. Maximum gain occurs at any price from 50 up.
A covered call is considered a conservative strategy but not a risk-free one. The loss on the stock is cushioned only by the premium. The risk the exam wants named is opportunity cost: giving up gains above the strike.
A covered put is the mirror image: short 100 shares plus a short put. The short put is "covered" in the sense that if it is assigned, the customer buys the stock at the strike and uses it to close the short position. The short stock is unprotected on the upside, so the loss is unlimited if the stock rises. The gain is limited to the premium plus any gap between the short-sale price and the strike: maximum gain = premium + (short price − strike) × 100.
Example. Short 100 at 40, sell one 40 put at 2. Breakeven = 40 + 2 = 42. Maximum gain = $200 (the premium) if the stock falls: the put is assigned at 40, the customer buys 100 at 40 and uses them to close the short position, which was opened at 40, leaving only the premium. Maximum loss is unlimited above 42.
A cash-secured put (short put with cash set aside to buy the stock) is not a "covered put" in the exam's sense, but its numbers equal those of a short put.
Protective put and protective call (hedging with options)
A protective put is long stock plus long put. It sets a floor under a position: the customer can sell at the strike no matter how far the stock falls. Think of it as insurance: the premium is the price of the policy.
Example. A customer owns 100 XYZ bought at 60 and buys a 55 put for 2.50.
- Breakeven = 60 + 2.50 = 62.50.
- Maximum loss = (60 − 55 + 2.50) × 100 = $750, no matter how low the stock goes.
- Maximum gain: unlimited (stock rises, put expires).
Compare with a covered call: the covered call pays the customer premium and limits gains; the protective put costs the customer premium and limits losses.
A protective call is short stock plus long call. It caps the loss on a short sale. Example: short 100 at 40, buy a 45 call for 1.50. Breakeven = 40 − 1.50 = 38.50. Maximum loss = (45 − 40 + 1.50) × 100 = $650. Maximum gain = (40 − 1.50) × 100 = $3,850 if the stock goes to zero.
Hedging a portfolio with index options
Index puts hedge a diversified portfolio because the index moves with it. The number of contracts is:
Contracts = portfolio value ÷ (index level × multiplier), then adjusted for the portfolio's beta.
Illustration (hypothetical index level). A $1,000,000 portfolio that tracks the broad market, with a broad-based index at 5,000 and a $100 multiplier. Each contract covers 5,000 × 100 = $500,000 of index value, so 2 puts hedge the portfolio. If the portfolio's beta against the index is 1.2, the hedge ratio is 1,000,000 × 1.2 ÷ 500,000 = 2.4, or about 2 or 3 contracts. The hedge is imperfect (basis risk): the portfolio may fall by more or less than the index. Index options are cash-settled, which is convenient, and if the market rises the portfolio profits while the puts lose their premium.
Collars
A collar is long stock, long put (below the market), short call (above the market). The short call premium pays for all or part of the put. The customer gives up upside above the call strike in return for a floor under the put strike.
Example. A customer buys 100 XYZ at 50, buys one 45 put for 1.50, and sells one 55 call for 2.
- Net option cost = 1.50 − 2.00 = a 0.50 credit. Effective cost per share = 50 − 0.50 = 49.50.
- Maximum gain = 55 − 49.50 = 5.50, or $550.
- Maximum loss = 49.50 − 45 = 4.50, or $450.
- Breakeven = $49.50.
When the premiums are equal, the collar costs nothing: a "zero-cost" collar. Collars are used for concentrated stock positions where the customer wants protection without cash outlay. Note that a collar is a hedge, not a speculation: both gain and loss are capped.
Spreads
A spread is the purchase of one option and sale of another of the same type (both calls or both puts) on the same underlying stock. The classification:
| Type | What differs | Also called |
|---|---|---|
| Vertical | Different strikes, same expiration | Price spread |
| Horizontal | Same strike, different expirations | Calendar or time spread |
| Diagonal | Different strikes and different expirations | Combination of the above |
A debit spread costs money to open (the long option is the more expensive). A credit spread receives money (the short option is the more expensive). A trader with a debit spread wants the spread to widen; a trader with a credit spread wants it to narrow.
For a vertical spread, maximum gain + maximum loss = difference between the strikes (× 100). Use this to check your work.
Debit spreads
Bull call spread. Buy the lower-strike call, sell the higher-strike call. Example: buy 50 call at 6, sell 55 call at 3.
- Net debit = 6 − 3 = 3, or $300. This is the maximum loss, reached if the stock is at or below 50 at expiration.
- Maximum gain = (55 − 50 − 3) × 100 = $200, reached at or above 55.
- Breakeven = 50 + 3 = 53.
- Check: 300 + 200 = 500 = 5 points × 100.
Bear put spread. Buy the higher-strike put, sell the lower-strike put. Example: buy 55 put at 4, sell 50 put at 1.50.
- Net debit = 2.50, or $250 (maximum loss, at or above 55).
- Maximum gain = (55 − 50 − 2.50) × 100 = $250, at or below 50.
- Breakeven = 55 − 2.50 = 52.50.
Credit spreads
Bear call spread. Sell the lower-strike call, buy the higher-strike call. Example: sell 50 call at 5, buy 55 call at 2.
- Net credit = 3, or $300 (maximum gain, if the stock is at or below 50).
- Maximum loss = (55 − 50 − 3) × 100 = $200, at or above 55.
- Breakeven = 50 + 3 = 53.
Bull put spread. Sell the higher-strike put, buy the lower-strike put. Example: sell 50 put at 3, buy 45 put at 1.
- Net credit = 2, or $200 (maximum gain, stock at or above 50).
- Maximum loss = (50 − 45 − 2) × 100 = $300, at or below 45.
- Breakeven = 50 − 2 = 48.
A quick way to classify. For calls, buying the lower strike is a debit and bullish; selling the lower strike is a credit and bearish. For puts, buying the higher strike is a debit and bearish; selling the higher strike is a credit and bullish. The exam tests this by giving you positions and asking whether the spread is a debit or credit and bullish or bearish.
Margin. A debit spread requires the customer to pay the net debit in full. A credit spread requires a deposit of the difference between the strikes less the credit, which equals the maximum loss: the bear call spread above needs ($500 − $300) = $200 in addition to the credit received.
Calendar and diagonal spreads
A calendar (time or horizontal) spread sells a near-term option and buys a longer-dated option of the same strike. It profits from the faster decay of the near-term option. It is a debit spread because the longer-dated option is worth more.
Example. Sell the March 50 call at 1.50, buy the June 50 call at 3.50. Net debit = 2.00 ($200), which is the maximum loss for the position at the time the near-term option expires. The best result occurs if the stock is near 50 when the March option expires: the short option expires worthless and the long June call retains time value.
A diagonal spread changes both strike and month (for example, buy the June 50 call, sell the March 55 call). It combines a vertical and a calendar view and is a debit or credit depending on the prices.
Straddles, strangles and combinations
A straddle is a call and a put on the same stock with the same strike and same expiration. A strangle is a call and a put with the same expiration but different strikes, usually both out of the money. A combination is any other call-and-put pair, including different strikes and/or different expirations.
A long position is a bet on volatility: the customer profits if the stock moves a lot in either direction. A short position is a bet on little movement.
Long straddle. Buy a 50 call at 3 and a 50 put at 2.50.
- Total premium = 5.50, or $550: the maximum loss, at exactly 50 at expiration.
- Upper breakeven = 50 + 5.50 = 55.50; lower breakeven = 50 − 5.50 = 44.50.
- Maximum gain: unlimited on the upside; (50 − 5.50) × 100 = $4,450 on the downside.
Short straddle. Sell both: maximum gain $550 (stock at 50), unlimited loss on the upside, and loss down to (50 − 5.50) × 100 = $4,450 on the downside. The breakevens are the same 44.50 and 55.50.
Long strangle. Buy a 55 call at 1.50 and a 45 put at 1.00.
- Total premium = 2.50, or $250 (maximum loss, anywhere between 45 and 55).
- Upper breakeven = 55 + 2.50 = 57.50; lower breakeven = 45 − 2.50 = 42.50.
A strangle costs less than a straddle but needs a larger move to profit. A short strangle collects less, but has a wider zone where the writer keeps the whole premium; the risk is large moves either way and, on the upside, unlimited.
For a long straddle, strangle or combination: breakeven points = strikes ± total premium. For a short one, the same points apply, but they bound the profit zone instead of the loss zone.
Questions buyers ask
How do I get it?
Pay, and the download appears on this page straight away. The links are also emailed to you. No account is required.
What if it isn't for me?
Email us within 14 days for a full refund, no questions asked.
Is the free practice going away?
No. Every practice question, the timed mock and the free chapters on this site stay free. This book is the studying half, not a gate around the free half.
More questions (16)
Can I read it on my phone?
Yes — the EPUB is for phones and e-readers, the PDF is for printing and tabbing. You get both.
Is a study guide enough for the Series 7 exam, or do I need a course?
A book is exam review: it does not replace any education, training or experience Financial Industry Regulatory Authority (FINRA) requires before you may sit the exam, so check those requirements first. For the exam content itself, this guide teaches the material chapter by chapter in 528 pages, then prints 1,176 practice questions with answers and explanations, grouped by topic. A prep course adds live instruction and a set schedule; whether you need one beyond any required education is your call.
What is the cheapest way to prepare for the Series 7 exam?
Start with what costs nothing: 1,176 practice questions on PrepPass, with explanations and no signup. If you want it taught in one file you keep, the full study guide is $24.99 once; the printable cheat sheet for the last days is $9.99. No subscription on any of them.
Who administers the General Securities Representative Qualification Examination (Series 7)?
Financial Industry Regulatory Authority (FINRA). The SIE exam is a corequisite: candidates must pass both the SIE and the Series 7 to obtain the General Securities Representative registration.
How many questions are on the General Securities Representative Qualification Examination (Series 7)?
130 questions (125 scored, 5 unscored pretest). FINRA allocates the 125 scored items across four job functions: 9, 11, 91 and 14 (Function 3, information and recommendations, is 91).
How long is the General Securities Representative Qualification Examination (Series 7)?
225 minutes
What is the passing score for the General Securities Representative Qualification Examination (Series 7)?
Not published by FINRA (scale range). FINRA's Series 7 page lists "Passing Score 72", and the content outline says scores are equated onto a common scale; neither states that scale's range, so PrepPass does not render 72 as a percentage.
How much does the General Securities Representative Qualification Examination (Series 7) cost?
$395 — Exam fee (FINRA, per attempt)
What languages is the General Securities Representative Qualification Examination (Series 7) offered in?
Not published by FINRA. FINRA's exam page, content outline and Limited English Proficiency page name no exam language; the only language provision is extra time for eligible candidates whose primary language is not English.
Does the Series 7 study guide come as a PDF?
Yes — Series 7 — General Securities Representative Study Guide (2026) downloads as PDF and EPUB, 1,031 pages in all: 528 pages of teaching plus 1,176 practice questions with answers and explanations. The download link is emailed the moment payment clears and does not expire.
How much does the Series 7 study guide cost?
$24.99, once. There is no subscription and no account to create; the PDF and EPUB files are yours to keep.
Are there free Series 7 practice questions?
Yes — 1,176 of them, free to use with no signup and an explanation on every one. This study guide has 1,176 practice questions with answers and explanations. The same free, no-account system also has practice modes (adaptive, new questions, spaced review of misses, weak-topic focus, saved, my mistakes); a timed mock exam (125 questions, 225 minutes) with a score report by topic; a 10-question readiness check (about 5 minutes); 4 study chapters. None of it needs this study guide.
Can I read part of the Series 7 study guide before buying?
Yes. A full chapter is free to read on this page — not a summary of one, the chapter itself.
What is the difference between the Series 7 study guide and the cheat sheet?
The study guide ($24.99) teaches the material chapter by chapter and is meant to be read over weeks. The cheat sheet ($9.99, 6 pages) drops the teaching and keeps the figures: every number on the exam grouped by value so the confusable ones sit together, each reference page paired with a recall page that blanks the answers, and four routes by days left — 14, 7, 3, or tonight. They are separate purchases; neither replaces the other.
Is there a cheaper way to buy the Series 7 study guide with anything else?
Yes. FINRA SIE + Series 7 is $34.99 for 3 files in one checkout — 41% less than the $59.97 those items cost bought separately today. It adds SIE — Securities Industry Essentials Study Guide (2026), FINRA SIE — Cheat Sheet (2026). The saving is measured against the items' real current prices; there is no struck-through "original" price on this site.
Is this the official Series 7 study guide?
No. This is an independent study guide and is not affiliated with or endorsed by the exam's awarding body. It is written from FINRA content outline / SEC, FINRA, MSRB and OCC rules. Always confirm current requirements with the body that issues your licence.
Why buy the book when the practice is free?
Our practice questions and timed mock stay free — nothing on the site moves behind this book. The $24.99 book is the studying half: the material itself, taught in order, in a file you own.
- Systematic teaching — every exam section explained chapter by chapter, start to finish, not just questions
- Print it & tab it — a paper-ready PDF you can highlight, mark up, and bring to your study table
- Study anywhere, offline — EPUB on your phone or e-reader; no wifi, no browser tabs
- Everything in one place — the chapters and the practice questions in one file
- Yours for life — one-time $24.99, instant download, no subscription
The details
- Verified from the official source(FINRA content outline / SEC, FINRA, MSRB and OCC rules)
- 1,176 free practice questions
A Series 7 exam prep course runs $300–$900. This book teaches the same exam — same rules, verified to current standards — for a one-time $24.99 you keep for life.
Also free on PrepPass for Series 7
Beside this guide, PrepPass has a free study system for the same exam. It needs no account, and buying the guide does not unlock or change it: 1,176 practice questions with explanations; practice modes (adaptive, new questions, spaced review of misses, weak-topic focus, saved, my mistakes); a timed mock exam (125 questions, 225 minutes) with a score report by topic; a 10-question readiness check (about 5 minutes); 4 study chapters.
Progress is saved in your browser; a free account keeps it across devices. The readiness gauge reflects your own practice, not a prediction of the real exam result. How the practice works
One-time purchase, lifetime access to the download. The eBook is the full Series 7 study guide in PDF and EPUB. Educational summary, not professional or legal advice — always confirm the current rules with the official source. Last updated: October 2026.