NMLS SAFE MLO (Mortgage Loan Originator) · 2026 Edition
NMLS SAFE MLO — Complete Study Guide (2026)
The PrepPass NMLS SAFE MLO study guide book (2026 edition) is an independent guide: 639 pages of teaching plus 195 practice questions with a full answer key, PDF + EPUB, $29.99 one-time. Exam facts last checked September 2026 against the exam body's published sources.
- 195 practice questions inside the book, with a full answer key
- 639 pages of teaching, chapter by chapter — not a question dump
- Cross-referenced against SAFE Act / Reg Z, X, B, C / CFPB / NMLS outline
SAFE MLO Test enrolment (national component), non-refundable: $110 per attempt, paid to NMLS (State Regulatory Registry LLC). A retake pays it again. This guide: $29.99, one time.
$29.99one-time · lifetime download · no subscription
PDF + EPUB · English · 639 pages · $29.99 one-time
This book is written in English.
Instant download after payment — no account needed, no subscription.
14-day money-back guarantee: not satisfied for any reason? Email support@preppass.org within 14 days of purchase for a full refund. It's a download, so there is nothing to ship back. Refund policy
Exam facts last checked against official sources: September 2026.
To prepare for the NMLS SAFE MLO (Mortgage Loan Originator) exam, start with what the exam body publishes: SAFE MLO National Test with Uniform State Test Content Outline from Nationwide Multistate Licensing System (NMLS) — the official outline of every topic on the test, free (web page). That is enough if you only need to see what the exam covers; this book is for learning it and practising it. The exam itself (SAFE Mortgage Loan Originator Test with Uniform State Content (National Test Component)): 120 questions (115 scored, 5 unscored pretest), 190 minutes, passing score 75%. Choose this book if you are taking, or have finished, your required pre-licensing course and want a written review before the test. It does not count toward that education.
Try 10 questions first — free
Answer all 10, then see every answer explained — with the section of this guide that teaches it. About 5 minutes, no sign-up.
You do not need the book to practise: 400 practice questions for this exam are free on PrepPass.
Start 10 free questionsLook inside the book
Three real pages, rendered straight from the PDF you download — a reference page, a teaching page, and a worked question, always in that order. Nothing here was redrawn to look better.
- Quick referencePart I — Higher-priced mortgage loans · PDF page 72
A page you can turn back to: the numbers, deadlines or terms gathered in one place.
- How it's taughtPart X — The Loan Estimate and the Closing Disclosure, page by page · PDF page 147
An explanation page: the material taught in prose, in the order the exam tests it.
- How it's taughtPart I — Adjustable-rate mortgages · PDF page 257
An explanation page: the material taught in prose, in the order the exam tests it.
Studying more than one? There's a bundle price
- California Real Estate Salesperson Exam — Complete Study Guide (2026)$14.99
- NMLS SAFE MLO — Complete Study Guide (2026)$29.99
- California Real Estate Salesperson Exam — Cheat Sheet (2026)$9.99
- NMLS SAFE MLO — Cheat Sheet (2026)$9.99
Buy all 4: $32.99 — save $31.97 vs buying separately
Separately $64.96 · 49% off · One checkout, all 4 items.
Already bought California Real Estate Salesperson Exam? Don't buy the bundle — it includes that book and you'd pay for it twice. Get NMLS SAFE MLO (Mortgage Loan Originator) on its own for $29.99. NMLS SAFE MLO (Mortgage Loan Originator) · What's in the bundle →
Pairing it with a different trade exam?
Exam inside two weeks?
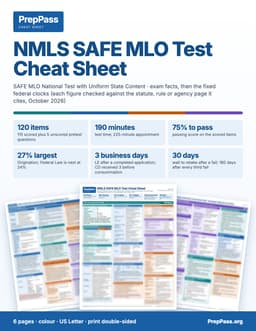
This guide is the teaching, read over weeks. If your exam is inside two weeks, the printable colour cheat sheet is the other product: the figures the exam turns on, laid out by section.
See the NMLS SAFE MLO cheat sheet PDF — $9.99 →
6 pages · US Letter · printable PDF · yours to keep
About the exam itself
| Administering body | Nationwide Multistate Licensing System (NMLS), operated by the State Regulatory Registry LLC for the Conference of State Bank Supervisors — exam delivered by Prometric |
|---|---|
| Questions | 120 questions (115 scored, 5 unscored pretest) Source: NMLS — MLO Testing Handbook, 1.0 Overview and Test Specifications |
| Time limit | 190 minutes |
| Passing score | 75% |
| Fees |
Source: NMLS — Processing Fees |
| Languages offered | Not published by NMLS What we read and found nothing in: NMLS — SAFE MLO Testing Frequently Asked Questions |
Questions buyers ask
- Which NMLS SAFE MLO (Mortgage Loan Originator) study guide should I use?
- It depends on what you already have. Nationwide Multistate Licensing System (NMLS): SAFE MLO National Test with Uniform State Test Content Outline, free (web page) — read it in any case to check every topic the test can ask about. Mometrix Test Preparation: NMLS Test Secrets, $28.99 ebook; $33.99 printed book — choose Mometrix if you mainly want several full-length practice tests, or a printed copy. This PrepPass guide: 639 pages, 195 practice questions with explanations, PDF + EPUB, $29.99 one-time — choose this book if you are taking, or have finished, your required pre-licensing course and want a written review before the test. It does not count toward that education. Prices were checked on 2026-09-24; confirm them with each seller.
- Is a study guide enough for the NMLS SAFE MLO (Mortgage Loan Originator) exam, or do I need a course?
- A book is exam review: it does not replace any education, training or experience Nationwide Multistate Licensing System (NMLS), operated by the State Regulatory Registry LLC for the Conference of State Bank Supervisors requires before you may sit the exam, so check those requirements first. For the exam content itself, this 639-page guide teaches the material chapter by chapter with 195 practice questions and explanations inside, and 400 more practice questions are free on PrepPass. A prep course adds live instruction and a set schedule; whether you need one beyond any required education is your call.
- What is the cheapest way to prepare for the NMLS SAFE MLO (Mortgage Loan Originator) exam?
- Start with what costs nothing: SAFE MLO National Test with Uniform State Test Content Outline from Nationwide Multistate Licensing System (NMLS) — free (web page) and 400 practice questions on PrepPass, with explanations and no signup. If you want it taught in one file you keep, the full study guide is $29.99 once; the printable cheat sheet for the last days is $9.99. No subscription on any of them.
- Who administers the SAFE Mortgage Loan Originator Test with Uniform State Content (National Test Component)?
- Nationwide Multistate Licensing System (NMLS), operated by the State Regulatory Registry LLC for the Conference of State Bank Supervisors — exam delivered by Prometric. NMLS states the test is available at all Prometric test centers. Prometric's own NMLS page could not be read — it returned HTTP 403 — so the vendor is confirmed from NMLS's side only.
- How many questions are on the SAFE Mortgage Loan Originator Test with Uniform State Content (National Test Component)?
- 120 questions (115 scored, 5 unscored pretest). The 75% pass standard applies to the 115 scored items only.
- How long is the SAFE Mortgage Loan Originator Test with Uniform State Content (National Test Component)?
- 190 minutes. The test itself is 190 minutes; the appointment booked at the test center is 225 minutes, which includes the tutorial and survey.
- What is the passing score for the SAFE Mortgage Loan Originator Test with Uniform State Content (National Test Component)?
- 75%. A single overall cut score. NMLS publishes no sectional or per-content-area cut score.
- How much does the SAFE Mortgage Loan Originator Test with Uniform State Content (National Test Component) cost?
- $110 — SAFE MLO Test enrolment (national component), non-refundable (NMLS (State Regulatory Registry LLC), per attempt); $36.25 — Criminal background check (Livescan), charged at each new license application (NMLS, one-time); $15 — Credit report, charged at a new license application when NMLS holds none under 30 days old (NMLS, one-time). State license fees are set by each state agency and are not included here. Most states also add state-specific pre-licensure education hours on top of the 20 NMLS-approved hours required before a license application; no course is required before sitting the test itself.
- What languages is the SAFE Mortgage Loan Originator Test with Uniform State Content (National Test Component) offered in?
- Not published by NMLS. NMLS publishes no statement of examination language anywhere we could find. The Testing FAQ, the Testing Handbook overview and test specifications, and the pre-licensure education FAQ were read in full and searched for “language”, “English” and “Spanish” with no result. PrepPass therefore states no language for this exam.
- Does the NMLS SAFE MLO (Mortgage Loan Originator) study guide come as a PDF?
- Yes — NMLS SAFE MLO — Complete Study Guide (2026) downloads as PDF and EPUB, 639 pages. The download link is emailed the moment payment clears and does not expire.
- How much does the NMLS SAFE MLO (Mortgage Loan Originator) study guide cost?
- $29.99, once. There is no subscription and no account to create; the PDF and EPUB files are yours to keep.
- Are there free NMLS SAFE MLO (Mortgage Loan Originator) practice questions?
- Yes — 400 of them, free to use with no signup and an explanation on every one. They are separate from this study guide, which is what you are buying here. The same free, no-account system also has practice modes (adaptive, new questions, spaced review of misses, weak-topic focus, saved, my mistakes); a timed mock exam (115 questions, 190 minutes) with a score report by topic; a 10-question readiness check (about 5 minutes); 5 study chapters; a day-by-day study plan. None of it needs this study guide.
- Can I read part of the NMLS SAFE MLO (Mortgage Loan Originator) study guide before buying?
- Yes. A full chapter is free to read on this page — not a summary of one, the chapter itself.
- What is the difference between the NMLS SAFE MLO (Mortgage Loan Originator) study guide and the cheat sheet?
- The study guide ($29.99) teaches the material chapter by chapter and is meant to be read over weeks. The cheat sheet ($9.99, 6 pages) drops the teaching and keeps the figures: every number on the exam grouped by value so the confusable ones sit together, each reference page paired with a recall page that blanks the answers, and four routes by days left — 14, 7, 3, or tonight. They are separate purchases; neither replaces the other.
- Is there a cheaper way to buy the NMLS SAFE MLO (Mortgage Loan Originator) study guide with anything else?
- Yes. CA Real Estate + NMLS SAFE MLO is $32.99 for 4 files in one checkout — 49% less than the $64.96 those items cost bought separately today. It adds California Real Estate Salesperson Exam — Complete Study Guide (2026), California Real Estate Salesperson Exam — Cheat Sheet (2026), NMLS SAFE MLO — Cheat Sheet (2026). The saving is measured against the items' real current prices; there is no struck-through "original" price on this site.
- Is this the official NMLS SAFE MLO (Mortgage Loan Originator) study guide?
- No. This is an independent study guide and is not affiliated with or endorsed by the exam's awarding body. It is written from SAFE Act / Reg Z, X, B, C / CFPB / NMLS outline. Always confirm current requirements with the body that issues your licence.
Free NMLS SAFE MLO (Mortgage Loan Originator) practice questions and study chapters →
How this book compares
NMLS publishes the SAFE MLO test content outline for free. This book teaches that outline with a full practice exam. Neither replaces the pre-licensing education your state requires.
| Resource | Price | What you get | Choose it if |
|---|---|---|---|
| This bookNMLS SAFE MLO — Complete Study Guide (2026)PrepPass | $29.99 | Downloadable study guide for the SAFE MLO test
| Choose this book if you are taking, or have finished, your required pre-licensing course and want a written review before the test. It does not count toward that education. |
| From the exam bodySAFE MLO National Test with Uniform State Test Content Outline (opens the publisher's page in a new tab)Nationwide Multistate Licensing System (NMLS) | Free (web page) | The official outline of every topic on the test | Read it in any case to check every topic the test can ask about. |
| AlternativeNMLS Test Secrets (opens the publisher's page in a new tab)Mometrix Test Preparation | $28.99 ebook; $33.99 printed book | Study guide with practice tests
| Choose Mometrix if you mainly want several full-length practice tests, or a printed copy. |
This book
NMLS SAFE MLO — Complete Study Guide (2026)
PrepPass
- Price
- $29.99
- What you get
Downloadable study guide for the SAFE MLO test
- 195 practice questions, each explained with its statute or regulation
- 639 pages, PDF + EPUB
- Choose it if
- Choose this book if you are taking, or have finished, your required pre-licensing course and want a written review before the test. It does not count toward that education.
From the exam body
Nationwide Multistate Licensing System (NMLS)
- Price
- Free (web page)
- What you get
The official outline of every topic on the test
- Choose it if
- Read it in any case to check every topic the test can ask about.
Alternative
NMLS Test Secrets (opens the publisher's page in a new tab)
Mometrix Test Preparation
- Price
- $28.99 ebook; $33.99 printed book
- What you get
Study guide with practice tests
- Five full-length practice tests (per the product title), 4th edition
- Choose it if
- Choose Mometrix if you mainly want several full-length practice tests, or a printed copy.
Other resources' prices and contents are as listed on each publisher's or seller's own page, checked September 24, 2026. Prices change; confirm on the linked page before you buy. This book's price and contents come from our own catalog.
Sources (2)
- https://mortgage.nationwidelicensingsystem.org/knowledge/products/nmls/pubs/testingHbk/education/mlo_testing/mlo_test_faq/mlo_testing_hbk_testOutline.html — read September 24, 2026
- https://www.mometrix.com/studyguides/nmls/ — read September 24, 2026
What's included — and what isn't
Included
- Learning objectives up front and key numbers & deadlines at the end of every chapter
- TRID timing (LE/CD clocks + the 3 CD-restart triggers), rescission
- RESPA, TILA/Reg Z (APR vs finance charge), ECOA vs Fair Housing
- HOEPA/QM (the price-based test that replaced the 43% DTI cap)
- SAFE Act licensing: 20-hr PE, 8-hr CE, 75%, and Temporary Authority
- A full-length 120-question practice exam (24/20/27/18/11 weighting) plus 75 chapter questions — every answer explained with its CFR or statute citation
- PDF (print & tab it) + EPUB (phone / e-reader)
Not included
- No printed copy is shipped — this is a file you download and can print yourself
- No video course, instructor or tutoring comes with the book — the free videos on the site are separate
- Not your exam registration or the testing centre's fee, which you still pay to the official body
Contents
See 23 sections and the page each one starts on
- Part I — Higher-priced mortgage loansp. 56
- Part V — The Homeowners Protection Actp. 108
- Part X — The Loan Estimate and the Closing Disclosure, page by pagep. 114
- Part I — Adjustable-rate mortgagesp. 195
- Part I — The Closing Disclosure in practicep. 299
- Part V — The closing documents and the feesp. 365
- Part X — The mathp. 374
- Section 9 — seller-required title insurance: a seller may notp. 408
- Part I — Sales contract and application red flagsp. 431
- Part V — Relationships with consumersp. 471
- Part I — The test, retakes, and the five-year lapsep. 518
- Part V — General loan origination scenariosp. 546
- Part II — Practice Questionsp. 551
- Chapter 1 — Federal Mortgage Laws (Questions 1– 18)p. 551
- Chapter 2 — General Mortgage Knowledge (Questions 19–33)p. 555
- Chapter 3 — Mortgage Origination Activities (Questions 34–53)p. 559
- Chapter 4 — Ethics (Questions 54–67)p. 563
- Chapter 5 — Uniform State Content: The SAFE Act (Questions 68–75)p. 566
- Answer Key & Explanationsp. 569
- Part III — Full-Length Practice Exam (120 Questions)p. 579
- Answer Key & Explanations — Part III Full-Length Examp. 605
- Appendix A — Federal timing & threshold quick referencep. 624
- Appendix B — Glossary of key termsp. 627
Taken from the PDF you download, with the page each one starts on — not typed here.
Read a chapter free, in full
One complete chapter, exactly as it ships in the eBook. Scroll the window to read it right here; no download, no email.
Read chapter 1 here, without leaving the page
Introduction
Federal law governs nearly every step of a residential mortgage, from the first disclosure a borrower receives to the money that changes hands at the closing table. It is the second-heaviest area on the SAFE MLO test — roughly 24% of your score — and it overlaps so heavily with Origination (Chapter 3) and Ethics (Chapter 4) that the points you earn here are earned three times over.
The reason this material is so testable is that it is almost entirely rules with triggers and clocks. A specific event starts a specific countdown, and a specific document must reach the borrower by a specific deadline. Learn the trigger, learn the deadline, and you have the point. The catch is that the exam is written precisely to separate the two disclosures everyone confuses — the Loan Estimate and the Closing Disclosure — and to separate the finance charge and APR world of the Truth in Lending Act from the settlement-cost world of the Real Estate Settlement Procedures Act.
There is a second reason this chapter repays close reading. Almost every number in it falls into one of two categories, and the exam punishes candidates who cannot tell them apart. The timing rules are fixed: the three-business-day Loan Estimate, the seven-business-day waiting period, the three-business-day Closing Disclosure receipt rule, the three-day right of rescission, the thirty-day adverse-action notice. Those have not moved in years and you should memorize them cold. The dollar thresholds are not fixed: the HOEPA points-and-fees cutoffs, the Qualified Mortgage points-and-fees caps, the HMDA asset threshold, the conforming and FHA loan limits. The regulations themselves say those figures are "adjusted annually on January 1." A study aid that prints one of them as gospel is telling you something that will be false next January, and this book will not do that. Where a figure moves, you will see subject to change and a pointer to the agency that publishes it.
A note on who runs all of this. Since the Dodd-Frank Wall Street Reform and Consumer Protection Act of 2010, rulemaking authority for almost every consumer mortgage statute in this chapter — TILA, RESPA, ECOA, HMDA, FCRA's mortgage-relevant provisions, GLBA privacy — was consolidated in the Consumer Financial Protection Bureau. That is why the regulations you will cite live in Title 12, Chapter X of the Code of Federal Regulations: Regulation X at 12 CFR part 1024, Regulation Z at 12 CFR part 1026, Regulation B at 12 CFR part 1002, Regulation C at 12 CFR part 1003, Regulation V at 12 CFR part 1022, Regulation P at 12 CFR part 1016, Regulation N at 12 CFR part 1014, and Regulation H at 12 CFR part 1008. When you see "Regulation Z," think "the CFPB's rule implementing the Truth in Lending Act." The statute is the authority; the regulation is the operating manual; and the exam quotes the operating manual.
This chapter walks the statutes in the order the exam frames them. Part A and Part B cover RESPA and Regulation X — the settlement-service world, the anti-kickback rule, escrow accounts, and servicing. Parts C, D and E cover ECOA and Regulation B — the nine prohibited bases, the thirty-day adverse-action clock, and the government-monitoring questions you must ask. Parts F and G cover TILA and Regulation Z at its foundations — the finance charge, the APR, and the right of rescission. Parts H, I and J cover the three Regulation Z rules that most often decide a borrower's price: HOEPA high-cost mortgages, higher-priced mortgage loans, and the loan originator compensation rule. Parts K, L, M and N cover TRID — the Loan Estimate, the Closing Disclosure, the tolerance buckets, and the record-retention rules that trip up almost everyone. Parts O through W cover the remaining federal laws the outline names: HMDA, FCRA and FACTA, the Red Flags Rule, BSA/AML and the USA PATRIOT Act, GLBA privacy and the Safeguards Rule, Regulation N advertising, the E-Sign Act, the Homeowners Protection Act, and finally Dodd-Frank itself and the two agencies the outline asks you to know — the CFPB and HUD.
Learning objectives
After working through this chapter you should be able to:
- Distinguish RESPA/Regulation X (settlement-service abuses, kickbacks, escrow, servicing — 12 CFR part 1024) from TILA/Regulation Z (the true cost of credit — 12 CFR part 1026), and explain how TRID integrates their disclosures.
- State the RESPA Section 8 prohibition precisely: no fee, kickback or thing of value for a referral of settlement-service business (12 CFR §1024.14(b)), and no split of a charge except for services actually performed (§1024.14(c)).
- Recite the six items that make a mortgage application complete and start the Loan Estimate clock (12 CFR §1026.2(a)(3)(ii)), and explain why an originator may not withhold the sixth to stall the clock.
- State the two central TRID clocks cold: the Loan Estimate delivered or mailed within 3 business days of a completed application and no later than 7 business days before consummation (§1026.19(e)(1)(iii)); the Closing Disclosure received by the borrower at least 3 business days before consummation (§1026.19(f)(1)(ii)(A)).
- Apply the two different definitions of "business day" in §1026.2(a)(6), and say which TRID paragraph takes which.
- Explain the three tolerance categories under §1026.19(e)(3) — zero tolerance, the 10 percent cumulative bucket, and the charges for which variation is permitted — and what a valid changed circumstance under §1026.19(e)(3)(iv) does to them.
- List the nine prohibited bases under ECOA/Regulation B §1002.2(z) and distinguish them from the seven protected classes of the Fair Housing Act at 42 U.S.C. §3605(a).
- State the adverse-action timing rules of §1002.9(a)(1) and the content requirements of §1002.9(a)(2), and the ECOA valuations rule of §1002.14(a)(1).
- Describe HMDA/Regulation C reporting — the loan/application register, the March 1 deadline (§1003.5(a)(1)(i)), and the indexed asset threshold — and the FCRA rules on permissible purpose, adverse action, and risk-based pricing.
- Explain the GLBA privacy notice and Safeguards duty, and the BSA/AML written-program and suspicious activity report obligations for non-bank mortgage lenders (31 CFR §§1029.210, 1029.320).
- Apply the LO Compensation Rule (§1026.36(d)) — no compensation based on a term of the transaction, no proxies, no dual compensation, no steering — and the NMLSR ID requirement of §1026.36(g).
- Identify a HOEPA high-cost mortgage by its three triggers (§1026.32(a)(1)), distinguish it from a higher-priced mortgage loan under §1026.35, and say which figures in each are indexed.
- State the Homeowners Protection Act equity points — 80 percent on borrower request, 78 percent automatically, and the amortization midpoint as a final backstop (12 U.S.C. §§4901, 4902).
- Apply the right of rescission (§1026.23): which transactions carry it, the three-business-day clock, the three-year backstop, and the twenty-calendar-day mechanics.
- Reproduce the four-way record-retention split: Regulation Z generally two years, TRID records three years, the Closing Disclosure itself five years, Regulation B twenty-five months.
### Key numbers & deadlines — the federal clocks Loan Estimate, delivery: delivered or placed in the mail no later than the 3rd business day after the creditor receives the consumer's application (12 CFR §1026.19(e)(1)(iii)(A)). Fixed. Loan Estimate, waiting period: also no later than the 7th business day before consummation (§1026.19(e)(1)(iii)(B)). Fixed. Closing Disclosure: the consumer must receive it no later than 3 business days before consummation (§1026.19(f)(1)(ii)(A)). Fixed. Mailbox rule: a disclosure not handed over in person is deemed received 3 business days after it is delivered or placed in the mail (§1026.19(e)(1)(iv) for the LE; §1026.19(f)(1)(iii) for the CD). Fixed. The six items of a complete application: name, income, Social Security number to obtain a credit report, property address, estimate of the value of the property, and the mortgage loan amount sought (§1026.2(a)(3)(ii)). Fixed. Two "business day" definitions: the general one is any day the creditor is open to the public for substantially all of its business functions; the precise one is all calendar days except Sundays and the legal public holidays in 5 U.S.C. 6103(a) (§1026.2(a)(6)). Fixed. Right of rescission: until midnight of the third business day after the latest of consummation, delivery of the notice, or delivery of all material disclosures; 3 years if the notice or material disclosures were never delivered (§1026.23(a)(3)(i)). Fixed. Rescission mechanics: the creditor has 20 calendar days after receiving the notice to return money and release the security interest (§1026.23(d)(2)); the consumer may keep tendered property the creditor does not collect within 20 calendar days (§1026.23(d)(3)). Fixed. ECOA adverse action: notify within 30 days of a completed application, of adverse action on an incomplete application, or of adverse action on an existing account; 90 days after an unaccepted counteroffer (12 CFR §1002.9(a)(1)). Fixed. ECOA valuations: copies of all appraisals and written valuations on a first-lien dwelling loan, promptly upon completion or 3 business days before consummation, whichever is earlier; the right-to-receive notice within 3 business days of application (§1002.14(a)(1)–(2)). Fixed. Record retention, the four-way split: Regulation Z generally 2 years (§1026.25(a)); TRID §1026.19(e) and (f) records 3 years (§1026.25(c)(1)(i)); the Closing Disclosure itself 5 years (§1026.25(c)(1)(ii)(A)); Regulation B 25 months (§1002.12(b)(1)). Fixed. BSA/AML: file a suspicious activity report within 30 calendar days of initial detection, extendable to 60 only where no suspect has been identified (31 CFR §1029.320(a)(3)). Fixed.
Part A — RESPA: origins, coverage, and the settlement-service world
Why RESPA exists, and what a "federally related mortgage loan" is
The Real Estate Settlement Procedures Act, enacted in 1974 and now implemented by the CFPB's Regulation X at 12 CFR part 1024, was written against a specific abuse. In the settlement industry of the early 1970s, the people who steered consumers toward title companies, escrow agents, appraisers, and insurers were routinely paid for the steering. The consumer never saw the payment, could not shop it, and paid for it inside a settlement charge that looked like the price of a service. RESPA's answer was two-sided: make the costs visible through mandated disclosures, and make the hidden payments illegal.
Coverage runs through a defined term. RESPA applies to a federally related mortgage loan — broadly, a loan secured by a first or subordinate lien on residential real property designed principally for the occupancy of one to four families, where the lender is federally regulated or insured, the loan is insured or guaranteed by a federal agency, the loan is intended for sale to Fannie Mae, Freddie Mac or Ginnie Mae, or the lender makes mortgage loans above a de minimis annual volume. The practical consequence is that nearly every residential mortgage an originator will ever touch is covered. What is not covered is the transaction that is not residential and not consumer-purpose: a loan on a twelve-unit apartment building, a loan primarily for a business or agricultural purpose, and — historically — certain vacant-land and construction-only loans.
The reason to learn the definition rather than the shorthand is that the exam builds items around the edges of it. A candidate who has memorized "RESPA covers mortgages" will answer a question about a loan on a 25-unit apartment complex the same way as a question about a duplex, and only one of those is a federally related mortgage loan. The one-to-four-family limit is the line that does most of the work.
Do not fall for the idea that RESPA is a pricing statute. It does not tell a lender what it may charge. It tells the lender what it must disclose, and it tells everyone in the settlement chain what they may not pay each other (12 CFR §1024.14). A question that asks whether RESPA caps a title fee is testing whether you know the difference between a disclosure statute and a rate regulation.
Example. A borrower in Toledo is buying a four-unit building, intending to live in one unit and rent the other three. The lender is a federally insured bank. This is a loan secured by a lien on residential property designed principally for the occupancy of one to four families, made by a federally insured lender — a federally related mortgage loan, and Regulation X applies in full. Change the building to five units and the same loan falls outside RESPA's residential coverage, even though nothing about the borrower changed.
"Settlement service" and "mortgage broker" — the two definitions the exam leans on
A settlement service is any service provided in connection with a real estate settlement. Regulation X's own list is long and deliberately so: title searches, title examinations, the provision of title certificates, title insurance, services rendered by an attorney, the preparation of documents, property surveys, the rendering of credit reports or appraisals, pest and fungus inspections, services rendered by a real estate agent or broker, the origination of a federally related mortgage loan, and the handling of the processing and closing. The breadth is the point. If it is a service someone is paid for in order to make a closing happen, it is almost certainly a settlement service, and the anti-kickback rule of §1024.14 reaches it.
A mortgage broker, for RESPA purposes, is a person or entity that, for compensation or in expectation of compensation, brings a borrower and a lender together — a person who renders origination services and serves as an intermediary between a borrower and a lender, without using its own funds to close the loan. The contrast the exam wants is with a lender, which funds the loan, and with a table-funded transaction, in which a broker closes a loan in its own name with funds advanced at settlement by an assignee. Regulation X treats table funding as a secondary-market transaction only in form; in substance the funding party is the lender, and RESPA looks through the paperwork.
Why does that matter to an originator? Because the answer to "who owes the disclosure" and "who may be paid" depends on which role a person occupies. A broker's compensation is a settlement charge disclosed on the consumer's forms. A lender's yield on the loan is not. Blurring the two is exactly how the pre-2010 yield-spread-premium abuses worked, and it is why the Regulation Z compensation rule (Part J of this chapter) now supplements RESPA rather than duplicating it.
Two misconceptions to bury. First, a real estate agent is providing a settlement service, even though the agent is not in the lending business: the agent's commission is a settlement charge, and the agent is squarely inside the anti-referral rule. Second, an attorney is not exempt from Section 8; §1024.14(g)(1)(i) permits payment "to an attorney at law for services actually rendered," which is a permission to pay for work, not a permission to pay for referrals.
Example. A mortgage broker takes an application, orders the appraisal and title work, and arranges the loan, which closes in the broker's name using funds wired by the eventual investor at settlement. The broker never risks its own money. This is table funding; the broker is rendering origination services as an intermediary, and its compensation is a settlement charge to be disclosed, not an invisible spread.
RESPA's prohibitions, limitations, and exemptions
Regulation X's prohibitions cluster into four groups, and the exam draws from all four.
Section 8(a) — referral fees. "No person shall give and no person shall accept any fee, kickback or other thing of value pursuant to any agreement or understanding, oral or otherwise, that business incident to or part of a settlement service involving a federally related mortgage loan shall be referred to any person" (12 CFR §1024.14(b)). The regulation then closes the obvious escape route: "Any referral of a settlement service is not a compensable service." You cannot characterize a referral as work and pay for it.
Section 8(b) — unearned fees and fee splits. "No person shall give and no person shall accept any portion, split, or percentage of any charge made or received for the rendering of a settlement service … other than for services actually performed" (§1024.14(c)). A charge for no or nominal services, or a duplicative fee, is an unearned fee and violates the section. Note the sentence the exam likes: "The source of the payment does not determine whether or not a service is compensable." It does not matter whether the money comes from the borrower, the lender, or a third party.
Section 9 — required use of a title company. A seller may not require, as a condition of selling the property, that the buyer purchase title insurance from any particular company.
Section 10 — escrow limits. A lender may not require escrow deposits beyond the amounts Regulation X permits, including the cushion limit discussed in Part B.
The limitations and exemptions matter as much as the prohibitions. Section 8 does not prohibit a payment to an attorney for services actually rendered, a payment by a title company to its duly appointed agent for services actually performed in the issuance of a title policy, a payment by a lender to its duly appointed agent for services actually performed in the making of a loan, a payment to any person of a bona fide salary or compensation for goods or facilities actually furnished or services actually performed, or an employer's payment to its own employees for generating business for the employer (§1024.14(g)(1)). It also does not prohibit normal promotional and educational activities that are not conditioned on referrals and do not defray expenses the recipient would otherwise incur.
The unifying idea, and the one that answers most exam items: you may pay for a thing of value received; you may not pay for a stream of business. Ask what the payer got. If the honest answer is "customers," it is a referral fee.
Example. A lender hosts a continuing-education class for local real estate agents, provides coffee and materials, and does not condition attendance on any agent sending it loans. That is normal promotional and educational activity. The same lender then offers each agent a $300 payment for every buyer who closes a loan with it. That is a referral fee under §1024.14(b), and the fact that the agent also performed genuine real estate work for the buyer does not save it — the $300 is not payment for that work.
Before you buy
- How do I get it?
- Pay, and the download appears on this page straight away. The links are also emailed to you. No account is required.
- What if it isn't for me?
- Email us within 14 days for a full refund, no questions asked.
- Is the free practice going away?
- No. Every practice question, the timed mock and the free chapters on this site stay free. This book is the studying half, not a gate around the free half.
- Can I read it on my phone?
- Yes — the EPUB is for phones and e-readers, the PDF is for printing and tabbing. You get both.
The details
Federal mortgage law (TRID, RESPA, TILA, ECOA, HOEPA/QM), general mortgage knowledge, origination, ethics, and the SAFE Act — the national test — with a full-length 120-question practice exam.
- Format: PDF + EPUB download · 639 pages
- 195 practice questions in the book, with a full answer key
- 400 free practice questions for this exam on PrepPass, included at no cost
- $29.99 one-time — no subscription
- 14-day money-back guarantee · refund policy
- Cross-referenced against: SAFE Act / Reg Z, X, B, C / CFPB / NMLS outline
- Last updated: September 2026
- Verified from the official source(SAFE Act / Reg Z, X, B, C / CFPB / NMLS outline)
- 400 free practice questions
- Instant download, yours for life
“I didn't read every page cover to cover. Mostly used the guide for the areas I was weak on and then kept doing questions.”
Individual results, shared with permission. Not a pass-rate claim.
An NMLS 20-hour SAFE pre-license course runs $250–$599. This book teaches the same exam — same rules, verified to current standards — for a one-time $29.99 you keep for life.
Why buy the book when the practice is free?
Our practice questions and timed mock stay free — nothing on the site moves behind this book. The $29.99 book is the studying half: the material itself, taught in order, in a file you own.
- Systematic teaching — every exam section explained chapter by chapter, start to finish, not just questions
- Print it & tab it — a paper-ready PDF you can highlight, mark up, and bring to your study table
- Study anywhere, offline — EPUB on your phone or e-reader; no wifi, no browser tabs
- Everything in one place — the chapters and the practice questions in one file
- Yours for life — one-time $29.99, instant download, no subscription
And it's risk-free: 14-day money-back guarantee — not satisfied? Email us for a full refund, no questions asked. See the refund policy.
Also free on PrepPass for NMLS SAFE MLO (Mortgage Loan Originator)
Beside this guide, PrepPass has a free study system for the same exam. It needs no account, and buying the guide does not unlock or change it: 400 practice questions with explanations; practice modes (adaptive, new questions, spaced review of misses, weak-topic focus, saved, my mistakes); a timed mock exam (115 questions, 190 minutes) with a score report by topic; a 10-question readiness check (about 5 minutes); 5 study chapters; a day-by-day study plan.
Progress is saved in your browser; a free account keeps it across devices. The readiness gauge reflects your own practice, not a prediction of the real exam result. How the practice works
14-day money-back guarantee · full refund, no questions asked.
One-time purchase, lifetime access to the download. The eBook is the full NMLS SAFE MLO (Mortgage Loan Originator) study guide in PDF and EPUB. Educational summary, not professional or legal advice — always confirm the current rules with the official source. Last updated: September 2026.