Guía de estudio · Edición 2026
SIE — Securities Industry Essentials Study Guide (2026)
Twenty-seven chapters written to FINRA's SIE content outline, with the working shown on every calculation and a practice question bank behind them.
- Extensión
- 845 páginas (358 de enseñanza + banco de preguntas)
- Preguntas de práctica en el libro
- 1,149
- Simulacro en línea de PrepPass
- 75 preguntas · 105 min
- Datos verificados y archivo actualizado
- octubre de 2026
- Entrega
- PDF + EPUB · en inglés · descarga inmediata
Sobre este libro
Tarifa del examen SIE: $100 por intento, que se paga a FINRA. Repetir el examen vuelve a costarlo. Esta guía: $24.99, pago único.
Datos del examen, a quién le sirve y qué cambió
Sobre el examen en sí
| Organismo administrador | Financial Industry Regulatory Authority (FINRA) — examen administrado por Prometric |
|---|---|
| Preguntas | 80 preguntas (75 calificadas, 5 de prueba sin calificar) Fuente: FINRA — Securities Industry Essentials (SIE) Examination Content Outline (PDF, © 2025 FINRA) |
| Tiempo límite | 105 minutos Fuente: FINRA — Securities Industry Essentials (SIE) Examination Content Outline (PDF, © 2025 FINRA) |
| Puntuación para aprobar | Puntuación escalada de 70 en una escala de 0–100 Fuente: FINRA — SIE Exam and Exam Restructuring Frequently Asked Questions (FAQ) |
| Tarifas |
|
| Idiomas disponibles | No publicado por FINRA Lo que leímos y donde no aparece: FINRA — Securities Industry Essentials Exam (SIE) |
Mira dentro del libro
Tres páginas reales, renderizadas directamente del PDF que descargas — una página de referencia, una de explicación y una pregunta resuelta, siempre en ese orden. Nada se rediseñó para verse mejor.
- Referencia rápidaChapter 7 — Bonds: Pricing, Yields, Corporates, Treasuries and Municipals · Página 137 del PDF
Una página a la que puedes volver: cifras, plazos o términos reunidos en un solo lugar.
- Cómo se enseñaSection 32 Criminal: entities Fine up to $25 million · Página 327 del PDF
Una página de explicación: el material enseñado en prosa, en el orden en que lo evalúa el examen.
- Una pregunta resueltaChapter 5 — Rights, Warrants, ADRs and Convertible Securities · Página 90 del PDF
Una pregunta de práctica con su respuesta y el razonamiento detrás — no solo la clave.
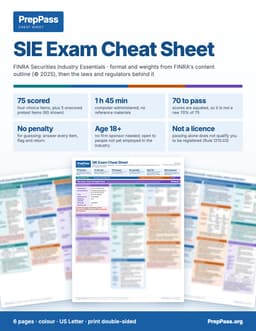
¿Examen en menos de dos semanas?
Esta guía es la enseñanza, para leer durante semanas. Si tu examen es en menos de dos semanas, la hoja de referencia a color imprimible es el otro producto: las cifras clave, por secciones.
6 páginas · US Letter · PDF imprimible · tuyo para siempre
Qué incluye — y qué no
Incluido
- Twenty-seven chapters in the teaching order of FINRA's SIE content outline: regulators, capital markets, products and their risks, trading and customer accounts, conduct and registration
- Every chapter closes with a key-facts box and a named exam-traps list
No incluido
- No se envía copia impresa — es un archivo que descargas y puedes imprimir tú
- El libro no incluye curso en vídeo, instructor ni tutorías — los vídeos gratis del sitio van aparte
Todo lo incluido y todo lo que no
Incluido
- Worked examples with the working shown where the exam asks for arithmetic: bond pricing and yield, accrued interest, options breakeven, margin, settlement dates
- A chapter on taking the exam: format, retake waiting periods, a study plan and the ten most common confusions
- Dated rule changes called out, including the end of the pattern-day-trader rule and T+1 settlement
- 358 pages of teaching, then a question bank of 1149 practice questions, grouped by topic, with answers and explanations
- PDF (print & tab it) + EPUB (phone / e-reader)
No incluido
- No incluye tu inscripción al examen ni la tasa del centro, que sigues pagando al organismo oficial
Contenido
Ver 32 secciones y la página en la que empieza cada una
- Chapter 1 — Who Regulates the Markets and Who Works in Themp. 9
- Chapter 2 — Capital Markets, Offerings and Registrationp. 24
- Chapter 3 — The Economy, the Federal Reserve and Company Financialsp. 47
- Chapter 4 — Common and Preferred Stockp. 66
- Chapter 5 — Rights, Warrants, ADRs and Convertible Securitiesp. 88
- Chapter 6 — Corporate Actions, Buybacks and Proxiesp. 98
- Chapter 7 — Bonds: Pricing, Yields, Corporates, Treasuries and Municipalsp. 107
- Chapter 8 — Agency and Mortgage Securities, Municipal Variations, Money Market and Ratingsp. 127
- Chapter 9 — Investment Companies: Mutual Funds, ETFs, Closed-End Funds and UITsp. 143
- Chapter 10 — What Funds, Annuities and Trades Costp. 164
- Chapter 11 — Municipal Fund Securities, Partnerships, REITs, Hedge Funds and Exchange-Traded Productsp. 176
- Chapter 12 — Options: Calls, Puts, Strategies, the OCC and Opening an Accountp. 187
- Chapter 13 — Investment Risks and How to Reduce Themp. 205
- Chapter 14 — Where Securities Trade: Venues, Market Makers, Regulation NMS, Best Execution, Reporting and Haltsp. 214
- Chapter 15 — Orders, Quotes and Positionsp. 228
- Chapter 16 — Clearing, Settlement and Failed Tradesp. 236
- Chapter 17 — Return, Cost Basis, Tax and Benchmarksp. 243
- Chapter 18 — Margin and Short Salesp. 251
- Chapter 19 — Knowing the Customer, Recommendations, Regulation Best Interest and Form CRSp. 267
- Chapter 20 — Account Types, IRAs and Retirement Plansp. 284
- Chapter 21 — Anti-Money Laundering: FinCEN, OFAC, Structuring and the PATRIOT Actp. 293
- Chapter 22 — Confirmations, Statements, Customer Mail, Continuity Plans and Safeguarding Customer Assetsp. 301
- Chapter 23 — Market Manipulation, Insider Trading and Fraudp. 308
- Section 32 Criminal: entities Fine up to $25 millionp. 314
- Chapter 24 — Conduct Rules: Customer Funds, Trading Practices and Cooperation with Regulatorsp. 317
- Chapter 25 — Who May Work in the Industry: Qualification, Registration and Disqualificationp. 331
- Chapter 26 — Hiring, Disclosure, Reporting and Municipal Personnel Rulesp. 340
- Chapter 27 — Taking the SIE: Format, Chapter Map, Study Plan and Ten Confusionsp. 349
- Section 1: Capital Markets (16%)p. 351
- Section 2: Products and Their Risks (44%)p. 351
- Section 4: Regulatory Framework (9%)p. 353
- Appendix — Question Bank 1,149 practice questions with answers and explanationsp. 359
Tomado del PDF que descargas, con la página en la que empieza cada uno — no escrito a mano aquí.
Lee un capítulo completo gratis
Un capítulo completo, tal como viene en el eBook. Desplázate en la ventana para leerlo aquí; sin descargas ni correo.
Lee el capítulo 17 aquí, sin salir de la página
No te dimos la introducción fácil — el capítulo gratis abre en una de las partes más exigentes del libro, para que juzgues la enseñanza donde el examen se pone difícil.
Every investment is judged by what it returns and by what is left after tax. This chapter defines total return, shows how cost basis is set and changed, explains the wash-sale rule and the short-term and long-term capital-gains treatment, and closes with the benchmarks and indices used to judge a portfolio. Dividend types and dates are in Chapter 4.
Words you need
- Return. What an investment earned over a period, usually stated as a percentage of what was put in.
- Income. Cash an investment pays out while you hold it: dividends from stock, interest from bonds.
- Capital gain / capital loss. The profit or loss when you sell for more or less than your cost basis. It is "realized" only when you sell; before then it is "unrealised".
- Total return. Income plus change in price, over the period, as a percentage of the starting value.
- Dividend. A distribution of a company's profit to its shareholders, set by the board of directors.
- Cost basis. What you are treated as having paid for a security. Gain or loss is sale proceeds minus basis.
- Holding period. How long you owned the security. It decides whether a gain is short term or long term.
- Wash sale. Selling at a loss and buying the same or a substantially identical security within a 30-day window around the sale.
- Benchmark. A standard, often an index, against which a portfolio's results are compared.
- Index. A published number that tracks the prices of a defined group of securities. You cannot buy an index directly; funds copy it.
Components of return
An investor can earn money from a security in two ways.
- Income. Dividends or interest paid in cash while you hold it.
- Capital appreciation. The price rises, so you could sell for more than you paid.
Total return = (income + change in price) / starting price.
Worked example. You buy 100 shares at $50 ($5,000). Over the year you receive $1.80 per share in dividends and the price rises to $56.
| Piece | Calculation | Amount |
|---|---|---|
| Income | 100 × $1.80 | $180 |
| Capital gain (unrealized until sold) | 100 × ($56 − $50) | $600 |
| Total | $180 + $600 | $780 |
| Total return | $780 / $5,000 | 15.6% |
The two pieces carry different risks. Income from a stable company is steadier; price change is volatile. Growth-oriented investors lean on appreciation, income-oriented investors on cash payments. A bond held to maturity returns income and a return of principal, with any gain or loss depending on purchase price (Chapter 7).
The exam also separates nominal return (before inflation) from real return (after). With a nominal return of 7.4% and inflation of 3.0%, the approximate real return is 7.4% − 3.0% = 4.4%.
Cost basis
Gain or loss on a sale is proceeds minus cost basis. Basis starts as the price you paid plus commissions and fees, and changes with events such as stock dividends, splits and return of capital.
How you acquired the shares changes the basis
| How acquired | Basis |
|---|---|
| Purchase | Cost plus commissions |
| Gift | The donor's basis carries over to you. If you sell at a loss, your loss is measured from the lower of that basis and the market value at the date of the gift (IRC §1015) |
| Inheritance | Fair market value on the date of death (a "step-up" or "step-down"), and the holding period is automatically long term |
| Stock dividend or split | Original basis divided over the larger number of shares |
| Reinvested dividends | Each reinvestment is a new purchase at its own cost |
When you hold several lots
If you bought shares at different prices, you must say which you are selling.
Worked example. You hold three lots of 100 shares: bought at $30, $40 and $50. You sell 100 shares at $55.
| Method | Lot treated as sold | Basis | Gain |
|---|---|---|---|
| FIFO (first in, first out), the default for stock | $30 lot | $3,000 | $2,500 |
| Specific identification (you name the lot before settlement) | $50 lot | $5,000 | $500 |
| Specific identification | $40 lot | $4,000 | $1,500 |
| Average cost (available for mutual fund shares) | all lots | $40 average | $1,500 |
Average basis: (3,000 + 4,000 + 5,000) / 300 = $40. The same sale produces a gain anywhere from $500 to $2,500 depending on the method, which is why the choice matters. Choosing the highest-basis lot defers tax now; it does not remove it.
Broker reporting of basis
Since the Emergency Economic Stabilization Act of 2008, brokers must report cost basis to the investor and the IRS on Form 1099-B for "covered" securities. Covered means acquired on or after 1 January 2011 for stock, 1 January 2012 for mutual fund shares and dividend-reinvestment plan shares, and 1 January 2014 for most bonds and options. For older "non-covered" securities the broker may not report basis, and the investor must keep records. The broker's default method is FIFO for stock and average cost for mutual funds unless the customer chooses another in time.
The wash-sale rule
The tax law does not allow you to sell at a loss and keep the position. If you buy the same or a substantially identical security within 30 days before or after the sale (a 61-day window including the sale day), the loss is disallowed for now. It is added to the basis of the replacement shares, and the holding period carries over.
Worked example. You sold 100 shares for $5,000 that had cost $7,000: a loss of $2,000. Fifteen days later you buy 100 shares at $48 ($4,800). The $2,000 loss is disallowed. New basis = $4,800 + $2,000 = $6,800, or $68 per share. If you later sell at $60, the gain or loss is $6,000 − $6,800 = a $800 loss, which you can use.
Worked example (partial). You sell 300 shares at a $3,000 loss ($10 a share) and buy back 100 shares within 30 days. Only the replaced one-third is disallowed: 100 × $10 = $1,000 disallowed, $2,000 allowed as a loss now.
The rule applies to purchases in an IRA or by a spouse as well. It affects losses only; gains are never "washed".
Capital-gains tax: short term and long term
| Holding period | Class | Tax treatment |
|---|---|---|
| One year or less | Short term | Taxed as ordinary income at the investor's marginal rate |
| More than one year | Long term | Taxed at preferential rates of 0%, 15% or 20% depending on taxable income |
The holding period starts the day after you acquire the security and includes the day you sell. A purchase on 10 March 2025 and a sale on 10 March 2026 is a one-year hold, which is still short term. A sale on 11 March 2026 is long term.
Higher-income investors may also owe the 3.8% net investment income tax on investment income above statutory thresholds of $200,000 (single) and $250,000 (married filing jointly) of modified adjusted gross income. These NIIT thresholds are set by statute (IRC §1411) and are not indexed; the income brackets for the 0/15/20% rates are indexed annually and are not stated here.
Netting. Gains and losses are netted within each class, then across classes. If losses exceed gains, up to $3,000 of the net loss a year can offset ordinary income (and $1,500 if married filing separately); the rest carries forward to later years indefinitely (IRC §1211(b)).
Worked example. A $600 gain on shares held 8 months is short term. At a 24% marginal rate the tax is $600 × 0.24 = $144. The same $600 gain after 14 months, at 15%, is $90. Waiting saved $54.
Municipal bond interest is generally federally tax-exempt, but a capital gain on selling a municipal bond is taxable like any other gain.
Benchmarks and indices
A benchmark answers: "compared with what?" A portfolio return of 6% sounds acceptable. If the right benchmark returned 11%, it is not.
| Index | What it tracks | How it is weighted |
|---|---|---|
| S&P 500 | About 500 large U.S. companies | Market capitalization (price × shares outstanding) |
| Dow Jones Industrial Average | 30 large U.S. companies | Price weighted |
| Nasdaq Composite | Most stocks listed on the Nasdaq exchange | Market-cap weighted |
| Russell 2000 | 2,000 smaller U.S. companies | Market-cap weighted |
| MSCI EAFE | Developed markets outside the U.S. and Canada | Market-cap weighted |
| Bloomberg U.S. Aggregate Bond Index | Investment-grade U.S. bonds | Market-value weighted |
The index must match the portfolio. Comparing a bond fund with the S&P 500, or a small-cap fund with the Dow, tells you nothing.
How weighting changes the answer
Three stocks, A, B and C, with prices $100, $50 and $30. Shares outstanding: A 10 million, B 100 million, C 200 million. Market capitalizations: A $1,000m, B $5,000m, C $6,000m, total $12,000m.
Stock A rises from $100 to $110; the others do not move.
| Weighting | Calculation | Index change |
|---|---|---|
| Price weighted | Sum of prices 180 → 190, so 190/180 − 1 | +5.56% |
| Market-cap weighted | Total cap 12,000 → 12,100, so 12,100/12,000 − 1 | +0.83% |
| Equal weighted | (10% + 0% + 0%) / 3 | +3.33% |
The price-weighted index is moved most by the highest-priced stock, regardless of company size. The cap-weighted index is moved most by the biggest companies. This is why the Dow can be influenced by a high-priced stock that is small in value, a favorite exam point.
Index funds and ETFs try to match an index; active managers try to beat it. A fund's gap from the benchmark is its tracking difference.
Key facts — Return and tax - Total return = income + price change, as a percentage of the starting price. - Gain or loss = proceeds − cost basis. Gift: donor's basis carries over. Inheritance: market value at death and long-term treatment. - Default basis method: FIFO for stock, average cost for mutual funds. Specific identification must be made before settlement. - Wash sale: loss disallowed if the same or substantially identical security is bought within 30 days before or after. Loss is added to the new basis. - Capital gain is short term if held one year or less, long term if more than one year. Capital losses offset gains plus $3,000 of ordinary income; the rest carries forward. - Price-weighted (Dow) versus cap-weighted (S&P 500). Compare a portfolio with a benchmark that matches it.
Exam traps
- "Total return is only the price change." It includes income.
- "A gain on a stock held exactly one year is long term." It must be held more than one year.
- "The wash-sale rule applies to gains." Only to losses, and the disallowed loss is added to the new basis, not lost forever.
- "Inherited stock keeps the decedent's basis." It is stepped to market value at death.
- "The Dow weights companies by size." It weights by share price.
Preguntas frecuentes
¿Cómo lo recibo?
Paga y la descarga aparece en esta página al instante. Los enlaces también se te envían por correo. No hace falta cuenta.
¿Y si no es para mí?
Escríbenos dentro de 14 días para un reembolso total, sin preguntas.
¿Va a desaparecer la práctica gratis?
No. Todas las preguntas, el simulacro cronometrado y los capítulos gratis del sitio siguen gratis. Este libro es la mitad de estudio, no una valla alrededor de lo gratuito.
Más preguntas (1)
¿Puedo leerlo en el móvil?
Sí — el EPUB es para móviles y e-readers, el PDF para imprimir y marcar. Recibes ambos.
¿Por qué comprar el libro si la práctica es gratis?
Nuestras preguntas de práctica y el simulacro cronometrado siguen gratis: nada del sitio se esconde tras este libro. El libro de $24.99 es la mitad de estudio: el material en sí, explicado en orden, en un archivo tuyo.
- Enseñanza sistemática — cada sección del examen explicada capítulo a capítulo, de principio a fin, no solo preguntas
- Imprímelo y márcalo — un PDF listo para papel que puedes resaltar, anotar y llevar a tu mesa de estudio
- Estudia en cualquier lugar, sin conexión — EPUB en tu teléfono o e-reader; sin wifi, sin pestañas
- Todo en un solo lugar — los capítulos y las preguntas de práctica en un archivo
- Tuyo de por vida — pago único de $24.99, descarga instantánea, sin suscripción
Los detalles
- Verificado con la fuente oficial(FINRA SIE content outline / SEC, FINRA, MSRB and OCC rules)
- 1,149 preguntas de práctica gratis
Un FINRA SIE exam prep course cuesta $150–$500. Este libro enseña el mismo examen — las mismas reglas, verificadas a los estándares actuales — por un pago único de $24.99 que conservas de por vida.
Compra única, acceso de por vida a la descarga. El eBook es la guía completa de FINRA SIE (Securities Industry Essentials) en PDF y EPUB. Resumen educativo, no asesoría profesional ni legal — confirma siempre las reglas vigentes con la fuente oficial. Última actualización: October 2026.